Understanding USD to CAD Conversions
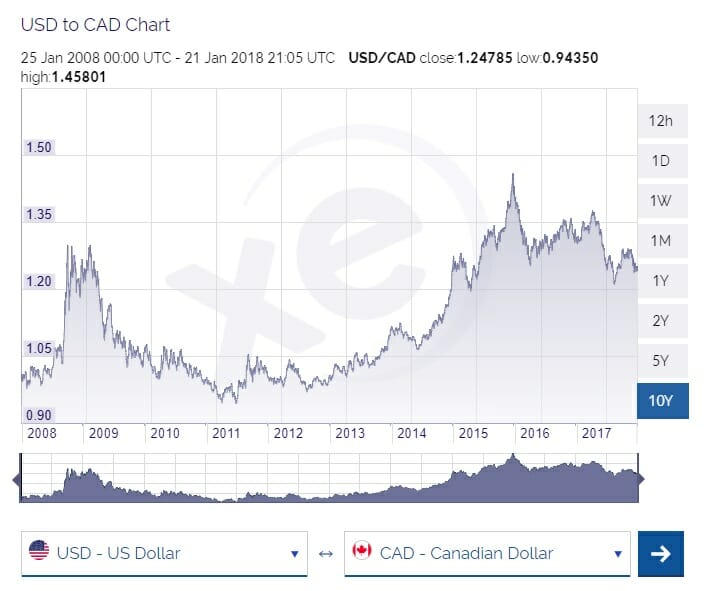
The US dollar to Canadian dollar exchange rate is one of those things that looks simple on the surface but gets complicated fast once you actually need to move money across the border. Right now, 100 USD converts to roughly 136 to 142 CAD depending on where you're looking and when. The spread alone at most traditional banks will eat about two to four percent of your value before you even factor in fees. That's not a typo. A hundred dollars becomes ninety-six. Getting the current rate is straightforward. You check a financial news site, your bank's app, or a currency converter. What's less obvious is why the rate moves the way it does and how to actually take advantage of it. The USD/CAD pair is heavily influenced by oil prices since Canada is a major energy exporter. When crude crosses above seventy dollars a barrel, the loonie tends to strengthen against the dollar. When it dips below sixty, you'll see the pair push toward the one-thirty-five range or lower. This relationship isn't perfect and it's broken a few times recently, but it holds enough that serious savers watch it. I spent years dealing with cross-border payroll for a contractor team split between Alberta and Texas. The problem wasn't the conversion itself. It was timing. We'd agree on a rate at the start of the quarter, the bank would hold it for five business days, and by the time the wire hit, the rate had shifted by three to five percent because of something as mundane as a Canadian employment report or a Federal Reserve comment. We lost maybe two thousand dollars a year on that gap alone. I stopped trying to predict and started using a limit order system through our broker instead. You set the rate you want, the system waits, and it executes automatically when the market hits your number. That cut our average loss down to under four hundred dollars annually. Not sexy. Worked.
Here's something most people miss about the USD/CAD pair. It doesn't move in straight lines. It gaps. Overnight price changes from Asian or European markets can shift the opening rate by a full cent or more before US markets even open. If you're converting on a Monday morning and the rate looked good Friday afternoon, don't assume that price is still available. The gap is real and it happens frequently enough that you should build it into your planning. A gap of zero point zero one on a hundred dollar amount is small. On ten thousand it's a hundred dollars. On a fifty thousand business transaction it's five hundred dollars you didn't plan for. The other thing nobody tells you about bank conversions is the tier pricing. Your rate depends entirely on how much you're moving. Someone converting five hundred dollars gets the retail rate with a wide spread. Someone converting fifty thousand gets institutional pricing with a much tighter spread. If you're doing regular conversions, consolidate. Move larger amounts less frequently. The fee savings usually outweigh the minor rate fluctuation risk between transactions. I've seen people convert five times a year in small batches and pay three times more in total fees than someone who converted twice a year in bulk. Current trends matter more than a snapshot rate. The dollar has been relatively strong against the Canadian dollar through 2024 and into 2025, driven by higher US interest rates and a resilient American economy. But the gap is narrowing. The Bank of Canada has been holding rates steady while the Federal Reserve signals potential cuts. That divergence reversal is the single biggest factor right now. If the Fed follows through on rate cuts through late 2025 and early 2026, the USD/CAD pair could drift back toward one-thirty or even lower. That doesn't mean it will. Interest rate decisions are conditional and data-dependent. But anyone holding US dollars waiting to convert to Canadian dollars should watch the Federal Reserve meetings closely. Those are the inflection points.
Impact on everyday life is real but uneven. Canadians who earn in USD and spend in CAD benefit when the rate is high. US travelers to Canada get slightly better deals right now than they have for a few years. But Canadian exporters face margin pressure when the loonie stays weak, and that trickles down to employment and investment in certain provinces. It's not abstract. The weak dollar environment in recent years has made Alberta energy projects harder to finance and Quebec manufacturing slightly less competitive against US counterparts. These are structural effects, not temporary blips. If you're converting for a purchase, travel, or investment, here's what actually works. Check the mid-market rate first, usually found onXE.com or OANDA. Then compare your bank or transfer service against that mid-market rate. Anything worse than two percent away is a bad deal. Use Wise or Revolut for amounts under five thousand dollars if you can. Their spreads are typically under one percent and they show you the exact fee upfront. For larger amounts, talk to your bank about their wholesale rate tier. Most will quote you the retail rate by default unless you ask for better pricing. You have to push. It takes thirty seconds and saves real money. One edge case that caught me off guard recently. A client needed to convert fifteen thousand dollars but wanted to execute at a specific rate. They set a limit order, the market hit the target, and the trade executed. The money arrived three business days later. The rate had moved half a percent against them during the settlement period because the trade settled on a different day than the execution date. T+2 settlement applies to spot FX, and the rate you see when you place the order isn't necessarily the rate you get. It's almost always very close, but on volatile days it can matter. Just keep that in mind when you're locking in a specific conversion amount for a deadline.
Get the Full Details