How The Victoria's Secret Credit Card Actually Works In Practice
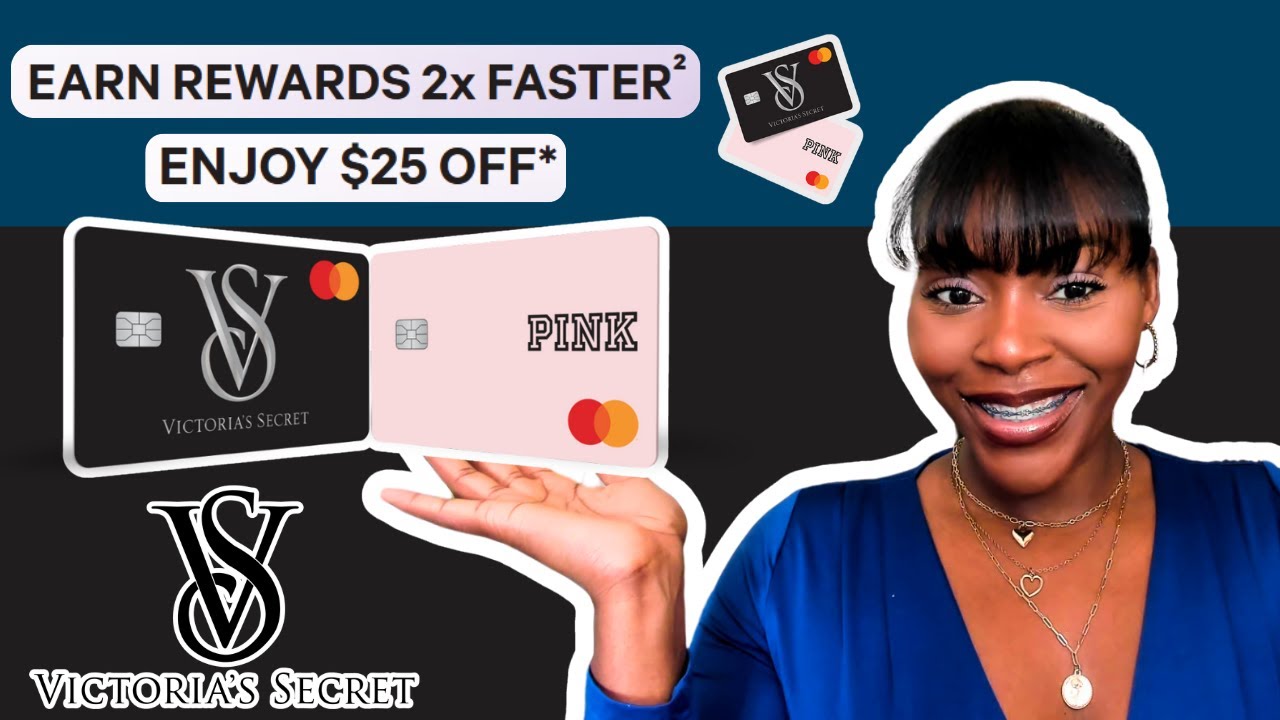
The Victoria's Secret credit card is a store-branded visa issued by Capital One, and it's worth understanding what you're actually signing up for before you apply. The basic structure is that you earn 2 points per dollar on Victoria's Secret and PINK purchases, and 1 point per dollar on everything else. Sign-up bonuses fluctuate but have historically been in the range of 3000 to 5000 bonus points after spending a certain amount in the first few months. You need about 2000 points to redeem for a reward certificate, which typically breaks down to $25 off a single purchase. Here's how I actually use this card and where it makes sense versus where it doesn't. The card is only financially worthwhile if you shop at Victoria's Secret or PINK at least a couple times per year. The 2x point multiplier means you're essentially getting a 1% to 1.25% cashback equivalent on those stores, which sounds thin but adds up during their sale events when you're stacking additional discounts. I hit a specific problem last year that took me about three weeks to sort out. I had accumulated roughly 4,800 points and redeemed them for two reward certificates — one for $25 and another for $50. The $25 certificate applied fine at checkout, but the $50 one kept getting rejected even though my account dashboard showed it as available. The issue turned out to be that the certificate was tied to my online account but the in-store register at the actual retail location wouldn't recognize it because I'd created my account under a slightly different email address than what was linked to my physical loyalty profile. The workaround was calling customer service and having them manually merge the two profiles. It took two calls and about 45 minutes total on hold, but they did resolve it. Going forward I always make sure the email on my account matches exactly between the website and any in-store registration.
The interest rate on this card is approximately 29.99% variable, which is typical for a store card but brutal if you carry a balance. I've seen people make the mistake of using the card for non-Victoria's Secret purchases during the sign-up period just to hit the minimum spend requirement, then carrying that balance for months. At 29.99%, you'll pay more in interest than you'll ever earn back in points. The math is simple: a $500 balance carried for six months at that rate costs you roughly $40 in interest. Your point earnings on that spend would be maybe $6 in value. That's a net loss of about $34, and it's a real trap. Another thing most people miss about this card is the relationship between the My Victoria's Secret Rewards program and the credit card itself. They share a points pool, which is convenient but also confusing. When you apply the card, your existing rewards points don't disappear — they merge automatically. But the redemption thresholds are the same regardless of whether your points came from the card or from in-store purchases with your phone number. Some people assume the card gives you access to exclusive redemption tiers or faster point accumulation on rewards, and it doesn't. The only real advantage is the 2x earning rate on VS and PINK purchases plus the occasional cardholder-only promotion that drops in the app. Cardholder-exclusive promotions are where this card actually shows its value. Victoria's Secret runs periodic sales like the semi-annual PINK event or the Black Friday weekend deals, and cardholders sometimes get early access or an extra 15% off on top of the already-discounted prices. I timed a purchase around one of these windows last year and ended up paying roughly 40% less than the original retail price after stacking the sale discount with the cardholder offer. That's the scenario where the card pays for itself — not from the points, but from the permission to buy deeper into a sale.
If you're applying, there's a practical detail about approval odds that matters. Store cards like this one typically have lower credit score requirements than general-purpose rewards cards. People with scores in the mid-600s have gotten approved here where they'd be declined on a Chase or Citi travel card. That's not necessarily a good thing if your credit is already fragile, because a hard inquiry drops your score by a few points and opening a new account lowers your average account age. If you're actively trying to build credit, this card can work because it reports to all three bureaus and responsible use — paying it off every month — will show up as positive payment history. But if you're already in the process of applying for a mortgage, don't touch this card. The inquiry alone could bump you over a threshold on a conventional loan. The mobile app is where most of the card management happens. You can check your points balance, see available certificates, track promotions, and manage your payment settings. I've found the app to be functional but occasionally slow to sync. There was a period where my points balance didn't reflect purchases I'd made in-store for about 48 hours. It always showed up eventually, but if you're trying to redeem a certificate at the register and the app looks empty, wait a day before assuming something is wrong. Don't start a dispute — just let it settle. There's also a debit card option attached to some versions of this program, but it's not worth getting excited about. It draws from a linked bank account rather than a credit line, so you don't earn the 2x points or the sign-up bonus. It's essentially a loyalty debit card with a branding layer on top. If you're going to deal with another card in your wallet, make it the credit version.
Get the Full Details
The annual fee situation is straightforward: there isn't one. No annual fee, no monthly maintenance charge. That's actually one of the stronger features because it removes the pressure to use the card just to justify keeping it open. You can close it after a year if you want and lose nothing except the potential for future cardholder promotions. The tradeoff is that closing it reduces your total available credit, which can temporarily lower your credit utilization ratio and dent your score by five to fifteen points for a few months. If you plan to keep the account open long-term, just set up autopay for the full statement balance and forget about it until the next sale cycle. For anyone looking at this purely as a shopping tool, the bottom line is that it works if you're already a regular customer. If you're going to Victoria's Secret or PINK once a year for a gift or an occasional purchase, the card is fine to have. If you're not, the 1-point-per-dollar rate on everything else makes it worse than keeping a standard cashback card in your wallet. The points do expire, by the way, if you don't make any qualifying purchase within 24 months. I learned that one the hard way when about 600 points vanished from my account after a long stretch without shopping there.