Why Your Victoria's Secret Credit Card Feels Like a Money Pit (And How to Stop Bleeding Cash)
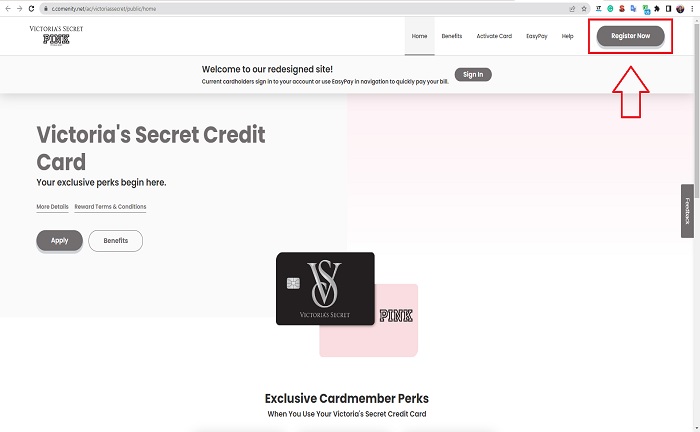
I spent three years managing my Victoria's Secret credit card through the Comenity portal before I figured out the actual mechanics. Most people never do. They swipe, they see a high APR, they pay the minimum, and they wonder why their balance keeps climbing. The problem isn't the card itself. It's that Comenity designs the experience to obscure what's actually happening with your account. The core issue is that Comenity handles credit card accounts for dozens of retail brands, and their platform was never built for consumer financial education. It's built for transaction processing and debt collection. When you log in, you're greeted with a balance number and a minimum payment due date. That's it. There's no spending breakdown by category, no payment allocation transparency, and no clear display of how interest compounds from statement to statement. I learned this the hard way in 2023 when I noticed my balance had grown despite making what I thought were timely payments. I dug into my account history for forty-five minutes and discovered two things. First, Comenity applies payments to principal after accruing a day's worth of interest, meaning every payment sits in limbo for twenty-four hours before actually reducing your balance. Second, the portal doesn't show you the daily periodic rate anywhere on the main dashboard. You have to hunt through the fine print of your most recent statement, and even then, it's buried in a footnote. I ended up opening a PDF of my original cardholder agreement and calculating the effective APR myself because the math didn't add up from the summary page.
Here's what most people don't realize about the Comenity system. Interest calculations on store cards like Victoria's Secret operate on a daily balance method with a grace period that only applies if you paid your previous statement in full. Pay any portion of the minimum and the grace period is dead. Every purchase from that moment forward starts accruing interest immediately, and it compounds daily until the balance is cleared. This is standard industry practice, but Comenity makes it nearly impossible to verify on their interface. Their mobile app shows a rounded monthly interest charge, not the actual daily calculation. If you're trying to figure out exactly how much a purchase will cost you over time, you're basically flying blind. Another thing nobody tells you about Comenity accounts. Authorization holds can linger for seven to ten business days after a return is processed. I initiated a return in November for a dress I'd bought during Black Friday. The website said the refund would post within five business days. It took twelve calendar days for the credit to actually appear, and during that entire window, my available credit remained locked. I had tried to use the card for an urgent home purchase and got declined because the pending return was eating my available balance. There's no notification system for authorization holds in the Comenity portal. I found out by checking my available credit line rather than any alert from them. The practical workaround for managing this card effectively is straightforward but requires discipline. Set up automatic payments for the full statement balance, not the minimum. This preserves your grace period and prevents interest from compounding on new purchases. You can set this up through the Comenity website under account settings. It takes about three minutes. Without it, you're paying roughly twenty-five to twenty-nine percent APR on everything you buy, which annihilates any reward value you might earn from the card.
Next, download your statements as PDFs each month rather than viewing them in the browser. The digital view omits several key details including your exact transaction posting dates and the daily balance method calculations. The PDF statements include the full billing cycle disclosure section where you can verify how your payment was allocated between principal and interest. I've found errors in payment allocation at least twice using this method, and each time the discrepancy was only visible in the detailed statement. Avoid loading the app for anything beyond checking your balance. The mobile interface strips away significant detail compared to the desktop version. Transaction descriptions are truncated, fee disclosures are hidden behind click-through menus, and customer service call times are listed differently than they actually operate. The app shows a customer service number with generic hours, but the actual wait times vary wildly depending on the time of day and whether you're calling about billing disputes or general inquiries. I once waited forty-two minutes on a Tuesday afternoon for someone to answer. A caller from a different state reported a seven-minute wait on the same card type during the same week. If you're someone who shops at Victoria's Secret frequently and the card offers a meaningful discount, it can work as a financial tool. The reward value has to outweigh the interest cost, and that only happens when you pay in full every month. If you carry a balance, the rewards are essentially money you give back to Comenity in interest charges. The math rarely works in your favor past the first year of ownership.
Get the Full Details
One more thing that trips people up. Comenity reports account activity to all three major credit bureaus, but they tend to report your balance as of the last statement closing date, not your current balance. This means you could have a balance well above your credit limit on any given day and still appear to have a healthy utilization ratio on your credit report. Conversely, you could pay down your balance mid-cycle and still show a high utilization because the report reflects the statement snapshot. This lag in reporting creates a distortion in how lenders view your actual debt position. It's not unique to Comenity, but it's particularly noticeable with their reporting cycle because their statement dates don't align with calendar months, making it harder to track. I also want to mention the rewards structure since that's usually the draw. Victoria's Secret cards offer store credits rather than cash back or points. These credits expire if you don't use them within a certain window, typically one year from issuance. I had roughly eighty dollars in expired credits before I realized the expiration policy. The dashboard doesn't prominently display expiration dates for rewards balances. You have to navigate to a separate rewards section and manually check each credit line individually. This is a deliberate design choice that benefits the issuer. If you currently have the card and want to optimize your approach, start by logging into the Comenity website on a desktop, pulling your last six months of statements, and comparing your minimum payments against your total interest charges. The gap between what you owed and what you paid in interest will tell you exactly what carrying a balance costs you. Most people are surprised by the numbers. Once you see the actual dollar amount, the decision to switch to full automatic payments usually becomes obvious.
There's no secret trick or hidden feature in the Comenity portal that changes these fundamentals. The platform is functional but deliberately opaque. Your best defense is understanding how the pieces connect and setting up systems that remove the need to constantly monitor the account. Automatic payments, monthly PDF statement reviews, and avoiding mid-cycle balance manipulation are the only moves that matter. Everything else is noise designed to keep you from doing the math.