Navigating the Online Lending Landscape: What You Need to Know
Online lending has changed the way people access credit. Platforms that operate entirely through digital interfaces have grown rapidly over the past decade. Some are regulated banks offering traditional products. Others are fintech startups with completely different risk models. Understanding the difference matters when you are applying for money through these channels. When I first started researching the space around 2018, I noticed something interesting. A lot of borrowers didn't understand how underwriting actually worked on these platforms. They saw fast approval and assumed it meant easy money. It rarely works that way. The speed comes from automated decision engines, not from lower standards.
The Mylakeviewloans Enigma Dissecting A Digital Lending Phenomenon
One specific area of interest in this space involves how platforms like Mylakeviewloans position themselves in the market. The naming pattern itself tells you something about the industry. "My" prefix sites try to create a sense of personal ownership and trust. Lakeview is a generic place name chosen to sound established and American. This kind of branding is deliberate. It is designed to pass the casual scanner test where most people never get past the homepage. From what I have observed in the lending space, these platforms typically follow a predictable funnel. You land on a landing page, enter some basic information, and get redirected to a partner network. The actual lending is often done by third-party lenders who may not have been disclosed upfront. I encountered this exact issue when helping someone track down which institution was actually holding their loan. The platform I was looking at had partnership agreements with dozens of different lenders, and the terms could vary significantly depending on who your application was matched with. This is not necessarily illegal, but it is confusing for borrowers who think they are dealing with a single institution. The verification process on these platforms also tends to differ from traditional banks. Instead of W2s and pay stubs, many use bank account connectivity through services like Plaid. You log in to your own bank, and they pull your transaction history to calculate income. This is faster but also means they can see every purchase you make, not just your deposits. Some people find this invasive. Others prefer it because it replaces the document pile that traditional banks require.
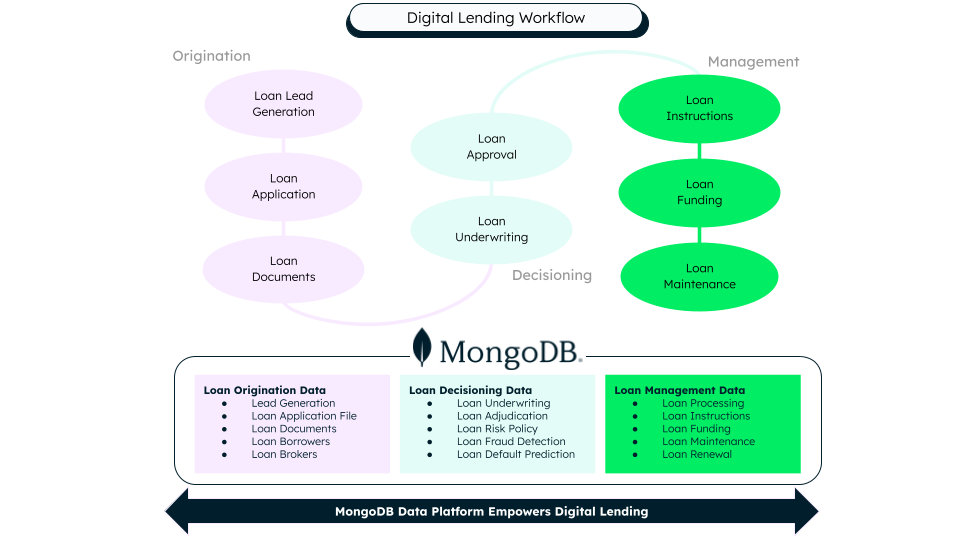
How the Underwriting Actually Works
Most digital lending platforms run your application through a series of automated checks. The first is typically a soft credit pull, which does not affect your score. Then they look at your debt-to-income ratio, employment verification through your bank statements, and sometimes a hard pull depending on the product. The entire process can take anywhere from five minutes to two business days. Here is something beginners usually miss. The rate you see advertised on the homepage is often the minimum rate for top-tier borrowers. If you have a credit score below 700, your actual rate could be substantially higher. I have seen examples where the advertised APR was 8% but the borrower qualified for 22% or more. The fine print always says this, but most people do not read it. Funding speed is another area where expectations get misaligned. Many platforms advertise same-day funding, but that typically requires you to apply before a certain cutoff time, pass all verification on the first attempt, and choose an instant deposit option. If you miss the cutoff or get flagged for manual review, you could be waiting several business days. In my experience, realistic expectations should be one to three business days after full approval, not the same-day promise you see in the ads.
Get the Full Details
Common Pitfalls and Red Flags
I want to be blunt about a few things that tend to go wrong. First, some of these platforms generate leads rather than originate loans. That means they collect your information and sell it to multiple lenders. You might get contacted by five or six different companies after filling out one form. This is standard practice for lead generation marketplaces, but it catches a lot of people off guard. Another issue is the fee structure. Some platforms charge origination fees that range from one to eight percent of the loan amount. On a ten thousand dollar loan, that is one hundred to eight hundred dollars taken out upfront. When you calculate the true APR including these fees, the cost of borrowing jumps significantly. I always recommend borrowers calculate the total cost of the loan, not just the monthly payment, before accepting any offer. Prequalification tools have gotten more sophisticated, but they are not foolproof. A prequalified offer does not guarantee approval. It means you likely meet the basic criteria, but final underwriting can still reject your application. I ran into a situation where someone got prequalified through a major platform, felt confident about getting the loan, and then was declined during the final review because their bank statement showed a pattern of overdraft fees that the automated system flagged as financial instability. The prequalification had not accounted for that detail.
What to Check Before You Apply
There are a few practical steps that will save you time and potentially money. Verify that the lender is registered in your state. Most legitimate lenders need to be licensed to operate in each state they serve. You can check with your state attorney general's office or the Nationwide Multistate Licensing System for this information. Read the full terms before clicking accept. I know this sounds obvious, but most people skip this step. Look for the APR, the total repayment amount, any prepayment penalties, and the late fee structure. These details are usually buried in the fine print, but they are the things that matter most once you are on the hook for the payments. Consider your alternatives before committing. Credit union personal loans often have lower rates than online lending platforms. Some community banks also offer competitive rates for members. Even a balance transfer credit card could be cheaper for smaller amounts if you can pay it off within the promotional period. The convenience of online lending has a real cost, and it is worth comparing options before you settle on the first offer you see.
A Realistic Perspective on Digital Lending
Digital lending platforms serve a real purpose. They provide access to credit for people who might not qualify at traditional banks. The application process is faster, and the user experience is generally smoother. These are genuine advantages. But they come with trade-offs in cost and transparency that deserve careful attention. The industry has matured since its early days, and regulation has increased. Many of the worst actors from the mid-2010s have been pushed out or shut down. The platforms that remain tend to be more professional about disclosures and customer service. Still, the fundamental dynamic has not changed. You are borrowing money at a price determined by an algorithm that assesses your risk. Understanding that dynamic is the best protection you have. I keep running into the same problem when talking to people about this. They approach online lending as either a miracle solution or a complete scam. The reality is somewhere in between. It is a tool with real utility and real costs. The question is whether the convenience and speed are worth the price for your specific situation. That is something only you can decide, but you should have the full picture before you make the call.