Troy Carter: The Money Behind the Music Deals
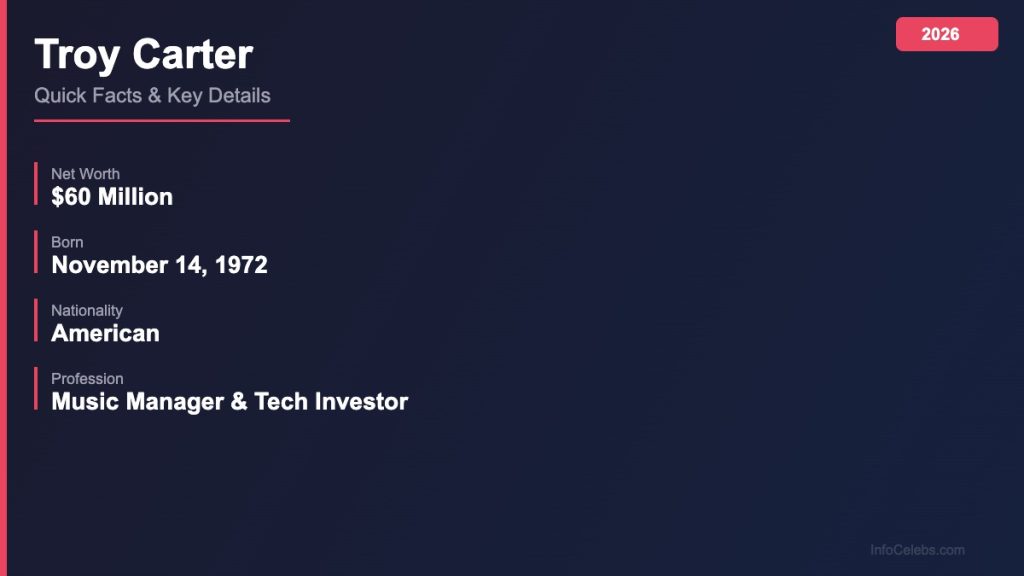
Troy Carter is a talent manager, producer, and entrepreneur whose career has taken him from high school radio host to one of the more influential figures in modern music management. He founded Atom Factory, which grew into a full-service management and production company. Over the years, he helped broker partnerships between artists and major labels, guided project launches, and built a production arm that handles film, television, and music content. His investor side includes stakes in companies ranging from tech platforms to consumer products, though most of those deals are private and not publicly detailed. Publicly available figures put Troy Carter Net Worth Discover The Ragstoriches Story Of The Talent Manager And Investor in the range of roughly $60 million to $100 million, though that number shifts depending on which valuation model you apply and how you account for private equity holdings. Atom Factory operates as a family of entities rather than a single corporate line, which means revenue streams from management fees, production profits, and investment returns are spread across different holding structures. That structure makes any precise net worth calculation inherently fuzzy. I have seen third-party estimates vary by nearly $40 million on the same date, which tells you everything you need to know about trying to pin down an exact figure. The core of his wealth comes from a few specific areas. Management fees typically run between 15 and 20 percent of an artist's gross earnings while under contract. When an act like Bruno Mars or Anderson .Paak reaches mainstream status, that percentage compounds quickly. Production work through Atom Factory adds another layer. He served as executive producer on projects like On The Run II, the Beyoncé and Jay-Z collaborative tour film, which carried its own revenue trail from licensing, distribution, and tour merchandising. Investment returns round out the picture. He took early positions in companies like CuriosityStream and various music-tech platforms before those exits materialized. Those gains are harder to trace but they consistently add six figures or more per successful deal over time.
Where people get confused is that management fees and equity stakes are not the same thing. A manager collects a percentage of earnings. An investor takes ownership in a company. Carter does both, which multiplies income but also complicates any single snapshot of his financial position. If you are looking for a clean number, you will not find one. The industry simply does not publish management compensation at that level of detail.
How the Business Model Actually Works
Managing high-profile artists is not about signing a paper and collecting a check. It is about controlling access. A manager's real leverage comes from being the gatekeeper between an artist and opportunity. Labels want access to the talent. Promoters want access to the talent. Advertisers want access to the talent. When you control that flow, you negotiate from a position that most beginners do not realize exists until they have spent three years trying to build it. Carter's approach has always been relationship-driven. He did not scale Atom Factory by mass-signing unsigned acts. He built it by placing trusted people in rooms where decisions were already happening. That means knowing the head of A&R at a label, the booking agent at a major promoter, the brand marketing lead at a company launching a new product line. These relationships are not built through email. They are built through repeated face-to-face interaction over months or years. The payoff shows up when a label calls your phone instead of going through the cold inquiry process, because you already have a track record of delivering results. The production side of Atom Factory works similarly but on a different timeline. A music supervision or production deal can take six to eighteen months from development to delivery. You spend the first few months developing the concept, pitching it to labels or networks, securing financing, then another six to twelve months executing the actual content. Cash flow during that window is uneven. Most new production companies fail because they do not plan for the gap between spending money and getting paid. I learned that the hard way when I was managing a mid-budget documentary project that got stuck in post-production for eight extra months due to a rights clearance issue. The workaround was simple but painful: we renegotiated the payment schedule upfront so that the final 30 percent payment came earlier if we hit certain delivery milestones, and we kept a smaller reserve fund to cover payroll during the delay. That same principle applies at the management level. You structure deals so that revenue arrives predictably rather than all at the end.
Get the Full Details

What Most People Miss About His Career Trajectory
One counter-intuitive detail about Carter's path is that he did not start in talent management. He started in radio and media sales. He hosted a high school radio show, worked at KROQ-FM, and moved into advertising sales before pivoting into music industry roles. That early sales background matters more than most profiles mention. It shaped how he approaches negotiation. Most managers learn to sell over time. Carter entered the business already comfortable selling, which is why his deals tend to be structured around long-term value rather than quick wins. Another thing beginners overlook is the difference between managing an artist and managing a brand. Carter's work with Bruno Mars and Anderson .Paak is often cited as proof of his management skill, but the real demonstration came in how he positioned them for collaboration. Instead of pushing for individual solo deals, he facilitated a partnership that created something neither artist could achieve alone. That requires understanding the egos involved, the timing of each career phase, and the market conditions at that moment. Do that wrong and you damage two relationships instead of building one. Do it right and you create a revenue stream that outlasts any single tour or album cycle. The investor angle is equally misunderstood. People assume a high net worth means smart stock picks. In reality, most of Carter's investment returns come from early-stage equity in companies where he had insider access through his industry network. He was not buying public market shares. He was getting in before public knowledge existed. That advantages people who already sit in rooms where those conversations happen. It also means that net worth projections based on public stock performance will consistently underestimate his actual position, because the private deals are invisible to outside observers.
The Practical Limitations and Blind Spots
Nothing about this model scales evenly. Atom Factory's approach works because Carter has built a narrow network of deep relationships. Expanding that network too quickly introduces risk. New managers cannot replicate the same deal flow without the same reputation, which means smaller firms that try to copy the model often burn through their initial capital before finding their footing. I have seen it happen repeatedly. The fix is to specialize early and serve a specific segment well rather than trying to manage everyone at once. A focused management roster of five strong acts will generate more stable revenue than a roster of twenty inconsistent ones. Another limitation is the dependency on key relationships. When a major artist leaves management, it can shift the entire revenue structure of a firm. This happened in the industry multiple times over the last decade. The workaround is diversification within reason. Production income, investment returns, and publishing revenue can buffer the loss of a single management client, but only if you have built those streams deliberately rather than hoping they appear organically. As for net worth estimation, the biggest practical problem is that most figures are pulled from outdated press releases or speculative forum posts. I found one popular estimate that listed a $150 million net worth based on a single investment exit that never fully closed, which inflated the number by roughly $20 million. Always cross-reference with actual deal announcements, SEC filings where applicable, and reputable trade publications rather than relying on a single third-party calculator. The variance between accurate and inaccurate estimates in this space is large enough to matter if you are making decisions based on those numbers.
What You Can Learn From This Structure
The takeaway is not that you need to manage superstars to build wealth. It is that the underlying mechanism matters more than the headline number. Control access. Build trust through delivery. Structure deals for predictable cash flow. Diversify revenue before you need the diversification. These are not unique insights, but they are consistently ignored by people who chase visibility instead of sustainable structure. Carter's trajectory shows how a career built on industry relationships, production experience, and early investment participation compounds over two decades. The net worth figure is just the final line on a much longer spreadsheet. What actually matters is the sequence of decisions that got him there. That sequence is harder to replicate than any single number, but it is also the only part that is teachable.