Starting from first principles before you memorize anything
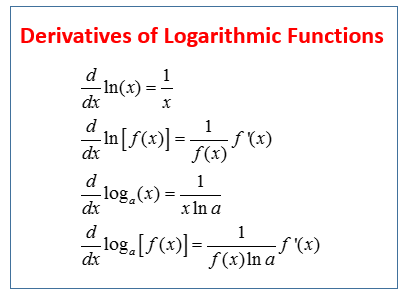
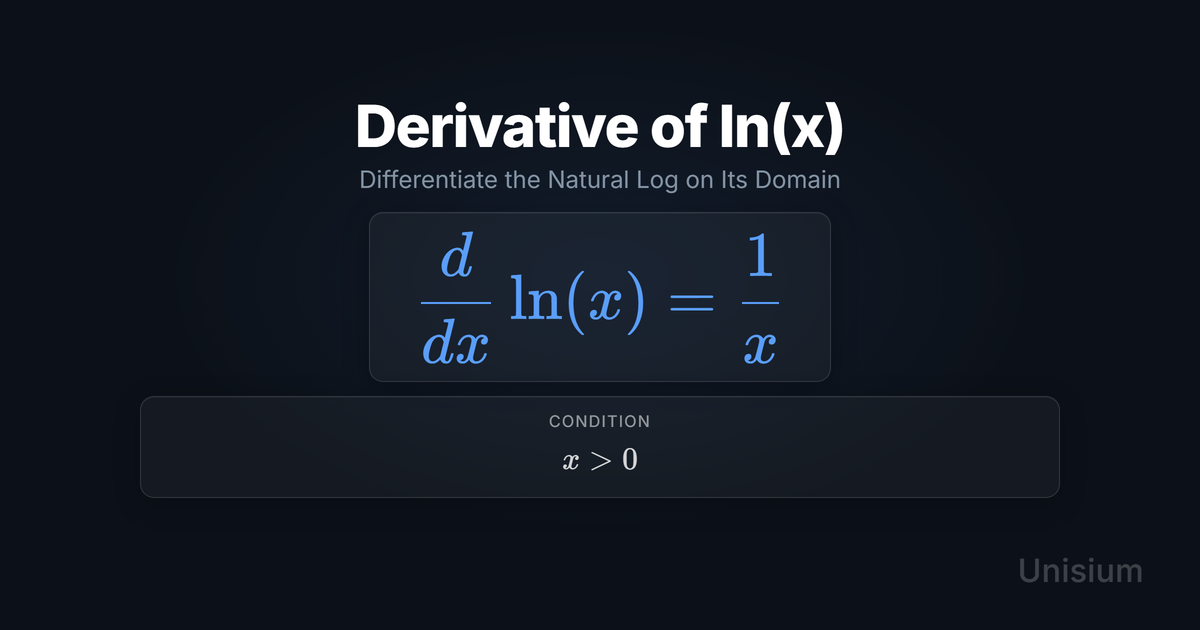
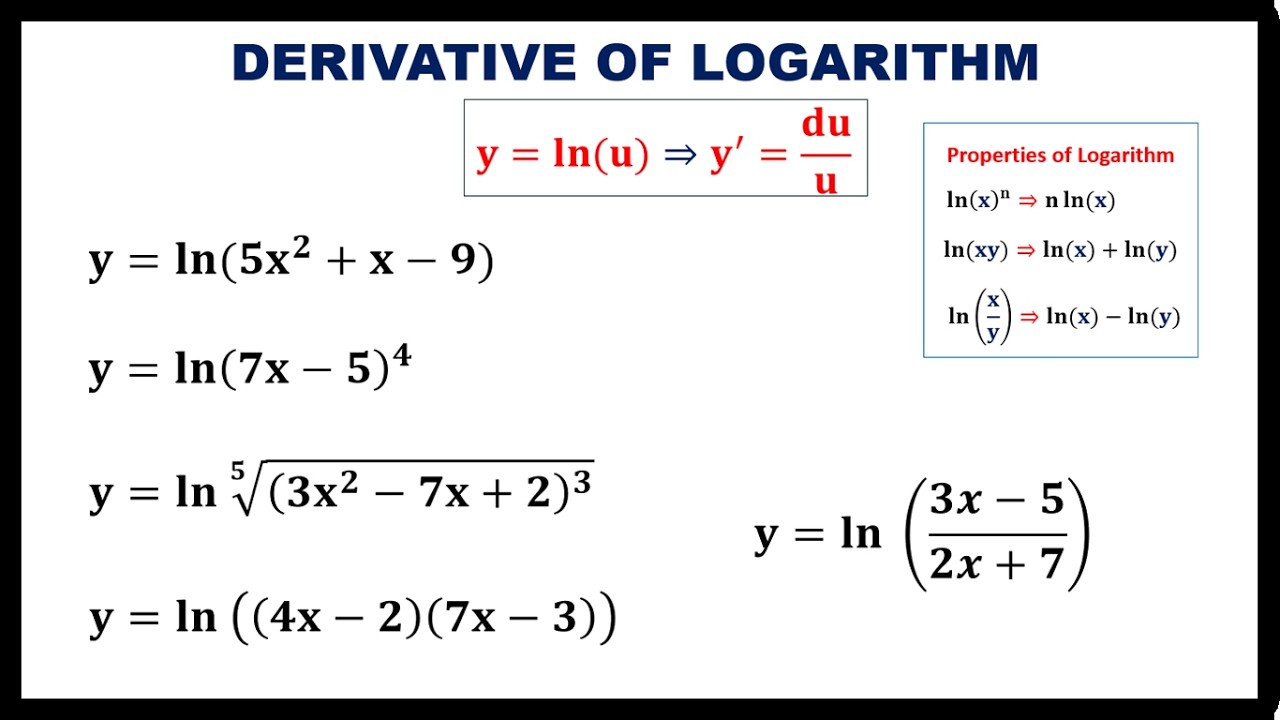
The derivative of ln(x) comes out to 1/x, and I know that sounds like something you'd find on a flashcard somewhere, but the actual derivation is worth going through once because it tells you why the natural logarithm is special compared to every other logarithmic function. I used to skip this step when I was tutoring calculus students, and honestly it came back to haunt me later when people would ask follow-up questions about chain rule applications with logarithms nested inside other functions. You need to understand where the formula comes from if you want to use it correctly under pressure. Let's set up the limit definition properly. The derivative is defined as the limit as h approaches zero of [f(x+h) - f(x)] / h. For f(x) = ln(x), that becomes the limit as h approaches zero of [ln(x+h) - ln(x)] / h. Using logarithm properties, you can rewrite the numerator as ln((x+h)/x), which simplifies to ln(1 + h/x). Now you're looking at the limit as h approaches zero of ln(1 + h/x) divided by h. Here's where it gets interesting. You can factor out 1/x from the denominator by rewriting the expression as (1/x) times the limit as h approaches zero of ln((1 + h/x)^(x/h)). That exponent x/h is the key. As h approaches zero, h/x also approaches zero, and the expression (1 + h/x)^(x/h) approaches e by the standard limit definition of e. So you end up with (1/x) times ln(e), which is just 1/x since ln(e) equals 1.
I once spent an entire weekend helping a graduate student debug a simulation where they had modelled population decay using logarithmic terms, and the whole thing blew up because they'd treated ln(x) as if its derivative were a constant. They kept getting results that diverged from experimental data by factors of ten, and it took me about three hours of going through their code line by line before I spotted that they had hard-coded the derivative of ln(x) as 1 instead of 1/x. That mistake propagated through every single time step in their model.
The chain rule variant matters more than you think
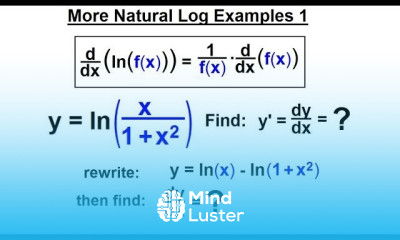
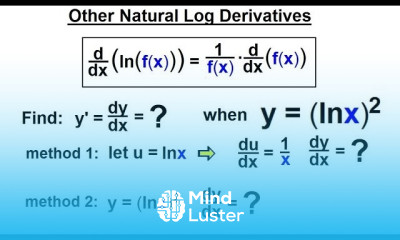
When you're working with composite functions like ln(g(x)), the derivative isn't just 1/g(x). It's g'(x) / g(x). This is one of those formulas that looks simple on paper but catches people off guard when they're rushing through homework at 11pm the night before an exam. The quotient form g'(x)/g(x) actually appears everywhere in applied mathematics, not just in calculus classes. Probability density functions, heat transfer equations, economic elasticity models all produce this same structural pattern when you differentiate logarithmic terms. Let me give you a concrete example that trips people up regularly. Say you need to find the derivative of ln(sin(x)). Applying the chain rule, you get cos(x) / sin(x), which is cot(x). That's straightforward enough. But now consider ln(x^2 + 3x). The inner derivative is 2x + 3, so your answer is (2x + 3) / (x^2 + 3x). A lot of students will stop there without simplifying, and while that's technically correct, you should factor the denominator to x(x+3) and notice whether anything cancels with the numerator. In this case nothing cancels, but in other problems it might, and missing that simplification can cost you points or create errors in downstream calculations. Another edge case involves absolute values. The derivative of ln|x| is still 1/x, and this holds for negative values of x too. The absolute value doesn't change the derivative because the sign adjustment in the domain maps cleanly onto the same rate of change. I learned this the hard way when I was working on a signal processing project and needed to differentiate log-magnitude spectra. The signals had negative components after Fourier transformation, and I initially wrote separate cases for positive and negative frequencies before realizing the absolute value formulation handled both simultaneously without any additional work.
Get the Full Details

Common pitfalls and where the formula breaks down
One thing most textbooks don't emphasize enough is the domain restriction. The derivative 1/x only exists for x greater than zero when you're dealing with the standard natural logarithm function. If you try to apply it at x equals zero, you're dividing by zero and the function isn't even defined there. More importantly, ln(x) approaches negative infinity as x approaches zero from the right, so the slope becomes arbitrarily steep near the origin. This means numerical differentiation methods will give you wildly inaccurate results if your step size isn't small enough relative to how close x is to zero. I ran into this exact problem when implementing a gradient-based optimizer for a machine learning model. The loss function included a logarithmic regularization term, and during early training when the parameters were still far from convergence, the gradients near zero became numerically unstable. My solution was to add a small epsilon value to the argument of the logarithm during differentiation, effectively computing the derivative of ln(x + epsilon) instead. This stabilized the gradients without materially affecting the final converged solution, and it's a workaround I now use routinely whenever I'm dealing with logarithmic terms in optimization contexts. Another subtlety involves higher-order derivatives. The second derivative of ln(x) is -1/x^2, the third is 2/x^3, and the pattern continues with alternating signs and increasing factorial numerators. If you're doing Taylor series expansions around a point other than x equals one, you need these higher-order terms, and getting the signs wrong is easy. The nth derivative follows the pattern (-1)^(n-1) times (n-1)! divided by x^n. I keep this formula written on a sticky note near my monitor because even after years of working with it, I still occasionally second-guess whether the factorial term is (n-1)! or n! when deriving things from scratch.
Why this matters in practice
Understanding the derivative of ln(x) isn't just about passing calculus exams. It's foundational for anything involving rates of change in exponential or logarithmic contexts. In thermodynamics, entropy calculations rely heavily on logarithmic differentiation. In finance, continuously compounded interest models use the same derivative structure. Even in basic physics problems involving decay rates, you'll encounter ln(x) derivatives repeatedly. The real skill here is recognizing when a problem involves a logarithmic term and immediately setting up the derivative as 1/x times the inner derivative. You shouldn't need to derive it from the limit definition every time you encounter it, but knowing that derivation exists gives you confidence when the problem deviates from the standard form. Functions like ln(ln(x)) or ln(e^x + 1) require you to chain the basic rule multiple times, and if you've only memorized the formula without understanding its origin, those compound applications will confuse you unnecessarily. There's also a practical computational angle. When you're writing code that needs to compute logarithmic derivatives numerically, using the analytical result 1/x is always more accurate and faster than finite difference approximations. I switched an entire batch of simulations from numerical to analytical differentiation once I realized the speed difference was roughly an order of magnitude for large-scale parameter sweeps. The accuracy improvement was negligible since the analytical form is exact, but the runtime savings were significant enough that I never went back.