How Semi-Annual Periods Actually Work
The simplest thing to understand is that semi-annually just means something happens twice a year, every six months. It is used everywhere from bond coupon payments to insurance premiums to corporate earnings reports. The term itself comes from the Latin prefix meaning two, combined with a word for year. In practice, it is less straightforward than people assume, which is why so many spreadsheets break when they try to handle it. I used to work in treasury operations, and the first time I tried to automate a semi-annual payment schedule for a commercial loan, I learned pretty quickly that six-month intervals are not evenly spaced in calendar terms. February exists. Leap years exist. Different month-end days create headaches. A loan originating on January 31 doesn't land cleanly on July 31 in every jurisdiction. You have to decide which day-count convention you are using, and that decision changes everything about your calculations.
What Is Semi Annually The Definitive Guide To Sixmonth Intervals In Finance And Beyond
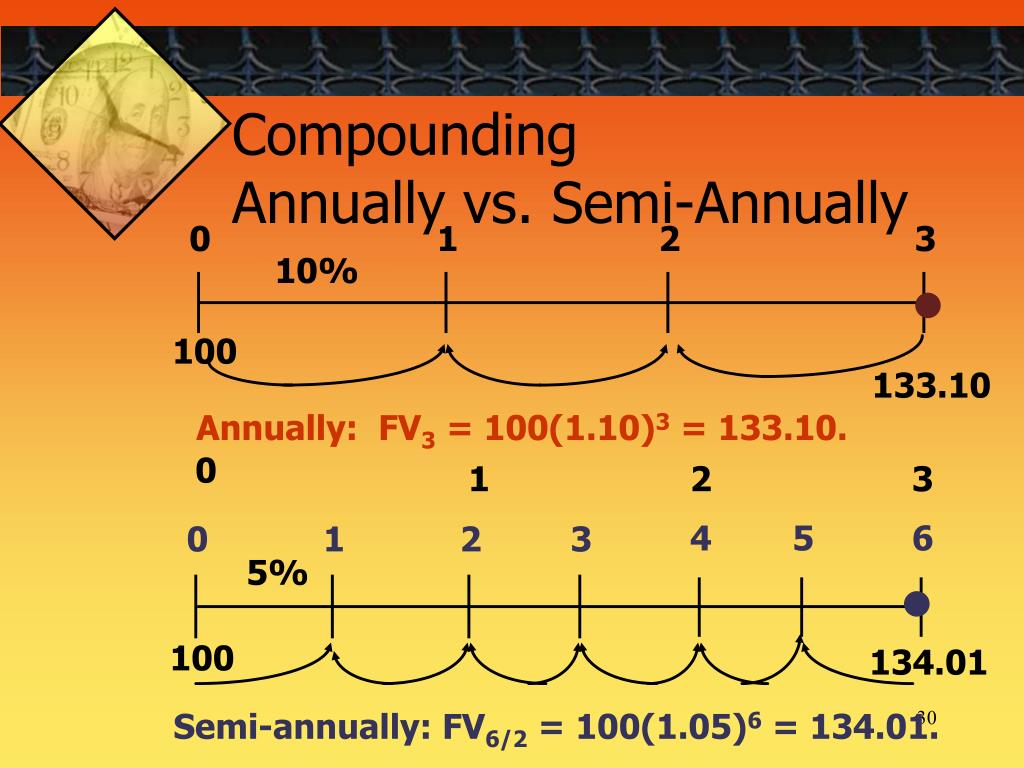
At its core, semi-annual means a period of six months or an event occurring twice per calendar year. In finance, the two most common uses are interest compounding and payment scheduling. When a bond pays semi-annually, it makes two coupon payments per year instead of one. When an interest rate compounds semi-annually, the annual rate is divided by two and applied twice. That division matters because of how effective annual yields work. A nominal rate of 8 percent compounded semi-annually does not equal 8 percent effective annual yield. The actual return is 8.16 percent. Most people miss that. They see 8 percent and assume they get 8 percent back. It is a small difference on small balances but it compounds literally over time and becomes significant on larger positions. I have seen junior analysts sign off on valuations where they treated a semi-annual compounding rate as if it were a simple annual rate. The numbers looked close enough on a spreadsheet that nobody caught it until the audit.
The Mechanics of Six-Month Scheduling
Semi-annual dates are usually calculated using one of three methods. The act/360 method counts the actual number of days between payment dates and divides by 360. The 30/360 method assumes every month has 30 days and every year has 360 days. The act/act method uses actual days in each month and actual days in the year, which means leap years matter. Bonds typically use 30/360 for corporate bonds and act/360 for Treasuries. Mutual funds and money market instruments often use act/360. This inconsistency is something most beginners never encounter until they are trying to match cash flows across different instrument types and their reconciliation fails by a few basis points. A few basis points sounds trivial. On a multi-million dollar portfolio it is real money. I once spent an entire afternoon tracking down a discrepancy in a bond fund's dividend distribution. The fund manager was applying 30/360 logic to municipal bonds that should have used act/360. The error was roughly 0.03 percent annually, which translates to about 30 basis points per year in accrued interest. Over the life of a position it accumulated enough to matter. The workaround was fairly simple: I wrote a script that checked the CUSIP prefix to determine the bond type and routed it to the correct day-count convention automatically. It took about four hours to build and saved me from doing that reconciliation by hand for the next three years.
Get the Full Details
Common Pitfalls That Nobody Warns You About
The first pitfall is assuming that semi-annual always means exactly 182 or 183 days. It does not. Some semi-annual periods have 184 days. Some have 181. February makes this unpredictable. If your start date is January 31 and your end date is July 31, that is 181 days in a normal year and 182 days in a leap year. If your periods are fixed at 182 days regardless, you are implicitly assuming a consistent day count that does not exist in reality. The second pitfall is confusing semi-annual with biannual. These words are often used interchangeably in casual conversation but they mean different things in finance. Semi-annual means twice a year, evenly spaced. Biannual can mean twice a year or once every two years depending on context. I have seen internal documents where the writer meant one thing and the reader assumed another, leading to whole quarters of misaligned reporting schedules. The fix is simple: always write out semi-annually or specify the exact months if there is any chance of confusion. A third issue shows up in compounding calculations. When someone says a savings account pays 5 percent semi-annually, they might mean 5 percent nominal compounded semi-annually or they might mean 5 percent effective yield paid semi-annually. These produce different results. The nominal interpretation gives you 2.5 percent per period multiplied by two, totaling 5 percent with some effective yield bump. The effective interpretation means the total annual return is exactly 5 percent split across two payments. Banks and credit unions sometimes use the terminology loosely and customers get surprised.
I encountered this when a client called me furious about a Certificate of Deposit that advertised a semi-annual rate. They expected double their periodic payment to equal the advertised annual rate. The institution had quoted the periodic rate as the annual nominal rate divided by two, which is standard, but their marketing materials made it look like the periodic rate was the full annual amount. The difference between a 5 percent nominal rate and a 5 percent effective rate on a $50,000 CD over one year is about $12.75. Small amount to an individual but enough to cause a complaint that took me two hours to resolve.
Practical Applications Beyond Bonds
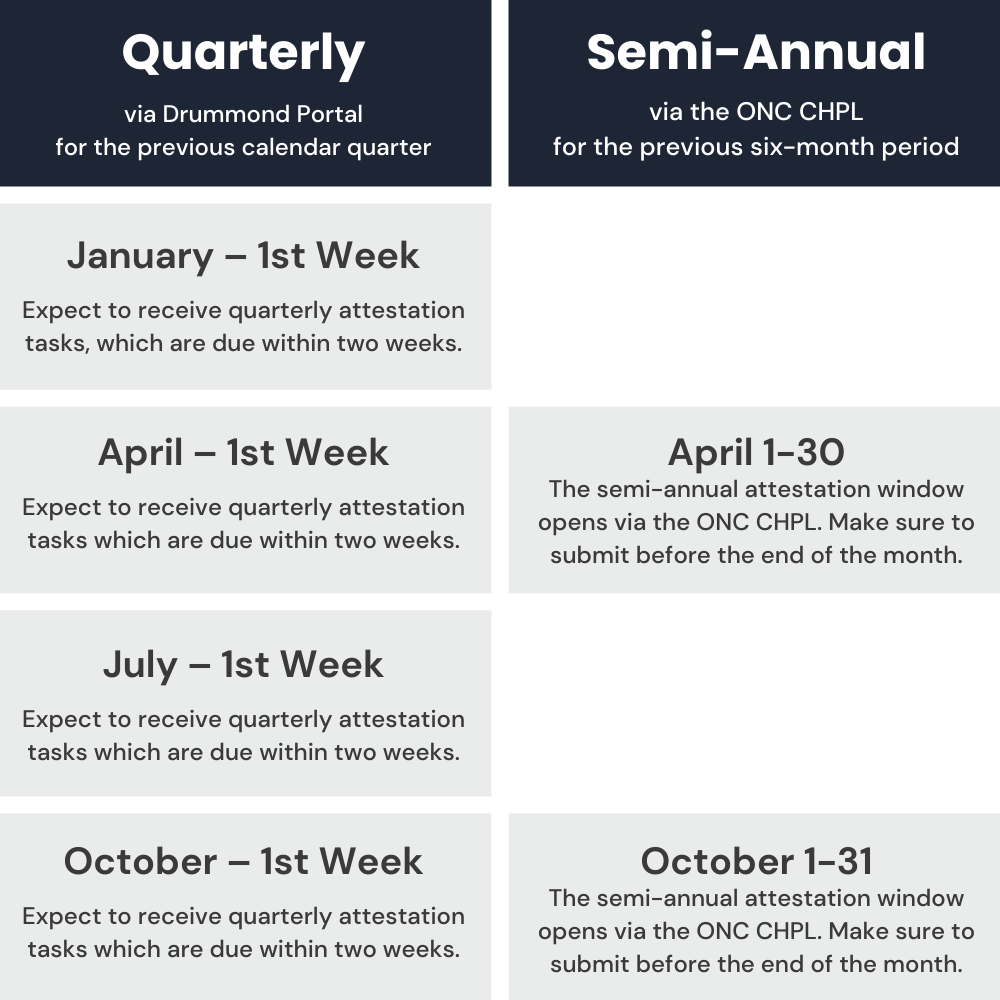
Semi-annual intervals appear in insurance premium billing, property tax assessments, royalty payments, dividend distributions, and lease agreements. Commercial real estate leases frequently use semi-annual rent escalations tied to CPI or fixed percentages. Royalty agreements in media and publishing often structure payments semi-annually because sales data typically takes two to three months to compile after a half-year closes. Tax reporting in the United States uses semi-annual estimated payment deadlines for individuals and businesses. June 30 and December 31 are the standard cutoffs for many semi-annual reporting requirements, though the exact dates vary by jurisdiction and entity type. Corporate tax extensions push some deadlines to specific months depending on the fiscal year structure. Regulatory filings often follow semi-annual schedules too. SEC Form 10-K is annual, but many international exchanges require semi-annual financial statements. Companies with dual listings in New York and London, for example, need to reconcile two different reporting cadences. I worked with a mid-cap company that had to adjust its entire earnings release process when it added a London Secondary Listing. Their finance team had never produced a semi-annual report before and the IFRS requirements differed from US GAAP in ways that mattered for their revenue recognition timing.
How to Calculate Semi-Annual Payments Yourself
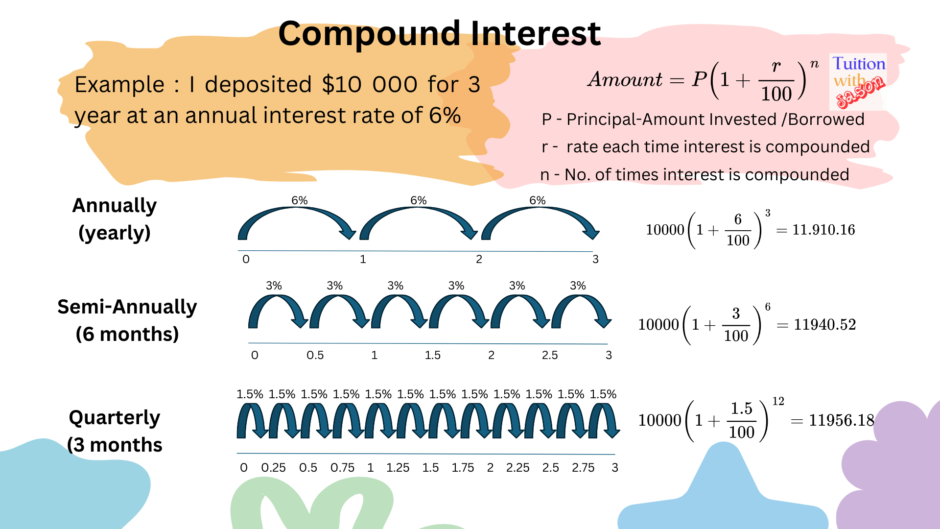
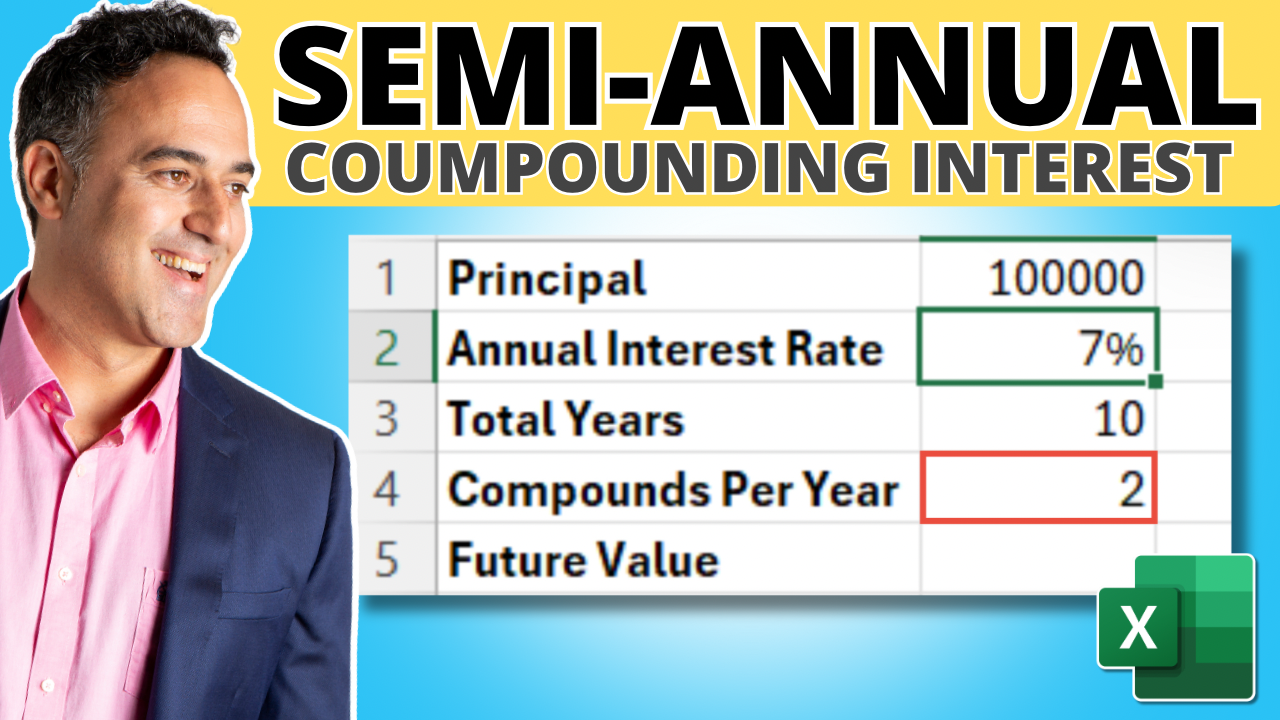
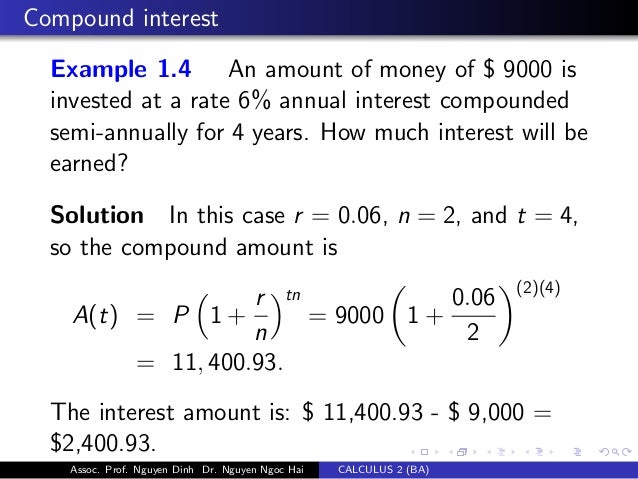
If you need to compute semi-annual payments manually, start with the nominal annual rate and divide by two. Apply that periodic rate to the outstanding principal balance. For loans, use the standard amortization formula adapted for semi-annual periods. The number of periods is the loan term in years multiplied by two. The periodic rate is the annual rate divided by two. For compound interest calculations, the formula becomes future value equal principal times one plus the periodic rate raised to the number of periods. If you are investing $10,000 at 6 percent nominal rate compounded semi-annually for three years, your periodic rate is 0.03 and your number of periods is six. The result is $10,000 times 1.03 to the sixth power, which equals approximately $11,940.52. The effective annual yield here is 6.09 percent, not 6 percent. Excel handles this cleanly with the PMT function when you adjust the rate and nper arguments. Rate becomes annual_rate divided by 2 and nper becomes years multiplied by 2. If you forget to adjust both, you get a wildly incorrect payment amount. I have seen this mistake in three different audit engagements. Usually it shows up as a payment that is about 40 percent too high because the formula is treating an annual payment as if it were semi-annual without the rate adjustment, or vice versa.
When Semi-Annual Doesn't Make Sense
Semi-annual scheduling works fine for stable, long-term instruments. It breaks down for short-term products or volatile environments. Money market funds distribute income daily because their yields change too frequently to lock into a six-month schedule. Variable rate demand obligations may reset monthly or even weekly. Forcing a semi-annual framework onto these instruments introduces lag that can distort pricing and risk measurements significantly. Inflation-indexed securities present another problem. Semi-annual coupon payments on TIPS are calculated on an adjusted principal, meaning the payment amount changes with the Consumer Price Index. The semi-annual structure is still there but the cash flow is unpredictable. Budgeting around semi-annual TIPS payments requires a range rather than a fixed number, which most retail investors struggle to model accurately. Global markets add currency risk to semi-annual structures. A Japanese bond paying semi-annually in yen exposes a US investor to yen movements between the coupon dates. The six-month gap between payments means the dollar-value of the coupon is unknown until payment day. Hedging this gap requires forward contracts or options, and those hedges cost money that eats into the semi-annual yield advantage. For small investors the cost usually outweighs the benefit. For institutional investors it is routine.
The main takeaway is that semi-annual is a convention, not a universal rule. It simplifies accounting and reporting but introduces calculation nuances that trip people up when they treat it as a simple binary. Learn the day-count conventions for whatever instrument you are working with. Verify whether a quoted rate is nominal or effective. And double-check your compounding assumptions before signing off on anything that involves money.