Understanding Basis Points Without the Finance Brospeak
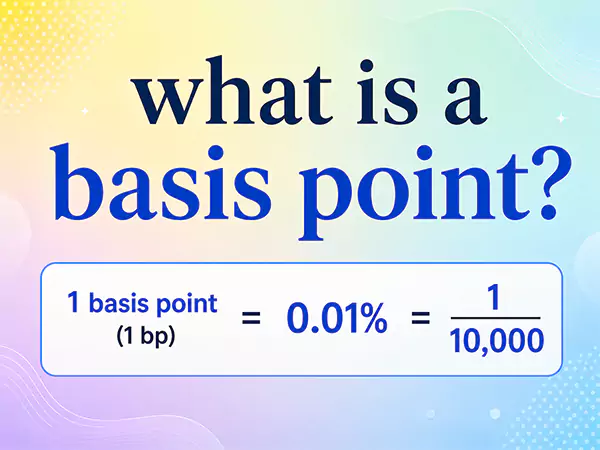
A basis point is one hundredth of a percent, or 0.01%. That is it. There is nothing mystical about it. You will see it used everywhere from bond yields to mortgage rates to Fed policy statements, and people will deliberately complicate it because it makes them sound important. It is not complicated. A basis point is just a way to talk about small percentage changes without getting lost in the decimal places. When the Federal Reserve says it is raising rates by 25 basis points, that is a quarter of one percent, or 0.25%. When a mutual fund's expense ratio drops from 0.75% to 0.60%, that is a 15 basis point improvement. When a treasury yield moves from 4.10% to 4.15%, you are looking at a 5 basis point shift. The math is trivial. The convention matters because in global finance, everyone needs to agree on the language before they trade. The reason basis points exist at all comes down to ambiguity. If someone says rates went up "one percent," do they mean 1 percentage point, or 1 percent of the current rate? That difference is enormous when you are talking about a 5% yield. One interpretation gives you 6%. The other gives you 5.05%. Basis points remove that entire class of errors. A move from 5% to 6% is a 100 basis point change. A move from 5% to 5.05% is a 5 basis point change. No confusion.
I ran into this exact problem once when reconciling trade confirmations between two desks that used different conventions. One team quoted everything in percentages, the other in basis points. A coupon shift that one side recorded as a 125 tick direction was actually 1.25 percentage points, or 125 basis points. The P&L didn't reconcile until we figured out that one desk had interpreted a basis point as a full percentage point and the trade tickets had been entered accordingly. We ended up writing a quick lookup script that flagged any discrepancy larger than 10 basis points between the two systems. That script caught about six trades a day that would have otherwise sat in limbo for weeks. Took me about three hours to build, saved maybe twenty hours per week in manual reconciliation. Here is something most beginners miss: basis points are not linear in how they feel across different asset classes. A 10 basis point move in short-term Treasury bills is practically noise. A 10 basis point move in a 30-year corporate bond can trigger actual hedging activity. The same number, completely different market impact depending on duration and liquidity. If you are trading fixed income and only think about the magnitude of the basis point move without considering the instrument's duration, you will consistently underestimate your risk. Duration tells you approximately how many basis points of yield change translate into price change. A bond with a duration of 7 years will move roughly 7% in price for every 100 basis point shift in yield. Roughly, because convexity matters at larger moves. Another thing people get wrong is assuming basis points always apply cleanly to percentages. They do not work the same way on negative yields, which have become more common in European and Japanese government debt. If a bond yields minus 0.50% and then moves to minus 0.45%, that is still a 5 basis point improvement, but calling it a 10% increase in yield is technically true and completely misleading in practice. Nobody talks about it that way, but spreadsheet models that blindly divide one yield by another will produce bizarre results. Always check whether your calculation is treating the numbers as basis point deltas or as percentage ratios.
For practical use, here is how you actually convert between the two without pulling out a calculator. Multiply basis points by 0.0001 to get a percentage. Divide basis points by 100 to get a percentage point decimal. To go the other direction, multiply the percentage change by 10,000. A 0.375% change equals 37.5 basis points. That half-point is where people start making rounding errors in their heads, especially when working with bond coupon adjustments or credit spread quotes that often land on quarter-points or even eighth-points of a basis point in institutional markets. If you need to track basis point movements across a portfolio, the easiest approach is to create a simple reference table rather than relying on mental math during trading hours. List your positions, note their current yields, and calculate the basis point distance from your entry yield. Most professional trading platforms do this natively now, but if you are working in something basic like Excel, a straightforward formula using the absolute value of the yield difference multiplied by 10,000 will give you the basis point figure you need. The trick is remembering to multiply by 10,000, not 100. That mistake will show up repeatedly in junior analyst work and I have seen it enough times to know it is worth pointing out. Basis points also show up in fee structures, insurance pricing, and even algorithmic trading parameters. A hedge fund manager might charge a management fee of 200 basis points on assets under management. That is 2%. A private credit fund might price its spread at SOFR plus 400 basis points. The language is consistent across these domains, which is useful because it means once you are comfortable converting between basis points and percentages, you can read almost any financial document without stumbling over the notation. The notation itself is standardized enough that Bloomberg terminals, Reuters screens, and even most retail broker platforms will display both values side by side if you ask them to.
Get the Full Details

The biggest limitation of basis points as a communication tool is that they become unwieldy for extremely large moves. Nobody says a rate increase of 500 basis points. They say five percentage points. The convention breaks down past 100 basis points because it is clearer to just switch back to percentage points. Smart traders and analysts know when to make that switch without being asked. Staying rigid about basis points regardless of magnitude just makes you look like you do not understand market convention. If you want a quick reference, there is no single download that matters here. The conversion is simple enough that a basic spreadsheet or even a calculator app with a custom formula will serve you. The real value is in internalizing the scale through exposure. After watching a few dozen earnings calls and rate decisions, you will start seeing basis point movements as intuitive numbers rather than something you have to convert each time. That is the whole point of the convention in the first place.