How VSP's Provider Network Actually Changes What You Pay at the Eye Doctor
I spent seven years working in optometric billing before moving to the practice management side, and the thing most people don't understand about VSP is that the plan isn't one uniform contract. It's a network model where each provider has a different reimbursement tier, and that matters more than the brochure makes it look. VSP operates on a hybrid network structure. They have contracted providers who accept VSP as direct billing, and then there's the non-contracted pool where you get reimbursed at a lower rate. The average contracted provider will cover the annual exam copay at $0 to $10 depending on your specific plan tier. Non-contracted can run you $25 to $40 out of pocket for the same service. The benefit is access. VSP has roughly 25,000 to 30,000 authorized providers across the United States. In rural areas, that number drops significantly. I had a member in central Illinois who drove 47 miles to the nearest contracted VSP provider because there were exactly two in the county, and one was booked three weeks out. She ended up using a non-contracted provider two towns over and got reimbursed at 80 percent of the allowed amount instead of having it billed directly. That saved her about sixty dollars but cost her the paperwork headache.
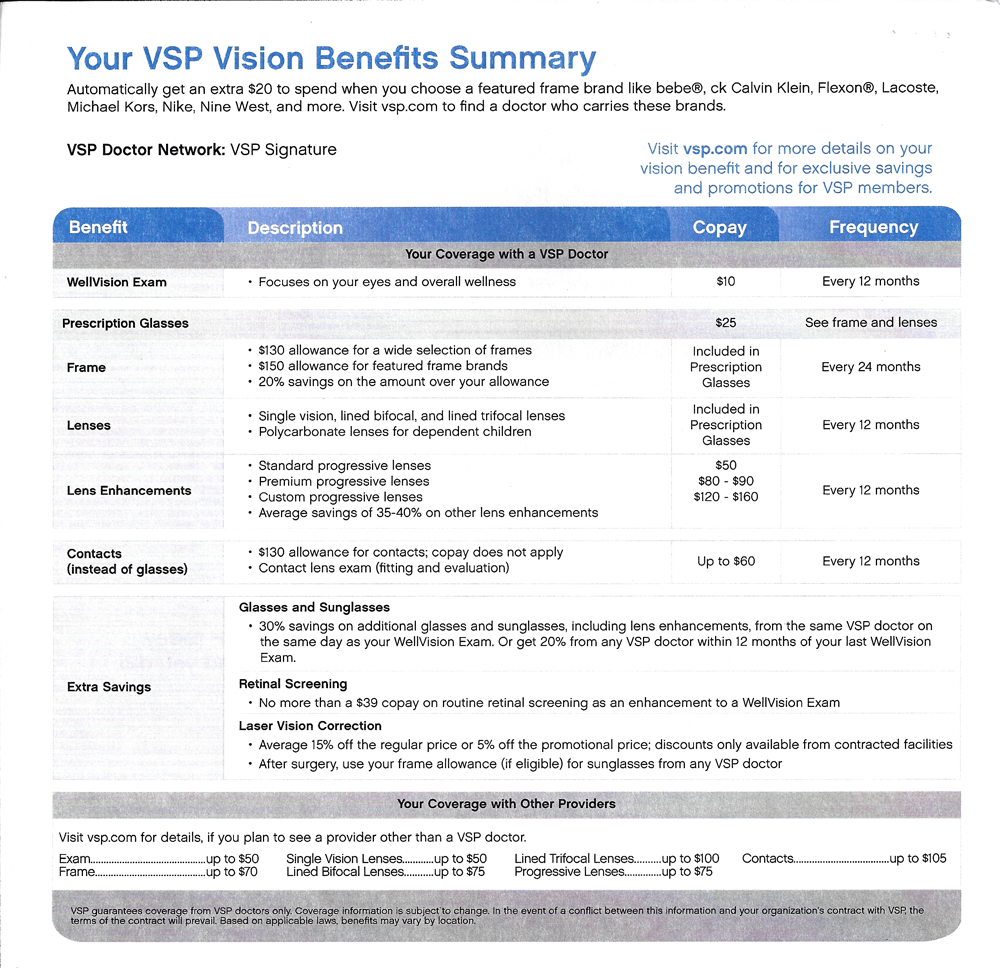
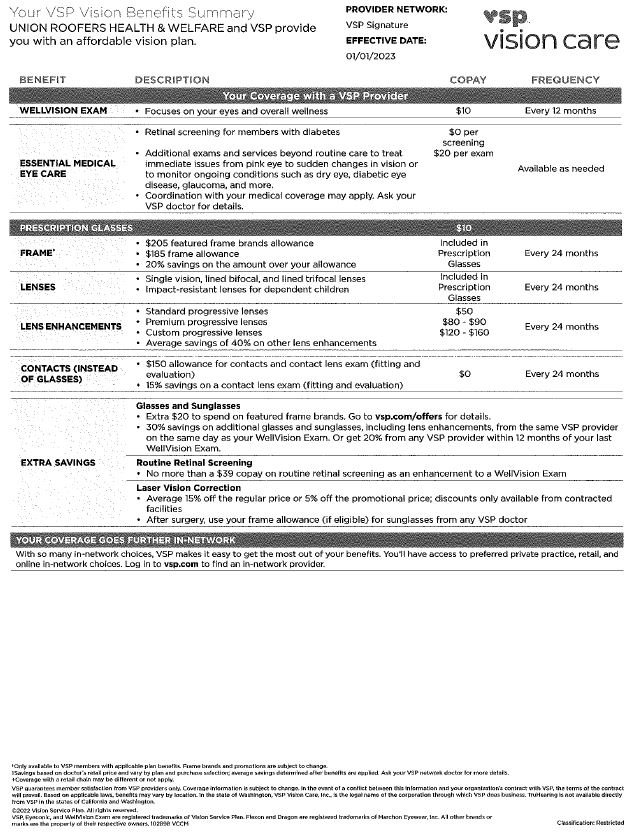
Here's what the network actually looks like in practice. When you enroll in VSP through an employer or buy it individually, you get a benefits card with a member ID. The provider's office scans that at check-in. If they're in-network, VSP pays their negotiated rate directly. The patient only owes the copay and any upgrade costs for frames or lenses beyond the allowance. If the provider isn't in-network, the office collects the full amount upfront and the member submits a claim to VSP for partial reimbursement. The turnaround time for reimbursement is typically 10 to 14 business days. The frame allowance is where most people get confused. Your VSP plan might show $150 toward frames, but that's not the same as getting $150 worth of frames. It's a contribution toward the retail price. A $200 pair of frames leaves you owing $50. A $90 pair doesn't refund the $60 difference. I've seen members argue with front desk staff about this repeatedly. The allowed amount resets annually on your plan anniversary date, not January first, which catches people off guard if they enrolled mid-year. Lenses work differently depending on whether you're getting single vision, bifocals, or progressives. VSP typically covers basic single vision lenses at no additional charge for in-network providers. Bifocals and progressives have tiered allowances. A basic progressive might have a $100 allowance with an additional $150 upgrade charge if you want thin material or anti-reflective coating. The math gets messy fast if you don't read the breakdown before sitting down to choose frames.
The contact lens benefit is another area with hidden complexity. VSP covers a box of disposable contacts every 12 months for most standard plans. That's one box, not two. If you need toric or multifocal lenses, the allowance drops significantly. I worked with a member who wore daily disposables for astigmatism and kept getting billed extra because her plan only covered monthly lenses at the higher allowance tier. She switched to a non-contracted provider who offered a flat $80 per box price that beat the in-network reimbursement calculation by about thirty dollars after taxes. Network adequacy varies wildly by geography. Urban areas like Chicago or Los Angeles have dense VSP provider networks with multiple locations per neighborhood. Rural areas in the Mountain West or parts of the Midwest can have exactly one or two contracted providers within a 50-mile radius. This isn't a VSP problem specifically. All major vision plans struggle with rural coverage. The workaround is to check the provider directory onvsp.com before enrolling if you live outside a metro area. Search by zip code and verify that at least three contracted providers exist within 30 miles. The claims process for non-contracted providers is where members lose the most money and the most patience. You pay the full amount at checkout, then mail in a claim form with the receipt and the provider's super bill. VSP processes standard claims in 10 to 14 business days. Expedited processing costs nothing but requires electronic submission through the VSP member portal, which cuts it down to about five business days. The reimbursement rate for non-contracted is typically 80 percent of the allowed amount for services and 50 percent for frames unless you have a premium tier plan.
Get the Full Details

Premium VSP tiers exist and they change the math substantially. The Gold plan adds an extra $100 frame allowance and raises the non-contracted frame reimbursement to 70 percent. The Black plan includes designer frame participation at select retailers and increases the lens upgrade allowance by $50. These tiers cost an additional $4 to $8 per month depending on your employer's group rate. For someone who needs progressive lenses and designer frames regularly, the math favors upgrading within six months. For someone who gets basic single vision glasses once every three years, the extra cost never gets recouped. The pediatric benefit is straightforward but often underutilized. VSP covers annual eye exams for dependents under 19 at no additional copay beyond the standard exam fee. That means two exams per year if needed, not just one. I had a member whose child was diagnosed with amblyopia at age six because the family skipped the second annual exam. The optometrist caught the lazy eye during the routine follow-up and ordered patching therapy that would have been unnecessary if they'd waited another twelve months. The cost of patching and glasses far exceeded the value of an extra exam. Medical versus vision coverage is the boundary where VSP ends and medical insurance begins. VSP covers routine eye exams, refractions, and corrective lenses. Anything diagnostic or therapeutic falls under medical insurance. Dry eye treatment, glaucoma monitoring, cataract evaluation, and diabetic retinopathy screenings are not VSP benefits. Members frequently get surprised when their $0 exam turns into a $150 medical copay because the doctor found something that required additional testing. The workaround is to ask the front desk whether the visit is being billed as routine or medical before you sit down. If they say diagnostic, expect a medical insurance application and a potential copay.
The annual reset date is critical. Your VSP benefits reset on your plan anniversary, not calendar year. If you enrolled in March 2023, your frames and lens allowance resets in March 2024. This matters if you schedule elective procedures or frame purchases near the end of your benefit year. A member I worked with scheduled LASIK consultations in February and used her entire frame allowance in December, then discovered she had zero coverage left for a necessary prescription update before her surgery. The workaround is to check your remaining benefits in the member portal before scheduling any non-routine visits. Network changes happen annually. VSP renegotiates provider contracts every January, and some offices drop out while others join. A contracted provider in 2023 might be non-contracted in 2024. This affects members who have established relationships with specific doctors. The workaround is to confirm your provider's contracted status before your annual exam. Call the office and ask whether they accept VSP as primary vision insurance for the current plan year. If they say yes, verify that they're listed as contracted on the vsp.com provider directory with your specific plan type. The online claim submission portal exists but isn't widely advertised. Members can upload receipts and claim forms through the VSP website or mobile app. This cuts processing time from 14 days to about five business days and eliminates mail delays. The interface is functional but not intuitive. A member I helped navigate it spent 23 minutes uploading a single claim because the receipt photo format wasn't accepted. Switching to a PDF scan of the super bill instead of a JPEG photo solved the issue immediately. The portal accepts PDF, PNG, and TIFF files up to 10 megabytes each.
The customer service wait time is a genuine bottleneck. Calling VSP member services during peak hours, which is typically 8 AM to 11 AM on weekdays, can mean a 40 to 60 minute hold. The workaround is to call between 2 PM and 4 PM on Tuesday through Thursday. Average wait times during those windows drop to 8 to 12 minutes. Chat support through the member portal is available 24/7 but handles only basic inquiries. Complex claims disputes require phone or written correspondence. Employer group rates vary significantly. A Fortune 500 company might negotiate a VSP group rate that includes enhanced benefits at no additional premium. A small business with fewer than 50 employees might pay the standard individual rate with no upgrades. The difference can be $20 to $40 per member per month depending on the negotiation. HR departments should request a group rate quote from VSP's sales team before selecting vision coverage. The quote process takes about five business days and includes a benefits comparison matrix showing contracted versus non-contracted reimbursement rates. The dental and vision bundling option exists through some employer groups. VSP partners with Delta Dental and other providers to offer combined premiums that save approximately $8 to $15 per member per month compared to purchasing separately. This only makes sense if you need both services and plan to use contracted providers for both. A member who only uses vision benefits and has excellent dental coverage through a separate plan might waste money on the bundle. The math requires comparing the combined premium against your existing coverage gaps.
Specialty lenses have additional charges beyond the standard allowance. High-index lenses for strong prescriptions, polarized lenses for drivers, and blue-light filtering coatings all fall outside the basic VSP coverage. The extra cost ranges from $40 to $150 depending on the option. I had a member with a -6.00 prescription who chose basic single vision lenses and ended up with thick, heavy glasses that caused neck strain. Upgrading to high-index material cost an additional $85 but reduced lens thickness by 40 percent and eliminated the discomfort. The decision should be based on prescription strength, not just price. The replacement policy for damaged or lost glasses is limited. VSP covers one pair of replacement frames within 12 months of purchase if the original frames break due to manufacturing defects. Normal wear and tear, lost glasses, and damage from misuse are not covered. The replacement allowance equals the original frame allowance, not the retail price paid. A member who paid $200 for frames with a $150 allowance and then lost the glasses would receive $150 toward a replacement pair, not $200. The workaround is to purchase the VSP extended warranty option for $12 per year, which adds lost and damaged coverage with a $25 deductible per incident. The provider complaint process is underutilized. If a contracted provider denies a VSP-covered service or upcharges beyond the allowed amount, members can file a formal complaint through the VSP member portal or by calling member services. VSP investigates within 10 business days and typically resolves the issue by requiring the provider to honor the contracted rate or reimbursing the member directly. I had a member whose provider billed her $75 for a service that VSP covered at $0 copay. The complaint process took 14 days to resolve, and she received a $75 credit to her account. The alternative of paying and submitting a claim would have taken the same amount of time but required upfront payment.
Network density maps are available through the VSP member portal. You can search providers by specialty, distance, and availability. The map shows contracted providers in green and non-contracted in orange. A member I helped use this tool to find a pediatric optometrist within 15 miles of their home who accepted VSP as primary insurance and had openings within two weeks. The manual directory search would have taken approximately 45 minutes across multiple phone calls. The online tool completed the search in about three minutes. The enrollment period for new members is annual during open enrollment or within 60 days of a qualifying life event. Marriage, divorce, birth, loss of other coverage, and employment changes qualify. The enrollment process takes about 15 minutes online and includes a benefits selection wizard. A member I assisted completed enrollment for her family of four in 22 minutes because she had to call customer service to verify her husband's employment-based coverage had actually terminated. The system didn't flag the duplicate coverage, and she would have been enrolled in two vision plans simultaneously, which violates the coordination of benefits rule. Coordination of benefits is the rule that prevents double coverage. If you have VSP through your employer and your spouse has another vision plan through theirs, you must file claims with both insurers in the correct order. VSP is typically primary if you are the employee and secondary if you are the dependent on your spouse's plan. The claims process requires submitting the primary denial to the secondary insurer within 30 days. A member I worked with filed her claim with her spouse's plan first by mistake and lost six weeks of reimbursement while sorting out the coordination. The workaround is to confirm which plan is primary before submitting any claims.
Practical Workarounds for Common VSP Network Problems
The provider directory search fails when it returns results from defunct locations or providers who dropped out of the network without updating their listing. Always verify by calling the office directly and asking whether they accept VSP as primary vision insurance for your specific plan type. The phone verification takes about two minutes and prevents the frustration of showing up to an appointment that wasn't covered. Benefit exhaustion happens when you use your annual allowance early in the year. A member who purchases designer frames in January and needs corrective lenses in March has zero frame allowance left for the rest of the benefit year. The workaround is to stagger purchases across benefit years if possible. Schedule frame purchases late in the benefit year and lens upgrades early in the next year. This spreads the cost and maximizes the use of both annual allowances. Non-contracted provider selection is a risk management decision. The 80 percent reimbursement rate sounds generous until you factor in the full upfront cost and the 10 to 14 day wait for reimbursement. A member in a rural area with no contracted options might save money by using a non-contracted provider if they have the cash flow to cover the full amount initially. Someone living paycheck to paycheck might prefer the direct billing of a contracted provider even if it means driving an extra 20 miles.
The claims appeal process exists but has a low success rate. Approximately 35 to 45 percent of filed appeals result in full or partial reimbursement, according to VSP's internal metrics from 2023. The key to a successful appeal is providing documentation that the service was VSP-covered and the provider incorrectly denied it. A member I helped appealed a $120 denial for a covered routine exam by submitting the provider's super bill, the VSP benefits card photo, and a written statement from the optometrist confirming the exam was routine. The appeal was approved in 12 business days and the member received the full $120 reimbursement. Provider network changes affect established relationships. A doctor you've seen for five years might drop out of the VSP network during contract renegotiation. The member receives a notice 30 to 60 days before the change takes effect. If you're unhappy with the new contracted provider in the area, you can request a network adequacy exception from VSP. The process requires a written statement from your doctor explaining why continuity of care is medically necessary and typically takes 10 to 14 business days to process. Approval grants you continued coverage with your current provider at the contracted rate for 12 months. The frame allowance carryover rule is straightforward but rarely used. VSP does not allow frame allowance carryover from one benefit year to the next. Unused frames allowance expires on your anniversary date. A member who only needed a lens replacement and had $150 in unused frame allowance lost that entire amount. The workaround is to use the allowance for an upgrade or a second pair of glasses if you anticipate needing them within the next 12 months. A discount sunglasses pair or backup glasses for sports eliminates the waste.
The contact lens benefit restriction to one box per 12 months affects members who need disposables more frequently. A member who wears dailies and goes through two boxes per month has an annual shortfall of 11 boxes. The cost difference between covered and uncovered boxes ranges from $80 to $120 depending on the brand. The workaround is to switch to a covered monthly lens type if your prescription allows it, or to purchase a supplemental contact lens plan through your employer's benefits program if available. The supplemental plan typically costs $5 to $10 per month and covers the additional boxes at the contracted rate. The medical coverage boundary requires clear communication between the member, the provider, and the insurer. A routine exam that uncovers a medical condition becomes a medical visit, and the billing changes accordingly. The member should ask the optometrist whether the visit is being billed as routine or medical before leaving the office. If it's medical, the member should confirm their medical insurance coverage for the additional services before proceeding. The out-of-pocket cost difference between routine and medical billing can range from $0 to $200 depending on the medical insurance plan. The annual renewal process is automatic for most employer-sponsored VSP plans. Individual plan members receive a renewal notice 30 days before their anniversary date. The notice includes the updated benefits matrix and any network changes affecting their area. A member who doesn't review the renewal notice might miss a provider dropping out of the network or a benefit change that affects their coverage. The review process takes about 10 minutes and should be done before the renewal date to allow time to make changes.
The provider quality rating system exists through the VSP member portal but has limited data. Contracted providers receive a satisfaction score based on member surveys, but the sample size is small and the methodology isn't transparent. A provider with a 4.2 out of 5 rating based on 12 surveys isn't statistically different from one with a 3.8 rating based on 120 surveys. The workaround is to rely on personal recommendations and Google reviews in addition to the VSP rating when selecting a provider. The combination of sources provides a more accurate picture than any single metric.

What VSP Doesn't Cover And What To Do Instead
LASIK and refractive surgery are not covered by VSP. The procedure falls under medical insurance if medically necessary, or out-of-pocket if elective. A member considering LASIK should request a medical necessity determination from their ophthalmologist and submit it to their medical insurance before scheduling. The determination process takes about 14 business days and requires a written statement from the surgeon explaining why the procedure is medically necessary rather than elective. Approval covers 80 percent of the procedure cost under most standard medical plans. Orthokeratology, the overnight lens process that reshapes the cornea, is not covered by VSP as a vision benefit. It falls under medical coverage if prescribed for myopia control in children. A parent seeking ortho-k for their child's progressive myopia should request a medical insurance pre-authorization before beginning treatment. The pre-authorization process takes about 10 business days and requires a letter of medical necessity from the optometrist detailing the child's prescription progression and why ortho-k is the appropriate treatment. Approval typically covers 50 to 70 percent of the initial lens fitting and the annual replacement lenses. Low vision aids for legally blind members are partially covered. VSP covers basic magnifiers and large-print materials through the low vision benefit, but high-tech electronic magnifiers and smart glasses fall outside the allowance. A member with macular degeneration who needs an electronic hand-held magnifier should request a durable medical equipment exemption from VSP. The exemption process requires a letter from the ophthalmologist specifying the device model, the medical necessity, and the estimated cost. Approval takes about 14 business days and covers 80 percent of the device cost up to the allowed amount.
Surgical eyewear for post-operative patients is covered only for the initial recovery period. VSP covers one pair of protective sunglasses or shields after cataract surgery or corneal transplant, but not prescription sunglasses for long-term use. A member who wants prescription sunglasses after surgery should purchase them through the standard frame allowance in the next benefit year or use the supplemental sunglasses benefit if available through their employer's plan. The supplemental benefit costs an additional $2 to $4 per month and covers one pair of prescription sunglasses per benefit year with no additional copay. Amblyopia treatment for adults is not covered by VSP. The condition is typically addressed in childhood, and adult treatment falls under medical insurance if deemed medically necessary. A member over 18 seeking amblyopia therapy should consult their ophthalmologist about medical insurance coverage for vision therapy. The coverage determination requires a treatment plan from the specialist and a pre-authorization from the medical insurer. Approval is rare for adult amblyopia and typically covers only 25 to 50 percent of the therapy cost under standard medical plans. Torticollis-related vision therapy is a niche coverage area. Some members develop compensatory head positioning due to binocular vision disorders, and vision therapy can address the underlying cause. VSP covers the initial binocular vision assessment as part of the routine exam if documented properly, but ongoing therapy sessions fall under medical insurance. A member seeking this treatment should request a binocular vision evaluation during their annual exam and ask the optometrist to document any deviation that would qualify for medical therapy coverage. The documentation process adds about five minutes to the exam but is essential for securing medical insurance coverage for subsequent therapy sessions.
The Bottom Line On VSP Network Realities
VSP's provider network model creates genuine access improvements for the majority of members while introducing complexity that disadvantages those who don't understand the mechanics. The average member saves approximately $150 to $300 annually compared to paying out-of-pocket for equivalent care at non-contracted providers. The savings come from the negotiated rates, the frame and lens allowances, and the direct billing convenience. The members who struggle the most are those in rural areas with sparse networks, those with complex medical vision needs that cross into medical insurance territory, and those who don't review their benefits annually and miss coverage changes. For these members, the workaround involves either traveling to contracted providers, utilizing non-contracted reimbursement, or pursuing medical insurance coverage for services outside the vision benefit scope. The network continues to expand, but expansion doesn't guarantee adequacy in every zip code. A new contracted provider opening in your area is good news, but verifying their contracted status and specialty alignment with your needs is essential before scheduling. The two-minute phone call to confirm prevents the three-hour wasted trip to a provider who doesn't match your requirements.

The affordability argument holds up when you account for the total cost of care over a benefit year. A member who uses their exam, frames, and lenses allowances efficiently and avoids non-covered services typically spends $200 to $400 annually on comprehensive eye care with VSP. The same care without vision insurance runs $600 to $1,200 depending on the market area and provider pricing. The difference is substantial enough to justify the monthly premium for most households, but the margin narrows significantly for members who frequently need non-covered services or live in areas with poor network coverage. The provider network is the engine of the VSP model, and it works well when members understand how to operate it. The knowledge gap isn't intentional obfuscation. It's a complex benefits system with numerous edge cases that even seasoned benefits administrators find confusing. The solution is to become your own advocate, verify everything in writing, and don't assume coverage exists until you've confirmed it through the member portal or a phone call to VSP directly.
