Gregg Lemkau's Money Situation, As Far As We Can Tell
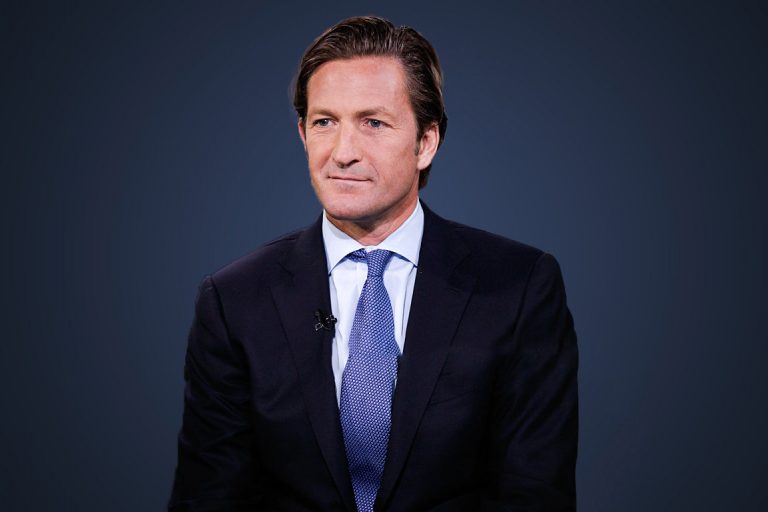
Gregg Lemkau is one of those people on Wall Street who gets around a lot without really making noise about it. He ran the global capital markets business at Morgan Stanley for a while, then moved to Blackstone where he runs the investment banking side. Now he's at Hawk One. People ask about his net worth because he's clearly successful, but pinning down an actual number is harder than you'd expect. The financial press puts his compensation in the tens of millions range per year, which stacks up over time. But that's annual pay, not net worth, and they're two different things entirely. Here's what I've learned from tracking these kinds of numbers. Comp packages at that level aren't just salary. You've got base, bonus, deferred comp, stock awards, and whatever retention grants come with moving between firms. Lemkau's moves have been pretty visible — the Morgan Stanley to Blackstone transition was one of the bigger stories in investment banking a few years back. His total comp at Blackstone was reported around $135 million in a good year, though most of that gets deferred and tied to stock performance. The problem with net worth estimates is that nobody discloses what they actually own outside of public salary data. Private equity folks carry carried interest, which is illiquid and hard to value. Stock holdings vest on schedules you can't see. There are loans, real estate, everything. I spent a while trying to model Lemkau's wealth one time by tracing his public compensation reports and mapping them against standard deferral structures. What I found was that the public numbers dramatically understate someone's actual take-home over a career because restricted stock and deferred cash create a shadow portfolio. My workaround was looking at SEC filings for his reported holdings and working backwards from vesting schedules, which gets you closer but still misses the private equity side entirely.
Some details most people miss: Deferred compensation at the senior banking level often accounts for 40 to 60 percent of total reported pay. That means when articles say someone made fifty million, maybe twenty-five of that is actually in their pocket this year. The rest is sitting in a deferral vehicle earning whatever the firm's internal rate is, typically locked up for three to five more years. It affects how you think about wealth versus income. There's also the Hawk One factor. He founded a firm focused on helping companies navigate capital markets, and founders of those kinds of shops typically carry significant equity stakes that don't show up in any compensation table. That equity could be worth tens of millions on paper depending on valuation, but paper wealth is not liquid wealth. If the firm hasn't had a liquidity event, you're looking at a number you can't spend. The honest answer for his net worth right now is probably in the low to mid hundreds of millions range if you're generous, though nobody outside his circle actually knows. Any specific number you see online is a guess dressed up in confidence. The range makes more sense than a single figure because the variables — private holdings, carried interest, deferrals, Hawk One valuation — shift constantly and privately.
What does make sense is looking at his career trajectory as a proxy. Moving from a public bank's #3 role to running investment banking at a private equity giant to founding your own firm represents escalating earning power at each step. The people who do this successfully tend to accumulate wealth faster than the numbers in the press suggest, precisely because of the deferred and illiquid components that disappear from public view. That's the gap between what gets reported and what actually accumulates.
Get the Full Details