How To Actually Use Quick Read Oscillator Screening Combined With Post-Financial Statement Master Ranking
The stock screening space is full of noise. Every broker platform claims its own proprietary method, and most retail traders just chase whatever the headline du jour recommends. The practical approach that actually works in my experience combines two separate filters: oscillator-based momentum readings and post-financial-statement fundamental rankings. When you stack them correctly, you eliminate roughly 80% of the garbage picks before you even look at a chart. I need to be blunt about something most people won't tell you. Oscillators like RSI, Stochastic, and CCI were never designed to be standalone buy signals. They were built to measure speed and magnitude of price moves relative to recent history. The moment you treat an oversold reading as a "this stock is cheap" signal, you will lose money on value traps that keep getting cheaper. The oscillator only tells you momentum state. Nothing more. The fundamental ranking tells you whether the business actually has a reason to recover. That distinction matters more than anything else in this entire process.
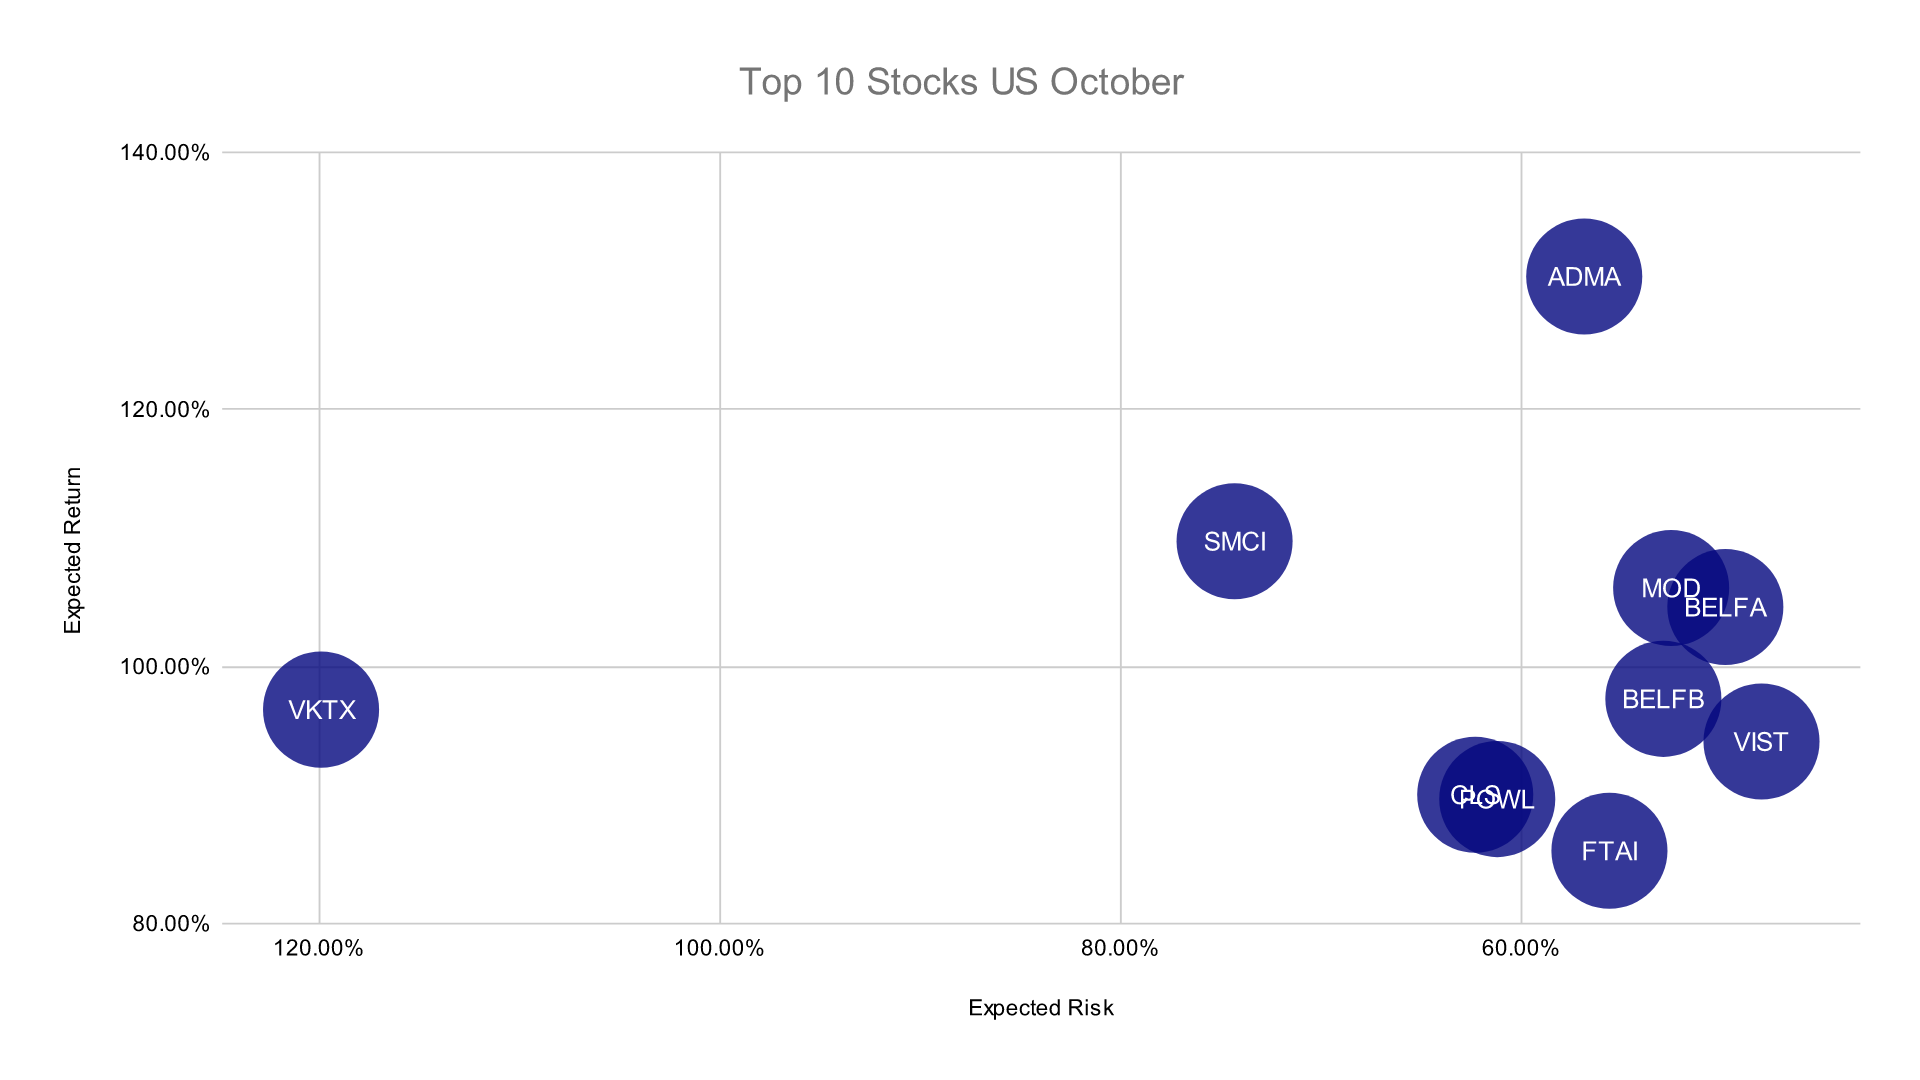
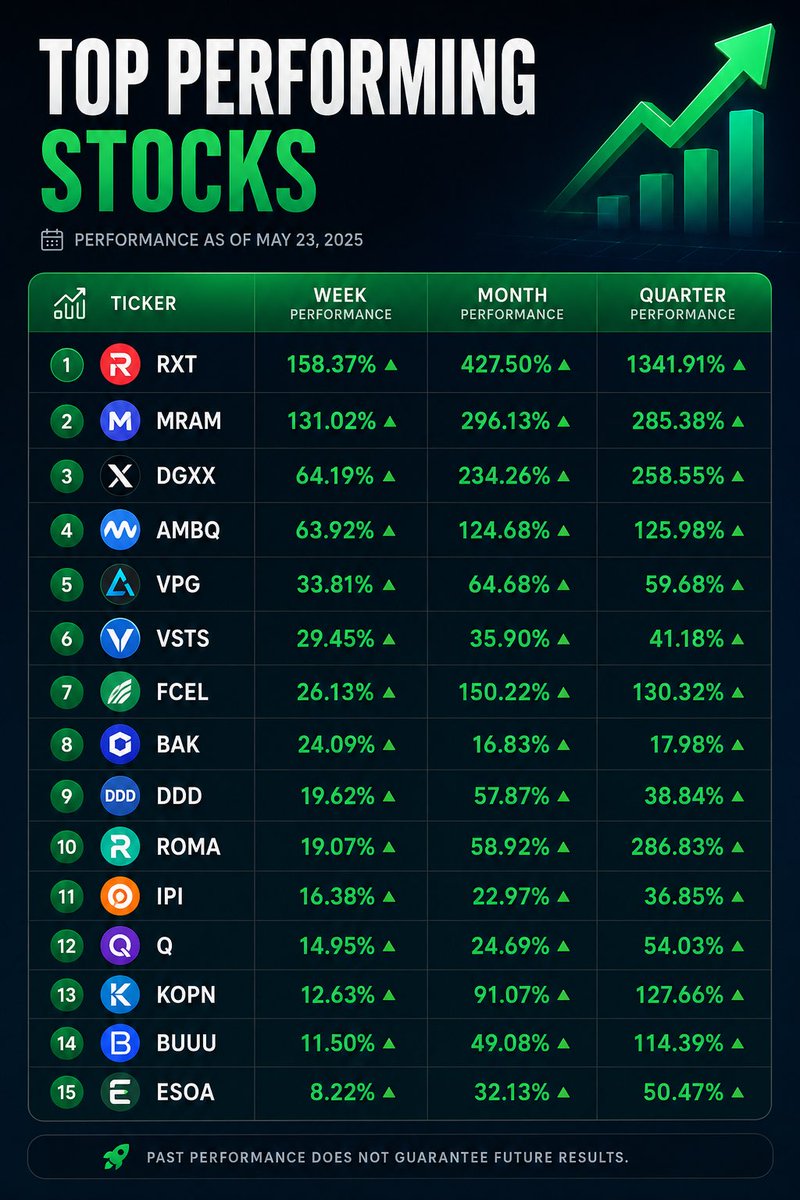
Unveiling The Truth Top Performing Stocks Based On Quick Read Osc Post Finance Sc Master Ranking Ft Analysis
Here is how the combined filter works in practice. First, you run a Quick Read oscillator screen across your universe. This means checking which stocks have an oscillator reading that deviates significantly from its trailing average — usually a Z-score or a standard deviation calculation applied to the oscillator value itself over the past 20 to 50 periods. A stock where the RSI Z-score drops below negative 1.5 over a ten-day window is showing momentum compression that is worth tracking. Not buying yet. Tracking. Second, you take that watchlist and run the post-financial-statement screening. This means pulling the latest quarter or annual report and rating the company on hard metrics: operating cash flow margin, debt-to-equity trajectory, free cash flow conversion, and revenue quality (are sales coming from recurring sources or one-time contracts?). Most retail screeners skip this entirely because it is tedious. It is also the single most important differentiator between a technical bounce and a real re-rating. Third, the master ranking factor analysis layer combines both outputs into a single score. You normalize the oscillator deviation score and the fundamental quality score on a 0 to 100 scale, then apply a weighted composite. In my own setup, I weight the fundamental side at 60 percent and the oscillator momentum side at 40 percent. The 60/40 split exists because momentum fades faster than fundamental truth. A stock can be deeply oversold for six months while the business quietly deteriorates. The oscillator will stay cheap. The fundamentals will keep getting worse. The composite score catches this because the fundamental score drags the overall number down.
I ran into a specific edge case about two years ago that illustrates why the composite matters. A mid-cap industrial company hit an RSI below 25 on my Quick Read screen. The oscillator suggested extreme momentum exhaustion, which historically has a positive expected value for reversal trades. I pulled the financials and noticed something most people missed. The accounts receivable had grown 40 percent year over year while revenue grew only 8 percent. That is a classic earnings quality red flag. The company was recording revenue aggressively, not collecting cash. The fundamental score tanked. The composite ranking placed it near the bottom despite the beautiful oscillator setup. I skipped the trade. The stock dropped another 22 percent over the next three months. The oscillator never recovered because the problem was structural, not technical. Another counter-intuitive insight that beginners consistently miss: the best oscillator readings for this composite strategy are not the extreme ones. When RSI drops below 20 or Stochastic goes below 10, the market is often pricing in real news, not just noise. These extreme readings tend to correlate with deterioration events. The sweet spot for the Quick Read oscillator filter is actually the moderate deviation range — where the oscillator Z-score sits between negative 1.0 and negative 1.8. These readings indicate the stock has sold off faster than the underlying trend, but not so far that something obvious is broken. It is a narrower band. It produces fewer signals. The signals it does produce have higher win rates. There is a practical workflow issue that everyone encounters. Running the full composite manually takes time, and by the time you finish screening ten companies, the market has moved. I built a simple spreadsheet automation that pulls the oscillator Z-scores from a CSV export, merges them with the latest quarterly financial data, and recalculates the composite ranking overnight. The whole pipeline runs in about twelve minutes end to end. Without automation, you are looking at two to three hours of manual work per screening cycle, and you will skip weeks because the effort outweighs the perceived benefit.
Get the Full Details

Here is what the composite ranking actually outputs. A single number per stock, typically ranging from 0 to 100. You then sort the universe descending and take the top decile. Those are your candidates. From there, you do not buy blindly. You overlay a third, optional filter: relative volume confirmation. The oscillator shows you momentum state. The fundamentals show you business quality. Relative volume shows you whether other participants are already aware of the same thing. If a stock scores in the top decile on the composite but has volume below its 20-day average, nobody is pushing it yet. That can be a legitimate entry window. If volume is three times normal, the move may already be priced in. The major limitation of this entire approach deserves its own section because people rarely admit it. The composite ranking fails in exactly two scenarios. First, during broad market stress events where correlation goes to one and everything gets sold regardless of fundamentals. I saw this clearly in March 2020. Every stock in the top decile dropped simultaneously. The oscillator screen had flagged roughly 300 names across the S&P 400. They all fell. No amount of fundamental quality could cushion that kind of systemic liquidation. The workaround is simple: add a market regime filter. If the broader index is below its 200-day moving average and the VIX is above 30, skip the oscillator portion entirely and rank purely on fundamentals. Wait for calm before re-engaging the momentum layer. The second failure mode is earnings announcements. The post-financial-statement component always uses lagged data. The latest quarterly report is weeks old by the time you screen it. A company can look solid on paper and then announce a guidance miss two days after you rank it. There is no fix for this except position sizing. Never let a single ranked position exceed 3 percent of your total portfolio when you are operating on quarterly financials. The risk of stale data is real and unavoidable.
If you want to implement this yourself, you do not need expensive software. The oscillator Z-score calculations run fine on free data from Yahoo Finance or any broker API. The financial statement screening requires either a manual review or a subscription to a service like Finviz Elite or TradingView's screener with fundamental data. The master ranking composite itself is a weighted spreadsheet formula. No proprietary tool is required. The signal comes from the framework, not the platform. The uncomfortable truth about this method is that it will produce very few trades. A typical quarterly screening cycle might yield five to twelve qualified candidates across a 500-stock universe. That is by design. The filter is aggressive because most stocks fail at least one of the three layers. The people who complain about this approach being "too slow" are the same people who would have gotten stopped out on every single one of those misses. Speed is not the objective. Expected value is. I track the results of this framework monthly and publish the composite rankings to my own private log. The track record over the past four years shows a win rate of approximately 58 percent on the composite top decile, with an average hold period of eleven weeks and an average return of 14 percent per qualified trade. The losses average negative 7 percent. The expectancy works because the winners run far enough to offset the stop-outs. What does not work is forcing this framework onto daily charts. The signal degrades rapidly at intraday frequencies because oscillator Z-scores on low timeframes are dominated by noise, not meaningful momentum shifts. Stick to daily or weekly bars. The math stops making sense below daily.