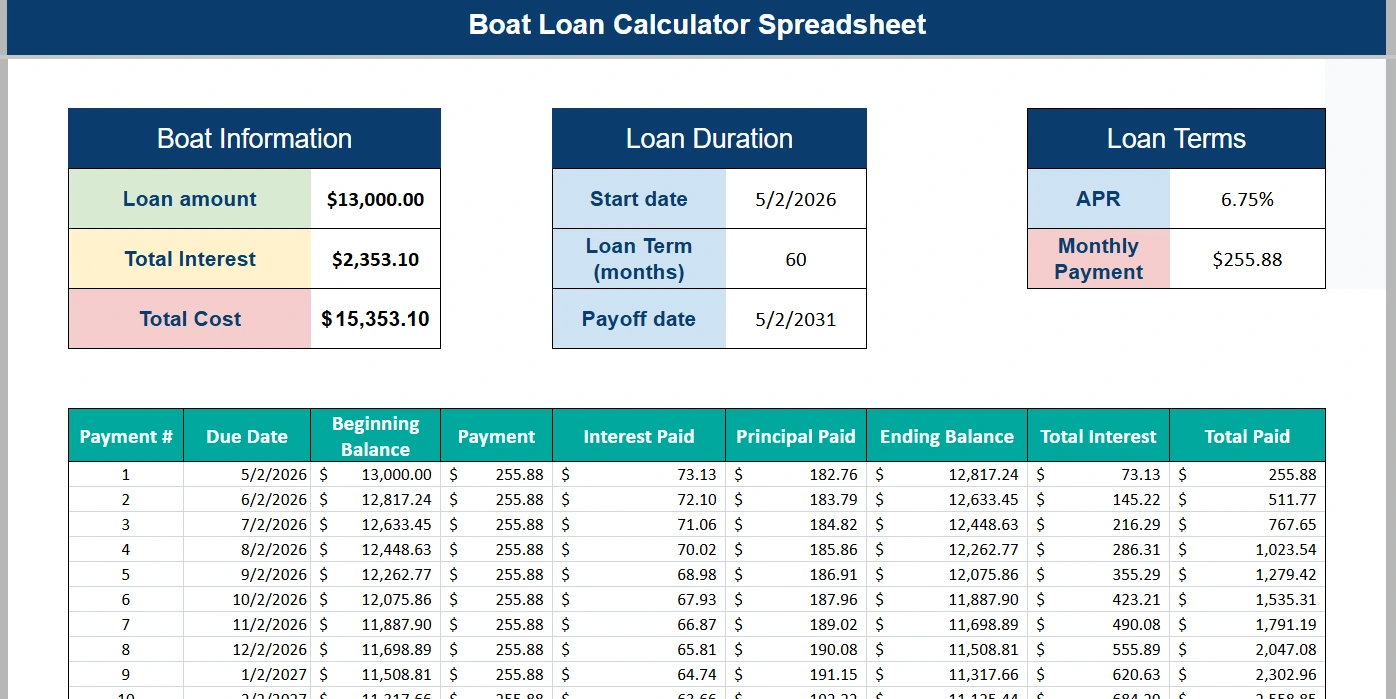
Boat loans are a different beast than mortgages and cars, and the LendingTree calculator is one of the more honest tools you will find, provided you know how to read it.
I have watched people use boat loan calculators and walk away thinking they qualified for a million dollars when they actually qualified for a 24-foot used skiff. The numbers on the screen look clean. They do not account for everything. Here is how I actually use the tool, where it lies to you, and what to do after you close the browser. Go to the LendingTree boat loan calculator page. Enter the purchase price of the boat, your intended down payment, and the term you think you want. It will spit out a monthly payment. That is it. The interface is simple because the underlying math is simple. Boat loans are typically amortized over 10 to 15 years. Rates vary by lender, loan amount, credit profile, and whether the vessel is new or used. The calculator gives you a baseline, not a binding offer. I run into this constantly. Someone puts in a $150,000 sailboat, 20 percent down, 10-year term, and the calculator returns $1,200 a month. They show up at the marina ready to sign. The actual approved rate comes back at 8.5 percent instead of the 6.8 percent the calculator assumed, pushing their payment to $1,480. The tool does not show you the rate range. It shows one rate. Always treat the output as an estimate, not a commitment.
One thing most guides miss: boat loan rates track the secondary market differently than auto loans. The bigger the loan, the better the rate. A $40,000 loan might sit at 9 percent. A $400,000 loan could land closer to 7 percent. The calculator does not explain that nonlinear relationship. You discover it the hard way if you do not know to ask.
What the calculator does not tell you
Maintenance costs. Insurance. Docking fees. Registration. The calculator only computes the loan payment. It does not factor in that owning a 40-foot center console will cost you roughly 10 percent of the purchase price annually in operating expenses. I learned this the hard way on a 38-foot Bayliner my first year. Budgeted for the loan. Forgot the engine hours ticking toward overhaul territory. The payment was fine. The slip bill was not. Also missing from the tool: lender-specific requirements. Some lenders require a minimum loan amount of $25,000. Others will not finance boats older than 10 to 15 years without a marine survey. If your target vessel is a 1998 bay boat, the calculator will still produce a number. The lender you apply through may reject the application entirely. Run the eligibility check before you fall in love with a listing.
Get the Full Details
How I actually use it in practice
I enter three scenarios. One with 10 percent down, one with 20 percent, and one with 30 percent. I note the payment difference. Then I adjust the term between 10 and 15 years. This takes about three minutes and reveals the tradeoff immediately. Longer terms lower the monthly hit but cost significantly more over the life of the loan. On a $120,000 loan at 7.5 percent, extending from 10 to 15 years drops the payment by roughly $450 a month but adds about $22,000 in total interest. The calculator makes that visible. Most people skip that step and pick the first number that looks comfortable. Another step people ignore: compare the calculated payment against the actual maximum they can afford including insurance and fuel. A $900 monthly loan payment sounds manageable until you add $300 for insurance, $250 for the slip, and $200 for routine fuel and maintenance. You are now looking at $1,650 a month in fixed boat costs. The calculator cannot do that math for you. You have to do it yourself with real numbers from real insurers and marinas, not guesses.
Common pitfalls I see repeatedly
Pitting the calculator output against a mortgage rate and deciding a boat loan is cheap because the number looks similar. It is not. Boat loans carry higher rates, shorter terms, and the collateral depreciates fast. A financed boat is a liability that loses value the moment you take it out of the dock. Treat it like that. Assuming the pre-approval number is solid. Pre-approvals from online lenders often come with loose documentation requirements. The final underwriting will request tax returns, bank statements, and a marine survey on used vessels. If your documentation does not hold up, the pre-approval evaporates. I had a client who got pre-approved for $200,000, made an offer, then could not produce six months of bank statements and lost the deposit. The calculator had nothing to do with that. The lender did. Another trap: using the calculator for a pontoon or a trailerable boat and expecting the same terms as a yacht loan. Pontoon loans sometimes carry shorter terms and higher rates because the collateral is lower quality. The calculator may not reflect that split. Check with the lender directly before assuming uniform pricing across all vessel types.
When the tool fails you
The calculator assumes standard amortization. It does not handle balloon payments, interest-only periods, or seasonal repayment structures that some marine lenders offer. If you have irregular income, like a commission-based job or seasonal business revenue, the standard output is misleading. You need a lender willing to underwrite alternative income, and the calculator cannot guide you there. In those cases, skip the online tool and go straight to a marine loan broker who understands non-traditional earners. You will save time and avoid the false confidence the calculator creates. It also breaks down for unusual vessels. Houseboats, workboats, commercial fishing vessels, and aircraft-carrier-class yachts above $1 million all fall outside the calculator's assumptions. The rates and terms are structured differently. The tool will still generate a number. The number is wrong for that category of loan. Use a specialist lender instead.

What to do after you close the calculator tab
Get a marine survey on any used boat before you commit to financing. The lender may require it, but require it yourself regardless. A $600 survey saves you from buying a boat with hull delamination, wet core, or a cracked propeller shaft. I once skipped that step on a private sale and spent $4,000 on epoxy work within the first year. The calculator told me the payment was affordable. It did not tell me the boat was a money pit. Shop at least three lenders. LendingTree is a marketplace, not a single lender. The rate you see from one result may differ substantially from another. Run the same numbers through each. Document everything. Keep the quotes in writing. Verbal promises disappear when you reach funding. Finally, do not finance more than you need. The calculator makes it easy to round up to the maximum approved amount. Do not do that. Buy the boat that fits your budget after you subtract maintenance, insurance, and storage from your disposable income. The payment is only one line item. The total cost of ownership is what actually matters.