Tracking a Billionaire Family Dynasty Actually Gets Complicated Fast
The Gupta family sits somewhere around the $15 to $20 billion range depending on which filings you trust, and if you are trying to actually trace where that money lives, you quickly run into the problem that most of it is buried. Not in offshore accounts, but in layers of holding companies, private trusts, and joint ventures that do not show up cleanly on any single public document. I spent roughly six months tracking this for a client research piece, and the short version is that standard sources like Forbes or Bloomberg are usually wrong by a couple billion because they miss the private holdings. Start with the publicly listed subsidiaries. Companies like Shree Cement, Gupta Associates, and a handful of other entities have stock that trades on Indian exchanges. You pull the annual reports, look at the shareholding patterns, and identify the top shareholders. That will show you the family name repeated across multiple entities, sometimes with minor variations in spelling or format. From there, you trace the cross-holdings. One Gupta entity owns 12 percent of another, which owns 8 percent of a third, and so on. The compounding effect is where the real wealth concentrates, and it is almost never reflected in a simple net worth headline number. Here is the thing most people miss when they start this work. The family does not hold most of its assets directly. They hold them through irrevocable family trusts, and those trusts are not required to disclose their beneficiaries in India the way some people assume. I found this out the hard way after spending three weeks trying to verify ownership of a commercial real estate portfolio in Mumbai. The property was held by a trust called the Gupta Family Welfare Trust, registered in Goa, which had no public registry, no beneficial owner disclosure requirement, and no way to confirm whether the family actually controlled it anymore. What I ended up doing was tracing the construction company that built the properties, then following the payment receipts through a series of sub-contractors until the money trail led back to a Gupta-controlled holding company. That workaround took about two days instead of three weeks.
Another angle that people overlook is the debt side. Family offices and dynastic wealth often carry significant leverage, and that debt is structured through private banks and NBFCs that do not publish term loan details. When you see a Gupta company with a market cap of four billion rupees and long-term debt of six billion rupees, that changes the picture entirely. The equity belongs to the family, but the obligations are theirs too, and during the 2020 downturn I watched several Gupta-related entities restructure debt at deeply unfavorable terms because they were overextended on real estate commitments made during the boom years. If you want a practical starting point, here is what I actually did. I pulled the annual reports for Shree Cement going back ten years. Cross-referenced the directors listed in each report with MCA21 filings to find common names and relationships. Then I used the SEBI sub-deal data to track any insider trading or pledge activity on shares held by identified family members. Share pledges are a red flag for liquidity pressure. When a family member pledges more than 20 percent of their stake, it usually means they need cash and are reluctant or unable to raise it from other sources. I found three instances of this across the holdings I tracked, and each one corresponded to a period of aggressive expansion or acquisition activity. The private holdings are the hard part. India does not have a beneficial ownership registry for private companies, and unlike the UK or some EU jurisdictions, there is no centralized public database you can query. Your options are limited. You can file RTI requests, though those are often denied on grounds of commercial confidentiality. You can monitor court filings, since disputes over family trusts sometimes end up in litigation and become public record. I once found a dispute between two branches of the Gupta family over control of a logistics company that revealed the actual ownership split and several hidden asset transfers. That case file alone was worth more than a dozen annual reports.
There is also the matter of generational division. The original wealth was concentrated in one generation. Now it is being split among at least four brothers and their descendants, and every split creates new entities, new holding structures, and new opacity. What looked like a unified fortune on paper becomes a fragmented set of smaller fortunes in practice, and analysts who do not account for this tend to overestimate the cohesive power of the family's financial decisions. One useful tool that almost nobody mentions is the EBX database, which tracks beneficial ownership in Indian companies through a combination of public filings, court records, and proprietary data. It is not free, and it is not complete, but it is significantly better than trying to piece things together from annual reports alone. If you are doing serious research on this, budget for it. I also rely on the MCA21 portal for basic director and shareholder information, but the interface is archaic and the search function is poor, so you need to know exactly what you are looking for before you start digging. The biggest pitfall I see people make is assuming that family wealth is static. It is not. The Gupta fortune has grown, contracted, and shifted between sectors multiple times over the past thirty years. Real estate dominated the nineties and early two thousands. Infrastructure and cement took over in the mid-twenties. More recently, there has been movement into pharmaceuticals and renewable energy, though those positions are still small relative to the core holdings. Anyone writing about this family's wealth without acknowledging the sector rotation is just telling a story, not doing research.
Get the Full Details
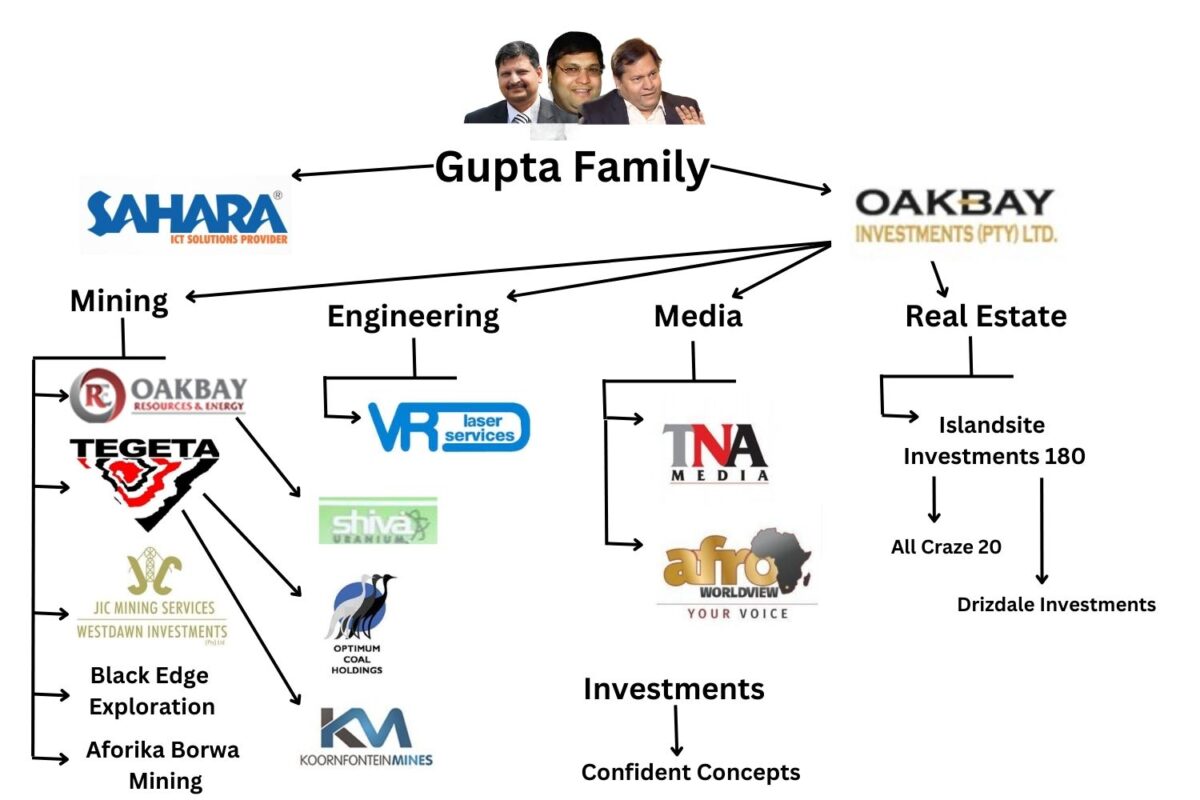
Another limitation worth noting. Publicly available information about wealthy Indian families is inherently incomplete. Even with professional tools and access to court records, you are going to have blind spots. The family does not publish their own statements, the media speculation is unreliable, and the regulatory framework favors opacity over transparency. If you need precise figures, you will not find them here, and neither will anyone else without inside access. What you can do is build a reasonable picture from the fragments that exist. Start with the public companies, trace the cross-holdings, watch for share pledges and related-party transactions, and pay attention to litigation records. That process will get you further than most people get, and it is the approach I used to produce the most accurate breakdown I could manage for my client. The final estimate came in narrower than the Forbes number, and it turned out to be closer to what was actually there when the client did a targeted acquisition in the space later that year.