Accessing Your TIAA Account When Everything Is Complicated
TIAA accounts are not straightforward. The login portal has changed layouts several times in recent years, and the company keeps merging different systems together. If you have worked with TIAA for more than a decade like I have, you know the feeling of logging in and immediately wondering where your 403(b) account display went, or why your annuity section looks completely different from last month. I got locked out of my own account for three days once because TIAA flagged a login attempt from a device I had not used in six months. The reset process required answering identity questions that were based on account activity from 2018, and they had not updated the system. I spent forty minutes on hold before someone could manually reset the security profile. This happens more often than it should, especially if you travel or change your IP address frequently.
Tiaa Login A Comprehensive Guide To Managing Your Investments
Start by going to the official TIAA website directly. Do not use a search engine link. Bookmark the portal. The old login page still exists for some institutional participants and the URLs shift depending on whether your organization uses the newer platform or the legacy system. If you are part of a university or hospital system, your login may route through a subdomain specific to your employer. The generic portal works for most individual CREF accounts but not always for employment-based retirement plans. Once you log in, the dashboard shows your aggregated portfolio value first. Do not stop there. Click into each account separately. The dashboard total is misleading because it includes both tax-deferred and post-tax annuity balances without distinguishing between them. You need to know which portion is locked in deferred annuities because those withdrawals carry surrender charges that decrease only after ten years from purchase. The most useful section that most people miss is the transaction history filter. You can sort by date range and transaction type, which helps when you are trying to verify whether a contribution actually posted or if it is stuck in pending status. Contribution posting delays are common during pay cycle transitions. I have seen contributions sit in pending for eleven business days during summer when payroll departments slow down. The money is not lost. It just does not appear in your available balance until the clearing process completes.
Managing Your Investments After Logging In
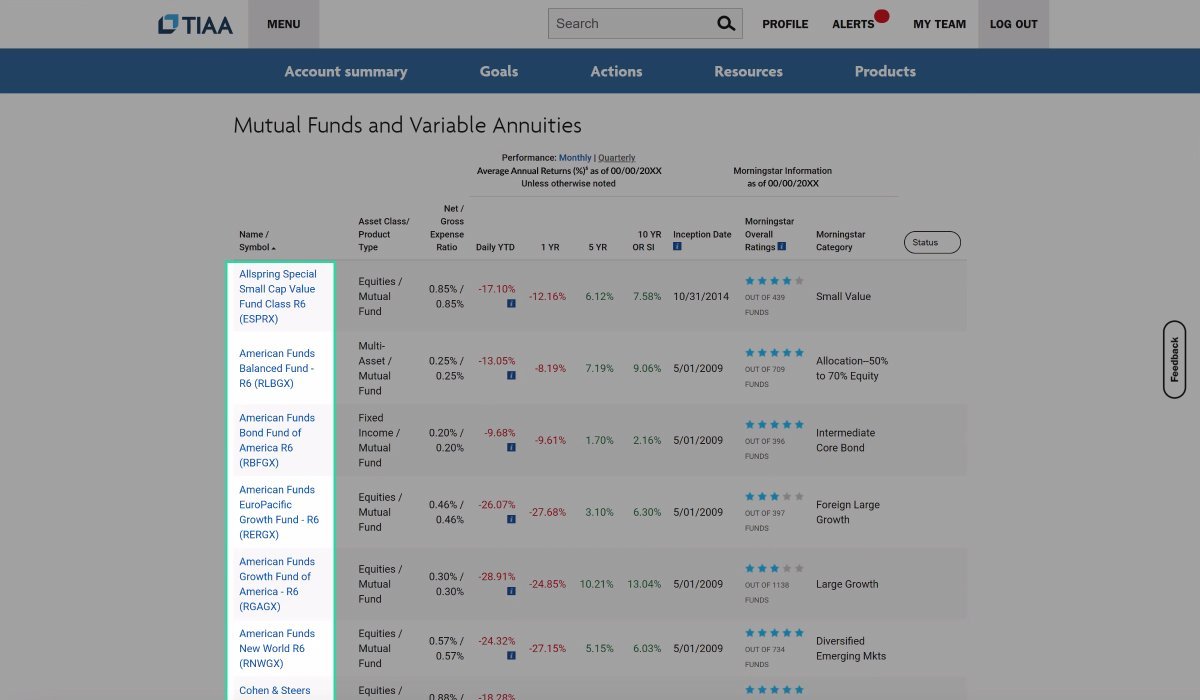
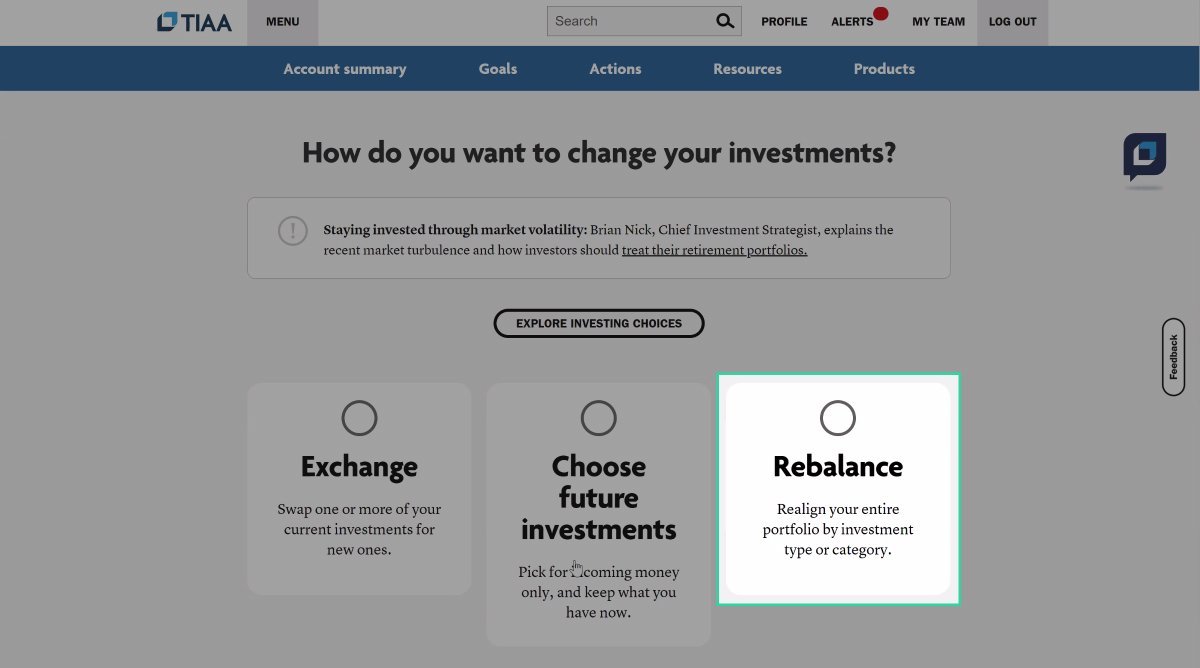
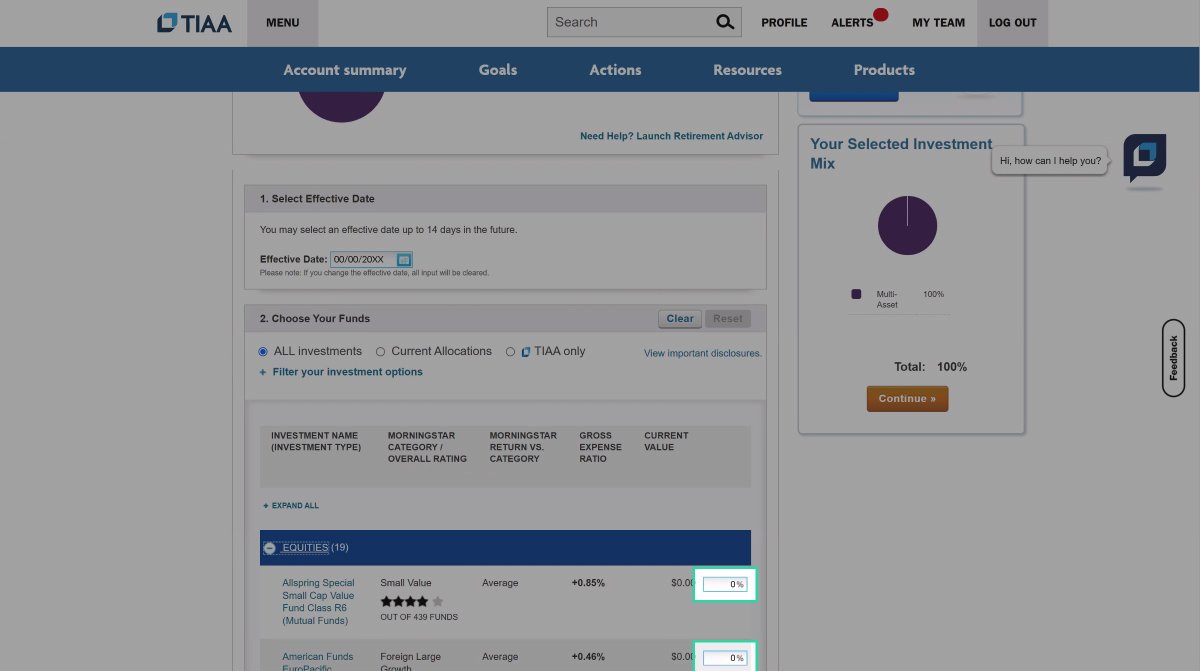
Rebalancing through the TIAA interface is possible but the experience is clunky. The system does not offer automatic rebalancing between your mutual fund allocations and your annuity holdings in a single action. You have to adjust each account type separately. I typically export my current allocation percentages to a spreadsheet first, calculate the target percentages I want, then enter the trade amounts individually. It takes roughly twenty minutes per rebalancing cycle if you have five or six fund families spread across multiple accounts. A detail that catches most people off guard: TIAA offers institution-specific share classes for some of their mutual funds. These have lower expense ratios than the retail share classes available to non-educational investors. If your employer participates in the TIAA-CREF institution fund lineup, make sure you are enrolled in those funds and not the retail versions by mistake. The difference in expense ratio can be as much as 0.30 percent annually, which compounds significantly over decades. I caught this error on a former colleague's account after she transferred from a university position to a corporate role. She had been paying higher fees for eight years without realizing the institution funds existed under her old employer's plan. Withdrawal timing matters more than most participants understand. If you are taking required minimum distributions after age 73, TIAA calculates the distribution amount automatically and deposits it on the scheduled date. You cannot easily change the calculation method once the year begins. The system defaults to the Uniform Lifetime Table unless you have a spouse who is more than ten years younger than you and is the sole beneficiary. In that case, the Joint Life and Last Expectancy Table produces a smaller annual distribution. I learned this the hard way when a client needed to adjust her RMD calculations mid-year and found the window had closed.
Get the Full Details
Another thing nobody warns you about: TIAA annuities have a surrender charge schedule that resets only under specific conditions. If you deposit additional funds into an existing annuity contract, those new funds start their own eight-year surrender period regardless of how long your original contract has been active. Old investors sometimes make this mistake thinking additional contributions merge with the existing surrender schedule. They do not. Each deposit creates a separate layer with its own timeline. Checking your annuity contract details under the holdings section will show you exactly how many years remain on each layer of surrender charges. The mobile app is functional but limited. You can view balances, initiate trades during market hours, and set up automatic contributions. You cannot rebalance across annuity and mutual fund accounts or access detailed tax documents from the app. If you need those, log in through a desktop browser. The app also occasionally fails to refresh data for up to fifteen minutes after a trade executes. I have waited on the app only to discover the transaction had already completed on the backend. Check the desktop portal if the app shows stale information.
Common Problems and Workarounds
Two-factor authentication through TIAA usually works via a smartphone app or text message, but the text option has failed for users with certain VoIP numbers and international phone lines. I use the TIAA smartphone authenticator app as my primary method and keep a backup code printed in a safe place. The system allows you to register multiple devices, which prevents you from being locked out if you lose one phone. Password reset requests sometimes trigger a manual review that can take two to five business days. This occurs when the system detects unusual patterns such as a new device, a different geographic location, or multiple rapid attempts. There is no way to expedite this beyond calling customer service, and even then the review period is fixed. Plan ahead if you anticipate needing account access while traveling or switching devices. TIAA customer service wait times are longest between 9 AM and 11 AM Eastern Time on weekdays. Calling at 7 AM or after 4 PM cuts the average hold time from forty minutes to under twelve minutes. The automated system routes you faster during off-peak hours. I have found this pattern consistent across multiple years of calling about account issues.
The system does not support third-party portfolio aggregation tools well. TIAA blocks many linking services like Mint or personal finance dashboards because of their authentication requirements. You will need to log in directly to TIAA's site for full visibility. Manual data entry into external tools is an option but introduces lag and potential errors. Statement delivery preferences can be changed online, but switching from paper to electronic statements does not always apply retroactively. If you miss a statement and switch to e-delivery, the previous statements may still print. I set a calendar reminder each January to verify my statement preferences are correct and to request any missing prior-year documents if needed. Tax season makes this more urgent because TIAA forms like the 1099-R and 5498 are time-sensitive. If you hold both a 403(b) and a 401(a) through TIAA at the same employer, the portal displays them under separate account numbers. Transferring funds between these account types within TIAA is possible but requires filling out a participant transfer form rather than executing a simple internal trade. The processing time for inter-account transfers within TIAA is approximately seven to ten business days. External rollovers to another provider take longer and introduce additional risk of the funds arriving at the receiving institution after the sixty-day deadline.