How the Polish PIT Scale Actually Works (And What Is Changing for 2025)
Most people in Poland don't understand how their monthly tax withholding relates to their annual tax return. They see a number on their payslip, trust that the employer calculated it correctly, and file the annual PIT form in April without really knowing if they owe money or are due a refund. That disconnect exists because the system is more mechanical than intuitive, and recent legislative noise around Tabela Pis 2025 The Future Of Personal Income Tax Reduction In Poland has only made it more confusing for everyone trying to plan ahead. The Polish personal income tax system (PIT) is a progressive two-bracket model. You earn income, pay social security contributions upfront, and then the tax authority recalculates everything at year-end based on your total annual earnings. The monthly withholdings are estimates. The annual filing is the real calculation. That is the fundamental mechanic everyone needs to grasp before worrying about any specific 2025 changes.
Unveiling Tabela Pis 2025 The Future Of Personal Income Tax Reduction In Poland
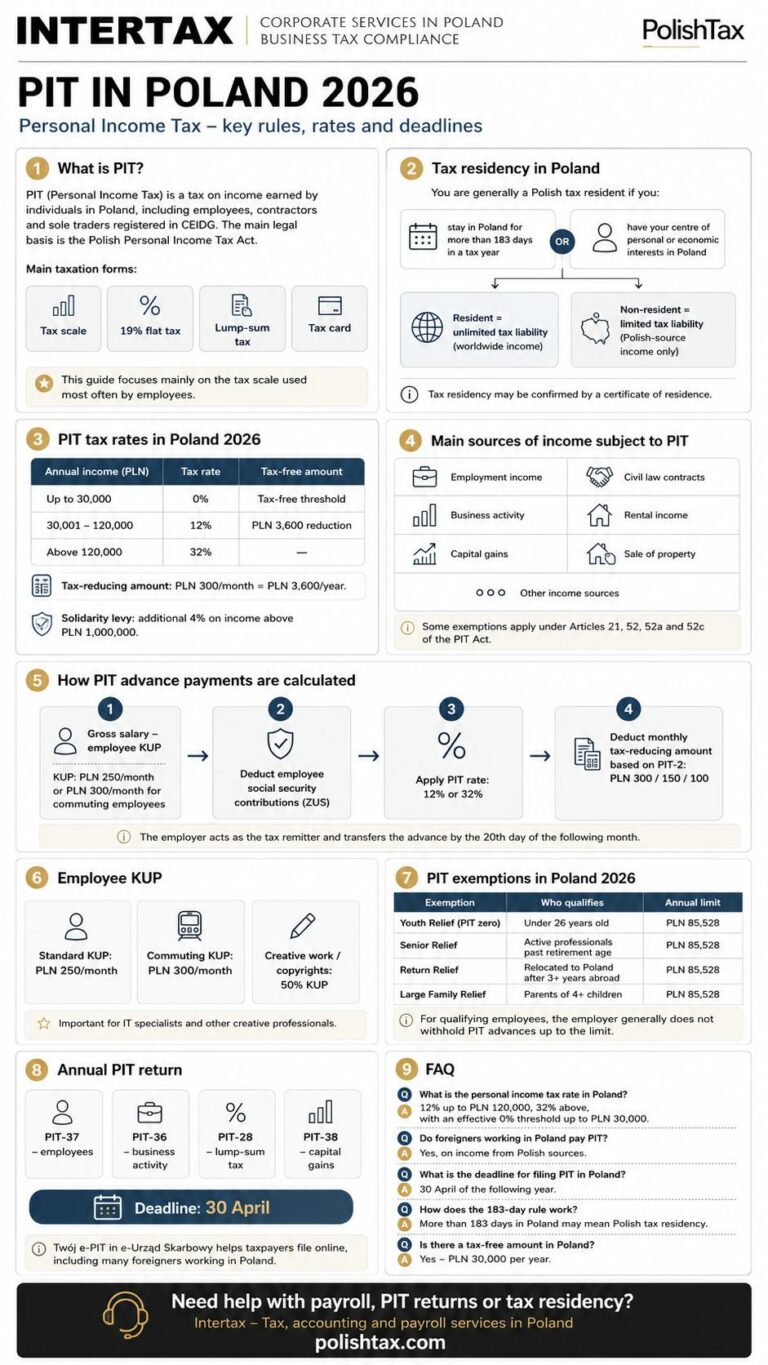
For the 2025 tax year, the key structural change revolves around the tax-free amount (kwota wolna od podatku). Under the current system, this amount is 11,120 zł annually, meaning the first 11,120 złoty of your annual taxable income is not taxed at all. The legislative proposal circulating for 2025 aims to raise this figure significantly, with government proposals pointing toward an increase to approximately 14,000 zł or higher depending on the final budget vote. The nominal tax rates themselves — 12% for income up to the upper bracket threshold and 32% above it — are expected to remain unchanged, but the interaction between a higher tax-free amount and the bracket threshold creates real arithmetic differences that matter for mid-income earners. Here is the mechanical process as it currently works. You start with your gross annual income. From that, you subtract mandatory social security contributions (ZUS), which include pension, disability, and health insurance. The health insurance portion is not deductible from taxable income, but the pension and disability contributions are. What remains is your tax base. You then subtract the tax-free amount. If the result is zero or negative, you owe no income tax. If it is positive, you apply the 12% rate to the portion up to the bracket threshold (currently 120,000 zł) and the 32% rate to anything above that. Finally, you subtract any applicable tax credits, such as the charitable donation credit or the school card allowance, and you arrive at your total tax liability for the year. Your employer has been withholding against this throughout the year, so the difference between what was withheld and what you actually owe is either a payment you make or a refund you receive. I worked through a specific edge case last year that illustrates why people get surprised by their April filings. A client of mine had a gross annual salary just slightly above the threshold where the tax-free amount begins to phase out. The phase-out kicks in at 68,000 zł of annual income, reducing the tax-free amount by 12% of every złoty earned above that figure. For someone making 70,000 zł, the tax-free amount is reduced by 240 zł (12% of 2,000), leaving only 10,880 zł instead of the full amount. Most payroll software handles this automatically, but if you have multiple income sources or variable monthly earnings, the phase-out can hit you unexpectedly. I found that recalculating the effective marginal rate on a spreadsheet — accounting for the phase-out as an implicit tax — showed the real tax burden was closer to 25% on that incremental income, not the headline 12%. That realization alone changed how I advise people about taking on side income or negotiating salary bumps.
Another counter-intuitive detail that trips people up involves the interaction between the tax-free amount and the 32% bracket. Because the tax-free amount is subtracted before the progressive brackets are applied, raising it does not simply reduce your tax bill linearly. It shifts your entire taxable base downward, which means more of your income stays in the 12% bracket rather than crossing into the 32% bracket. For someone earning 150,000 zł, even a 2,000 zł increase in the tax-free amount can save more than 240 zł in actual tax, because it keeps a portion of income that would otherwise be taxed at 32% down in the 12% zone. The math is straightforward once you map it out, but nobody explains it that way in the official documentation. The young person's tax relief (ulga dla młodych) remains relevant for taxpayers under 26, exempting income up to 85 times the monthly minimum wage from taxation. For 2025, assuming the minimum wage stays near current levels, this effectively shields roughly 160,000–170,000 zł of annual earnings from income tax entirely. This relief stacks on top of the standard tax-free amount, which creates a compound benefit that young earners should not overlook. I have seen too many people in their early twenties file their PIT and discover they overpaid throughout the year because they did not claim the relief properly on their annual return, even though their employer was already withholding correctly. There is a practical bottleneck worth noting about the proposed 2025 changes. The legislative process in Poland moves slowly, and tax law changes often get announced in the autumn budget bill but are not fully finalized until December. This means that for much of 2024 and early 2025, employers will continue calculating withholdings based on the current rules, and any refund or additional payment will depend on the final enacted figures. If you are planning your finances around anticipated tax reductions, treat the published proposals as directional guidance rather than a guarantee. The 2025 tax tables are officially published by the Ministry of Finance in the autumn preceding the tax year, and that is when you should lock in your assumptions.
Get the Full Details
For anyone needing the official reference documents, the Polish tax tables and detailed calculation guidelines are published on the Ministry of Finance website (gov.pl) under the PIT section. The annual tax return forms (PIT-36, PIT-37, PIT-28 depending on your income type) are also available there for download. I typically recommend printing the current year's form alongside last year's and comparing line by line when you encounter any discrepancy — it is the most reliable way to catch errors before you submit. The broader takeaway is that the Polish PIT system rewards people who understand the mechanics rather than those who assume the withholding is final. The annual recalculation exists precisely because monthly withholding is inherently imprecise. Whether the 2025 changes ultimately deliver meaningful relief depends on the final enacted tax-free amount and how it interacts with your specific income profile. Run the numbers yourself using a simple spreadsheet before relying on any summary article or payroll estimate. The arithmetic will tell you more than the political rhetoric.