Why Every Dollar Of American Mineral Reserves Isn't Worth What You Think
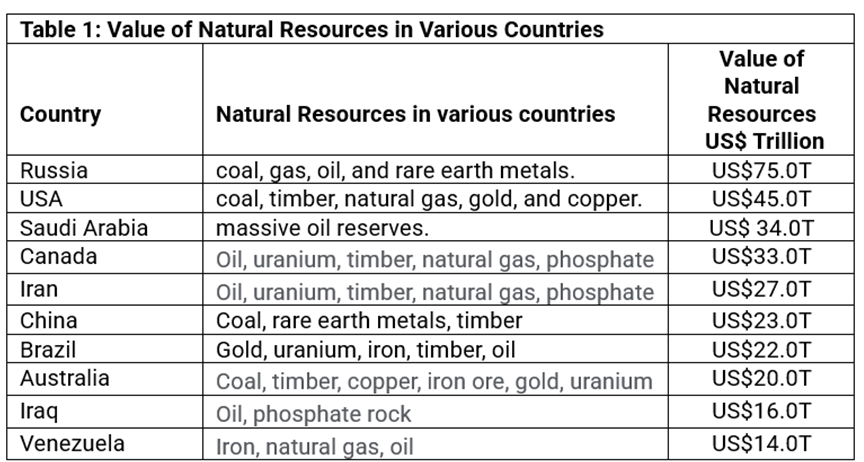
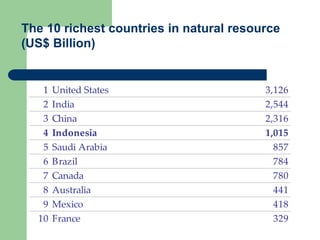
The United States holds somewhere around $40 trillion in estimated natural resource value, according to a 2021 Geological Survey study. That number gets thrown around in policy circles and think tank reports without much scrutiny. Most people reading it assume it means we have untapped wealth sitting in the ground waiting to be mined or drilled. It doesn't work that way. The actual economics are messier, the geopolitics more complicated, and the environmental trade-offs far from abstract. I spent roughly eight years working in resource economics and land use planning, mostly in the Rockies and the Permian Basin. One project I was involved with involved evaluating a proposed critical minerals lease in eastern Idaho. The preliminary geological survey suggested over $2 billion in contained value for rare earth elements and lithium. The actual permitted mine, three years later and $400 million into development, was producing at maybe 15% of the modeled reserve estimate. The difference wasn't bad geology. It was permitting delays, water rights litigation, and a shift in lithium prices that made the lower-grade deposits uneconomic to process. The $2 billion figure was real in the sense that the rocks contained those minerals. It was not real in any sense that mattered to a balance sheet.
Untapped Wealth And Global Stakes An Overview Of The United States Natural Resource Treasury
The concept of a natural resource treasury isn't new. It goes back to the early 2000s when the USGS started producing more systematic estimates of domestic mineral endowment. The idea is straightforward: map what's here, estimate the market value, and you get a picture of national wealth that isn't captured in GDP or financial markets. On paper it makes sense. In practice the gaps between measured resource and mineable reserve are enormous. Here's how the numbers actually break down across categories. The US holds the world's largest known uranium reserves, roughly 860,000 metric tons at currently economical extraction costs. That translates to about $30-40 billion at current spot prices, though uranium prices fluctuate between $40 and $100 per pound depending on reactor demand and geopolitical supply constraints. Coal reserves are estimated at over 250 billion short tons, but only a fraction is surface-minable and economically competitive against imported coal or natural gas. The Marcellus and Haynesville shale gas plays alone contain trillions of cubic feet of recoverable natural gas, which at current Henry Hub prices of roughly $2.50-$3.50 per MMBtu represents real but price-volatile wealth. The critical minerals category is where the geopolitical stakes actually live. Rare earth elements, lithium, cobalt, graphite, and tellurium are concentrated in deposits across the western states. China controls roughly 60% of global rare earth mining and 85-90% of processing capacity. The Mountain Pass mine in California is the only operating rare earth facility in the US, and for years it shipped its concentrate to China for separation and refining. Building domestic processing capacity is the stated priority of multiple administration policy frameworks, but the capital requirements are severe and the timeline from permit to production typically runs seven to twelve years for greenfield projects.
Water as a resource deserves a separate category entirely. The Colorado River Basin supports 40 million people and $1 trillion in agricultural output. The aquifer systems underneath the Ogallala and the Central Valley are being drawn down at rates that most hydrogeological models consider unsustainable beyond mid-century. Valuing water is notoriously difficult because it's not a commodity in the traditional sense. Markets exist in some regions through water rights trading, but the pricing mechanisms are fragmented and often disconnected from actual scarcity conditions. Timber resources on federal lands generate roughly $2-3 billion annually in timber sales, but the debate over old-growth preservation versus commercial harvest continues to cycle through courts and congressional appropriations. The actual volume of commercially viable timber on US Forest Service lands has declined significantly since the 1990s, partly due to wildfire risk and disease, partly due to legal challenges that have removed millions of acres from active management. The global dimension matters because resource wealth isn't just about what's in the ground. It's about who can extract it, who buys it, and what leverage that creates. The US is simultaneously the world's largest energy producer and a significant importer of refined products and critical minerals. Being the top oil and gas producer gives the country substantial geopolitical flexibility, particularly in European energy markets since the shale revolution. But being dependent on foreign-sourced rare earths and lithium creates vulnerability that adversaries are well aware of.
Get the Full Details
I've sat in meetings where the discussion shifted from "do we have the resources" to "can we process them domestically before the next trade restriction hits." The answer has historically been no, and the infrastructure gap hasn't closed at a rate that matches the stated policy urgency. Building a rare earth separation facility costs between $500 million and $2 billion depending on scale and technology. The operating margins are thin unless you're running at near-full capacity with stable feedstock grades. Many proposed facilities in the US and Australia have stalled at the feasibility study stage because the economics don't clear the hurdle rate when Chinese processing costs are factored in. There's also the issue of land access. Roughly 26% of US land is federally managed, and the Bureau of Land Management and the Forest Service control access to a significant portion of known mineral deposits. The General Mining Law of 1872 still governs hard rock mining on federal lands, which means qualified claim holders can obtain mining permits at relatively low filing fees. This framework was designed for a different era and doesn't account for modern environmental review requirements, which add years and millions of dollars to project timelines. The result is a system where the legal right to mine exists but the practical path to production is obscured by overlapping jurisdiction and uncertain regulatory outcomes. The Treasury Department has flagged critical mineral supply chains as a national security concern in multiple annual reports since 2019. The Department of Energy's Critical Minerals Institute tracks processing gaps and identifies priority materials. The Bipartisan Infrastructure Law allocated roughly $12 billion toward domestic critical minerals processing and recycling, but disbursement has been slower than projected and individual project awards have been selective. Some analysts estimate that only about 30-40% of allocated funds have been committed to specific facilities as of early 2024.
On the agricultural side, the US produces about 30% of the world's corn and soybeans using roughly 400 million acres of cropland. The soil resource itself—the topsoil that took millennia to accumulate—is being lost at rates that soil scientists consider alarming. The USDA estimates average erosion rates of 4-5 tons per acre annually on cropland, though conservation tillage and cover cropping have reduced that in many regions. Soil as a natural resource isn't typically counted in the treasury framework, but it should be. Losing an inch of topsoil can reduce yields by 6-11% for corn and 7-10% for wheat, and that loss is irreversible on any human timescale. The fisheries and marine resources category is another area where the treasury concept falls short. US Exclusive Economic Zones cover about 4.3 million square miles, making them among the largest in the world. Commercial fisheries landings average $2-3 billion annually, with aquaculture adding another $1-2 billion. The problem is that many domestic fisheries are either fully exploited or overexploited according to NOAA assessments, and the quota systems that manage them are politically contested and frequently litigated. The wealth exists but it's not growing, and in some cases it's declining. Geothermal energy represents an underdeveloped category in most treasury assessments. The US has the world's largest installed geothermal capacity at roughly 4.2 gigawatts, primarily in the Geysers complex north of San Francisco. Enhanced geothermal systems could potentially unlock resources across the Basin and Range province, but the technology is still maturing and the drilling costs remain high. A successful EGS project in 2018 at Fervo Energy's site in Nevada demonstrated viability, but scaling that to utility-scale deployment requires billions in further investment and a favorable power purchase environment.
What's often missing from these discussions is the distinction between resource endowment and economic availability. The US might have the minerals. It might have the technology to extract them. It might even have the market demand. What it frequently lacks is the combination of all three at the same location with acceptable environmental and social conditions. Every mine, every well, every timber harvest site creates winners and losers, and the losers usually have more immediate local influence than the abstract national interest argument. I worked on a project where the state geological survey had mapped what looked like a highly prospective lithium brine deposit in the Great Basin. The preliminary data suggested grades comparable to the Salar de Atacama in Chile, which is one of the world's lowest-cost lithium producers. But the US deposit sat on land with competing surface uses—cattle grazing, wildlife habitat, and existing water rights that predated the mineral claim. The extraction process for brine lithium is water-intensive, and in an arid region where water allocation is already politically explosive, that created an immediate ceiling on feasible production scales. The resource was real. The economics were not favorable under the constraints that actually applied. Another common misconception is that natural resource wealth automatically translates into economic benefit for host regions. The extractive industries literature is full of examples where resource revenues concentrate at the state or federal level while local communities bear the environmental and infrastructure costs. Alaska's Permanent Fund is a relative success story, distributing oil revenues directly to residents. Most resource-rich counties don't have anything like that mechanism, and the fiscal mismatch between where resources are extracted and where the revenue is counted is a persistent structural problem.
The valuation methodology itself deserves scrutiny. The USGS uses a range of approaches depending on the commodity. For metals, they typically apply a long-term price assumption, which tends to be conservative compared to spot prices during commodity booms. For energy resources, they model recoverable volumes at different price scenarios. None of these methods capture the option value of keeping resources unextracted in case prices rise significantly, nor do they adequately price in the declining marginal returns that come from extracting lower-grade deposits as easier resources are depleted. Environmental externalities are systematically underweighted in treasury valuations. Carbon sequestration potential from forests and wetlands, groundwater recharge capacity, biodiversity value, recreational use value—these are real economic benefits that disappear when land is converted to extractive use. A 2020 study estimated that ecosystem services on US public lands generate between $100 and $400 billion annually, but this flows into federal accounting in ways that are disconnected from resource extraction revenue streams. The two sides of the equation rarely meet in policy discussions. The international context has shifted significantly since the last major comprehensive assessment. The COVID-19 supply chain disruptions, the war in Ukraine, and the ongoing strategic competition with China have all accelerated interest in domestic resource development. The Inflation Reduction Act's domestic content requirements for electric vehicle tax credits directly tie mineral sourcing to market access, creating a policy-driven demand signal that didn't exist five years ago. This is changing project economics in ways that older treasury models don't reflect.
Domestic demand for critical minerals tied to energy transition is projected to grow 300-600% by 2050 under most scenario analyses. The US currently produces zero percent of its lithium demand from domestic sources, about 0% of its graphite, and roughly 15% of its rare earths. Filling those gaps requires not just finding the resources but building the entire supply chain from mining through refining to manufacturing, which is a multi-decade undertaking even under optimistic assumptions. The practical takeaway for anyone trying to use this kind of resource inventory is that the headline numbers are real but insufficient. They describe physical reality, not economic reality. A reserve estimate is a statement about geology, not finance. The conversion from resource to reserve to production to revenue involves engineering studies, permitting processes, capital raising, market conditions, and regulatory decisions that can each introduce order-of-magnitude uncertainty. Anyone citing a natural resource treasury figure should immediately contextualize it with those caveats, and most people who cite the figures don't bother. If you're looking at this from a policy perspective, the actionable insight is that resource existence is necessary but nowhere near sufficient. The binding constraints are processing capacity, permitting timelines, water availability, and community acceptance. These are harder to solve than geological questions, and they don't respond well to funding announcements. They require sustained institutional capacity that the US has historically struggled to maintain in the extractive sectors.
From an investment angle, the gap between headline resource value and extractable value is where the risk and opportunity both live. Companies that have navigated permitting successfully and secured off-take agreements at favorable terms are trading at premiums that reflect their execution track record, not their geological prospects. The market has learned, through repeated disappointment, that a big resource estimate means very little without the rest of the package. The natural resource treasury is a real thing. It's just not the savings account that some policymakers treat it as. It's more like a scattered collection of partial payments on an instrument that matures on unpredictable schedules, with fees and taxes deducted along the way, and occasionally with the counterparty defaulting entirely. Understanding that distinction changes everything about how you approach the question of whether the United States is actually resource-rich or just geologically interesting.