What Undepreciated Capital Cost Actually Is
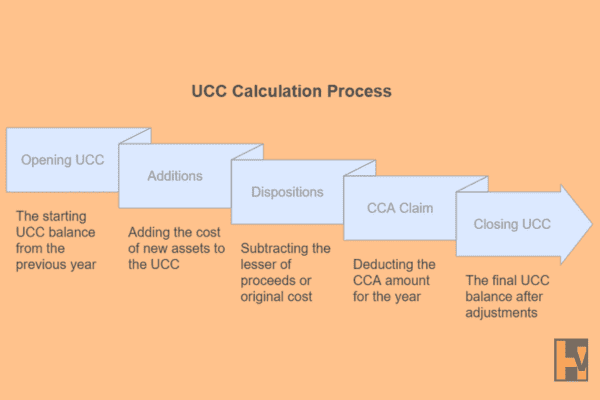
UCC is a running cumulative balance for each depreciation class in Canada's income tax system. It is not a balance sheet account. It shows how much of the capital cost base remains available for future capital cost allowance claims after accounting for all purchases, disposals, and CCA taken to date. The concept exists because the tax system allows accelerated write-offs that do not match economic depreciation, so something needs to track the gap between what was paid and what has been claimed against the CRA. I used to think UCC was just a subtraction problem. Then in 2019 I inherited a client's books and found a Class 8 bank with a negative UCC balance of about $34,000, which the previous accountant had simply ignored until the CRA issued a reassessment. The problem was that a prior disposal of equipment had triggered a recapture, but nobody had actually reported it on the T1 or T2. Negative UCC is one of those things that quietly compounds. Every year you carry a negative balance forward, the next disposition calculation uses that negative number as if it were zero, which understates recapture. The fix was a T1 Amendment Request with a Schedule 3 schedule adjustment and a letter explaining the error to the reviewer. I do not recommend ignoring it. The basic formula for any class is straightforward enough that most people overcomplicate it. You start with the opening UCC balance, add acquisitions during the year, subtract the lesser of cost or proceeds from dispositions, apply the half-year rule on net additions if it still applies, claim your CCA at the prescribed rate, and arrive at the closing UCC that rolls forward to the next fiscal period. The half-year rule matters more than people realize. It only applies to the net addition amount, not the gross amount of every purchase you make in a year. If you bought $120,000 of equipment and sold $80,000 of older equipment in the same year, the half-year rule applies to the $40,000 net increase, not the full $120,000. That single mistake can throw off your CCA claim by several thousand dollars depending on the class rate.
ClaSS 10 and 10.1 are where most errors surface. Class 10 covers automobiles and certain other equipment at a 30% declining balance rate. Class 10.1 applies specifically to passenger vehicles purchased after 2017 where the capital cost exceeds the prescribed limit. The limit changes annually. For 2024 it is $55,000 before tax, which means the UCC calculation for a $70,000 vehicle is capped at $55,000 regardless of what you actually paid. The difference between the actual cost and the capped amount gets trapped in a separate sub-account within Class 10.1 and can only be recovered when the vehicle is disposed of. I have seen CPAs miss this entirely and claim CCA on the full purchase price, which triggers a CRA flag almost immediately.
Disposals And The Recapture Trap
When you sell an asset, you remove the original cost from the class and compare it to the proceeds. If the proceeds exceed the remaining UCC in that class, the excess is recaptured income and fully taxable. If the proceeds are less than the UCC, the shortfall reduces the closing UCC balance. This is where the system gets subtle. Recapture is not calculated on an individual asset basis. It is calculated at the class level after all additions and dispositions for the year are netted together. Selling one piece of equipment at a gain does not automatically create recapture if the overall class UCC can absorb the difference. I worked with a manufacturing company last year that sold a CNC machine for $150,000 that originally cost $180,000. The UCC in Class 10 was $45,000 after years of 30% declining balance claims. They expected a $30,000 terminal loss. Instead, the CRA disallowed the loss because the company had also purchased $200,000 of new machinery during the same year. The net addition rule meant the Class 10 UCC increased rather than decreased, and the disposition simply reduced the new larger balance. The lesson is that you cannot analyze a single disposal in isolation. The class-level picture changes everything.
Get the Full Details

Second-Hand Purchases And The Proceeds Cap
This is the part most people do not expect. When you buy used depreciable property, the amount you can add to UCC is the lesser of the actual cost or the seller's original capital cost. In theory this makes sense because you should not be able to increase the pool beyond what was originally capitalized. In practice it creates a headache when the seller's books are incomplete or lost. I had a client purchase a used warehouse loading dock system for $62,000 from a bankrupt estate where the seller's records were destroyed. Without documentation of the original capital cost, the CRA would only allow the lesser of cost or the unknown original amount. I resolved it by obtaining a written declaration from the seller's liquidator stating the original cost, which the CRA accepted. If you cannot get that documentation, you are limited to the actual purchase price as the UCC addition regardless of what the asset was originally worth to the seller. When an entire class is emptied out because all assets have been disposed of, two things can happen. If the total proceeds exceed the UCC balance, the difference is recapture. If the total proceeds are less than the UCC balance, the shortfall is a terminal loss that is fully deductible against ordinary income. Terminal losses are valuable because they do not get restricted by the same rules that limit regular CCA claims. A $50,000 terminal loss in Class 8 reduces taxable income dollar for dollar in the year it occurs. However, there is a catch that trips up even experienced preparers. If you dispose of the last asset in a class and then acquire a replacement asset in the same class within the same taxation year, the class is not considered emptied. No terminal loss is available. The proceeds and the new acquisition net together and the UCC continues to roll forward. I advised a client to time a heavy equipment disposal to the end of the fiscal year precisely because he wanted the terminal loss. He also arranged for the replacement equipment purchase to occur in the following fiscal year, which allowed the terminal loss to crystallize. The timing saved him approximately $18,000 in current year taxes on a $45,000 terminal loss at his effective rate.
Investment Tax Credits And Their Interaction With UCC
When a company claims an investment tax credit, the UCC of the affected class must be reduced by the amount of the credit claimed. This is a mandatory reduction that happens before CCA is calculated. The reasoning is simple. If the government gave you a direct cash subsidy for purchasing the asset, the depreciable base should be lower. Many small business owners forget this step entirely. I ran into this with a client who had claimed the ITA 125 investment tax credit on qualifying manufacturing equipment in 2022. The UCC on their Schedule 8 had never been adjusted for the credit. When the CRA reviewed the return, they adjusted the UCC retroactively, which increased the CCA claimed in prior years and triggered a recapture adjustment. The moral is that any ITIC claimed requires a corresponding UCC reduction in the same taxation year, and the adjustment must be made on Schedule 8 of the T2. The most reliable approach I have found is maintaining a separate ledger for each class throughout the year rather than waiting until tax time to reconstruct everything. Each acquisition and disposal gets recorded with the date, amount, class, and whether the half-year rule applies. At year end you run the numbers once and verify them against the prior year's closing balance. If the numbers match, you file. If they do not, you investigate before submission. Reconciling UCC schedules after the fact takes roughly three times longer than doing it continuously, based on my experience with clients who switch between the two approaches. I use a simple spreadsheet template that pulls data directly from the general ledger. Each row represents a single transaction with columns for date, asset description, capital cost, proceeds on disposal, class number, half-year flag, and CCA rate. The template calculates the running UCC balance automatically. When I hand a client's file to another CPA for review, this template cuts the reconciliation time from about two hours down to roughly fifteen minutes. The CRA also tends to accept schedules that show line-by-line detail rather than summary totals.
Where The System Breaks Down
UCC calculations assume a stable tax environment. They do not handle well when legislative changes occur mid-year. The introduction of the half-year rule expansion in 2018, the changes to Class 10.1 limits, and the temporary acceleration of CCA rates during the pandemic all required retroactive adjustments to existing UCC balances. Nobody keeps clean records through that kind of volatility. If your class has survived multiple legislative changes with poor bookkeeping, the most practical solution is often to engage a tax specialist to reconstruct the UCC history from source documents, which will cost between $2,000 and $5,000 depending on complexity. Failing to do so leaves you exposed to CRA assessments that can exceed that cost significantly. Another scenario where UCC-based analysis becomes unreliable is when assets are used partly for personal purposes. The CCA claimed on mixed-use property must be reduced by the personal use percentage, but the UCC reduction does not always reflect that adjustment cleanly. I encountered a situation where a practitioner reduced the UCC by the full personal use percentage rather than just reducing the CCA claim, which artificially inflated the terminal loss on disposal. The CRA disallowed the excess loss and added interest. The correct treatment is to claim reduced CCA each year while keeping the full UCC intact, then calculate any terminal loss or recapture on the undiminished balance.
What To Do When You Face A Disposition With Unclear UCC
If your UCC records are incomplete or you suspect an error, do not file the return and hope nobody notices. The CRA has access to seller information through third-party reporting in many cases, and mismatches between your UCC and theirs are detectable. The safest path is to file an amendment or seek a letter ruling from the CRA's chief pathology officer before filing the current return. A letter ruling costs nothing and provides binding protection if the CRA later challenges your position. I recommend this approach for any UCC situation where the opening balance cannot be verified with reasonable certainty, because the cost of a misstep is almost always higher than the cost of getting an advance determination.