Understanding How FSA Payments Flow Through Treasury Systems
When people work with flexible spending accounts in a government payroll context, they run into the same messy intersection repeatedly. You've got pre-tax dollars being deducted from a paycheck, claims getting submitted through whatever enrollment platform the agency uses, and then the actual disbursement side where Treasury payment codes kick in. The confusion mostly comes from nobody connecting those two pieces clearly. Here's how it actually works in practice. The Treasury side, particularly anything touching the standard payment processes and codes like the ones you'll see referenced in agency financial systems, is mostly about tracking where money goes and making sure it clears the right accounting buckets. For an FSA, the employee's contribution gets withheld through payroll as a pre-tax deduction. That money sits in a trust arrangement until the employee submits a qualifying expense claim. Once that claim gets approved, the payout happens through whatever disbursement method the plan sponsor uses — often direct deposit, but sometimes a debit card or reimbursement check depending on the plan design.
Unlocking The Potential Of Misc Pay Fsa Treas 310 Navigating The Complexities Of Flexible Savings And Tax Strategies
The "Misc Pay" designation you see in Treasury reporting is essentially a catch-all code for payments that don't fit neatly into standard salary or benefit categories. FSA reimbursements sometimes land in that bucket, especially when they're processed outside the normal payroll cycle or when the claim timing doesn't match a regular pay period. This creates headaches for anyone trying to reconcile accounts or produce financial reports, because the transaction doesn't show up where you'd expect it to. Here's a specific problem I ran into last year that took about three weeks to resolve. An agency employee had elected to participate in the health FSA and had submitted a large dental claim — roughly $2,400 for a procedure that spanned two fiscal years. The claim got approved in the new fiscal year, but the original election had been set up under the prior year's budget allocation. The Treasury payment system flagged it as a misc pay item because the funding source didn't match the original appropriation. The employee was waiting on the reimbursement and getting frustrated, while our office was stuck trying to figure out which fiscal fund the disbursement should pull from. The workaround was straightforward once you understand the sequence. We pulled the employee's FSA election form and traced the original premium contribution records back to the correct appropriation. Then we worked with the disbursing officer to reclassify the payment from the misc pay bucket to the proper benefit disbursement code. The entire reconciliation took about two days of back-and-forth with the finance office, but getting the code right mattered because misc pay classifications can trigger audit flags if they're left unaddressed. We also made sure to note the correction in the supporting documentation so the next person reviewing the account wouldn't stumble over the same issue.
The tax implications here are worth understanding clearly. FSA contributions reduce your taxable income in the year they're elected, which is the main advantage. But there are important rules around what counts as a qualified medical expense, and the IRS publishes that list annually in Publication 502. Eye exams, prescription drugs, and dental work are standard qualifiers. Over-the-counter medications now require a prescription to qualify, which changed a few years back and catches a lot of people off guard. If you reimburse yourself for an expense that doesn't meet the qualification, you could face penalties when you file your return. One counter-intuitive thing most people miss is the "use it or lose it" rule, though it's softened slightly by the carryover provision. For 2025 and beyond, you can carry up to $660 (adjusted for inflation) into the next plan year. Before that option existed, people who underestimated their medical expenses by even a few hundred dollars lost that money entirely. The planning strategy that actually works is to look at your previous two years of expenses, not just the most recent one, because health costs tend to vary significantly year to year. I've seen people calculate their election based on a single year with unusually high expenses and then underfund the next year, only to need more coverage when they actually had medical events. Another thing nobody talks about enough is the grace period option. Some FSA plans offer a two-month grace period at the end of the plan year, allowing you to incur expenses in January and February of the following year and still get reimbursed from the prior year's funds. This is different from the carryover provision and only applies if your plan sponsor has elected to offer it. It's a significant detail because it effectively eliminates the use-it-or-lose-it risk for about half of FSA participants. Check your plan documents carefully — the summary plan description will tell you whether this option is available.
Get the Full Details
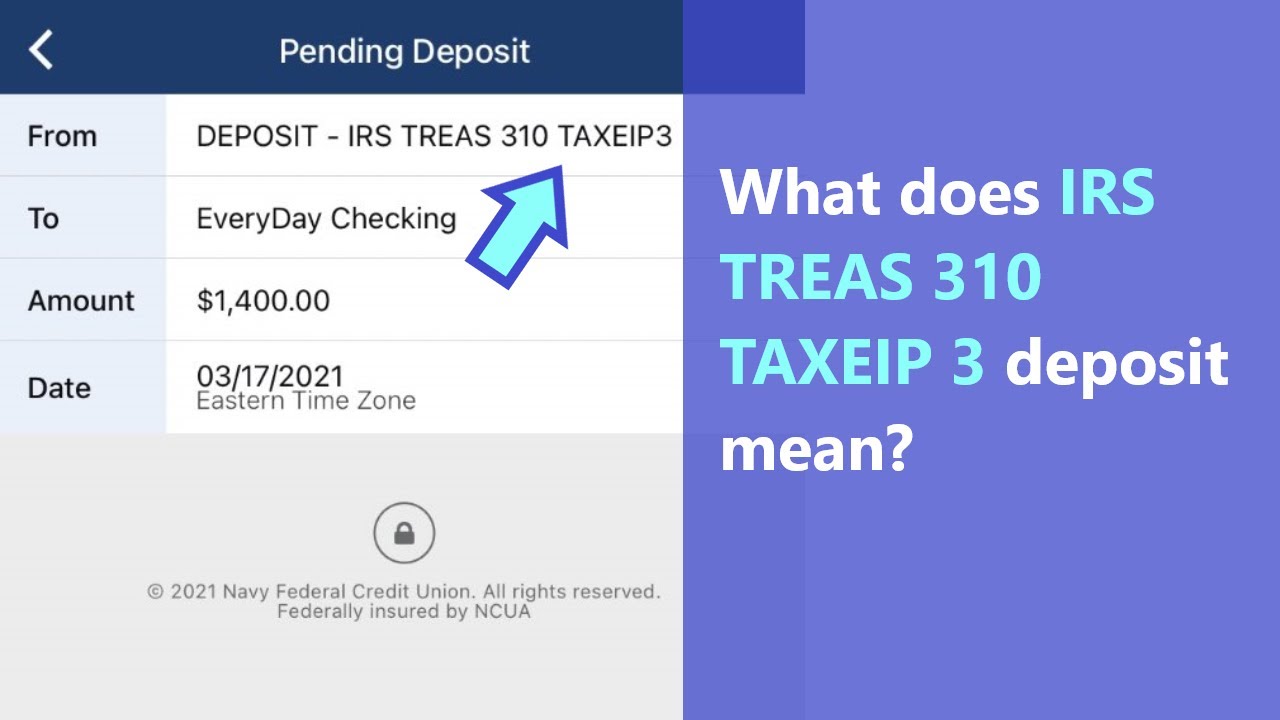
On the Treasury processing side, the main bottleneck people encounter is the timing mismatch between when a claim is submitted and when the payment actually posts. If you submit a claim in late December and the processing takes five business days, you might not see the reimbursement until the new year. That matters for tax reporting because the reimbursement is still tied to the prior year's pre-tax contributions. You'll see it on your W-2 in box 12 with code W, and it won't affect your taxable income regardless of when the payment actually hits your bank account. If you're managing this for someone else — a dependent, for instance — make sure the expense is yours to claim. You can reimburse yourself for qualified expenses paid by a dependent, but the dependent needs to meet the IRS definition, which generally means they qualify as your dependent on your tax return. There's no separate submission form needed for dependent expenses; you just keep the receipts and documentation in case the IRS asks. The other practical headache involves plan-year vs. calendar-year elections. Most FSA plans align with the calendar year, but some employers, particularly in the federal sector, may use a fiscal year that runs from October to September. This affects everything — when you make your election, when you incur expenses, when the use-it-or-lose-it clock starts ticking. If your plan uses a fiscal year, planning your large anticipated expenses around that timeline becomes important. A major dental procedure in March would count against a September-ending plan year's funds, while the same procedure in October would roll into the next year's election.
I also want to flag something that causes unnecessary problems. Several agencies allow a mid-year election change, but only under specific qualifying life events. Getting married, having a child, losing other coverage — those trigger the ability to change your FSA election. Simply deciding you picked too much or too little isn't a valid reason. People sometimes try to submit a change request just because their expenses turned out different than expected, and it gets denied. The documentation requirements for qualifying events are strict, so keep your marriage certificate, birth certificate, or loss-of-coverage letter on hand before you initiate the change. For the Treasury reporting side, if you're the one processing these payments, the key is making sure the misc pay classification gets resolved quickly. Every month those transactions sit in an unresolved status, they add noise to your financial reports and increase the likelihood of an audit finding. Pull the records monthly, match them against approved claim files, and reclassify anything that doesn't belong in the misc bucket. The process usually takes about fifteen minutes per month if you stay on top of it, but if you let it accumulate it can turn into a multi-day reconciliation project at audit time. There's no universal solution that covers every situation here because FSA plan designs and Treasury payment processing procedures vary by agency. The best approach is knowing your specific plan documents, keeping clean records, and not treating the misc pay flag as something that resolves itself. It doesn't. I've watched it compound across quarters and turn into a genuine compliance issue, so addressing it promptly when you see it is the only reliable strategy.