Getting Past the State Farm B2B Portal to Actually Sell
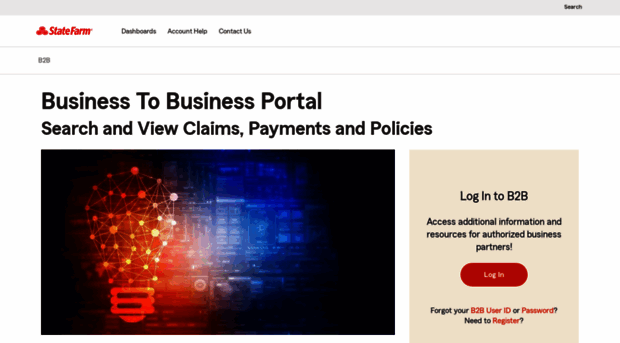
Most people treat the State Farm B2B portal like it is a simple ordering tool. It is not. It is a fragmented interface that was bolted together from several legacy systems, and understanding that fact changes how you use it every single day. I spent roughly nine months cleaning up quoting errors before I realized the platform was fundamentally designed for agents who had zero volume. If you are doing even moderate business through here, you will hit edge cases constantly.The portal handles commercial lines quoting, binding, and policy administration. That includes workers compensation, commercial auto, general liability, and various package policies. The interface itself is dated. You will find yourself toggling between multiple browser tabs because a single quote often requires data entry in two separate subsystems. This is normal. Do not assume you are doing something wrong. Start by understanding the difference between the standard agent portal and the B2B commercial platform. They are not the same system. New users frequently log into the wrong interface and waste an hour trying to find commercial quotes. The B2B portal URL is separate from the personal lines agent tools. Bookmark it immediately. I have seen agents lose deals because they searched Google and ended up on the wrong login page. The quoting engine has a specific limitation that most people discover too late. If you enter a NAICS code that is flagged as high risk, the system sometimes stalls at the premium calculation stage without throwing an error. The page just hangs. I ran into this with a construction client using NAICS code 238990. The quote appeared to process normally but never actually submitted. The workaround is simple: after entering the NAICS code, check the risk assessment field manually before hitting submit. If it shows any warning icons, switch to manual underwriting submission instead of relying on automated quoting.
Binding authority works differently than you might expect from other carriers. State Farm B2B portal does not grant automatic bind authority for most commercial products. You will typically need to request bind authority through a separate approval process that can take five to ten business days. During that waiting period, you can still quote and submit, but you cannot bind until approval comes through. I keep a running tracker in a shared spreadsheet so my team knows exactly which accounts need binding and which are still pending approval. This usually prevents the awkward phone calls where a client is waiting on the phone and the agent does not know the bind status. One thing nobody mentions is the renewal batch processing delay. When you have a book of business renewing, the portal does not process all renewals simultaneously. It works in waves based on policy type and account size. A group of fifteen commercial auto renewals might process on a Tuesday while your general liability renewals do not appear until Thursday. If you are running a renewal drive, check the portal twice a day starting three weeks before the renewal date. Do not assume everything will show up on the same day. The report generation side is functional but limited. You can pull renewal reports, production summaries, and some endorsement histories. What you cannot do is export custom date ranges with specific commission tiers in one query. I built a workaround using CSV exports from three different report types and then merging them in Excel with pivot tables. It adds about twenty minutes to my monthly reporting routine but saves me from chasing answers through supervisor channels.
There are real bottlenecks with this platform. The search function for existing policies is unreliable when you only have partial information. Searching by insured name alone frequently returns duplicate results because the system does not deduplicate well. The most reliable search method is by policy number or by exact address. If you do not have the policy number, pull the account from your own CRM first and then look it up in the portal. Trying to search a portal with loose criteria wastes time. Another frustration is the endorsement processing timeline. Same-day endorsements are not guaranteed even when the portal shows an estimated same-day completion. I learned this the hard way with a client who needed a certificate of insurance added to an active policy before a contract signing deadline. The portal showed the endorsement would process the same business day. It did not. It took forty-eight hours. The workaround is to submit endorsements at least forty-eight hours before you actually need them, and to call the support line to confirm processing status if a hard deadline is involved. Training resources exist but they are scattered. There is no centralized knowledge base within the portal itself. The official training videos are hosted on a separate State Farm partner site and are often out of sync with current portal updates. I recommend watching any training video that looks relevant and then immediately testing the feature in a sandbox or test environment. The portal updates happen frequently enough that video guides can be several months behind.
Get the Full Details

The support infrastructure has improved but it is still fragmented. There is a dedicated B2B agent support line, but wait times vary from twelve minutes on a Wednesday morning to over an hour on a Monday afternoon. The worst time to call is during the first two hours of the business day. If your issue is not urgent, call between ten and eleven in the morning on a weekday. Commission tracking through the portal is accurate but only updated on a monthly cycle. You will not see real-time commission accruals. If you are running on tight cash flow and need commission estimates between statement cycles, you will need to calculate them manually based on your quote submissions and binding records. I keep a simple running ledger that tracks estimated commissions per policy and compare it against the official statements at month end. The variance is usually less than three percent. The portal does not integrate well with third-party CRM platforms. API access is limited and primarily available to larger agency groups with volume commitments. If you are a small to mid-size operation, you are likely entering data manually into both systems. This duplication is the single biggest time sink in the entire workflow. Automating what you can with browser extensions or data entry templates reduces the friction considerably.
For new accounts, the application process requires uploaded documents in specific formats. The portal accepts PDF and certain image formats, but files over five megabytes get rejected without clear error messaging. I compress all documents down to two megabytes before uploading. It eliminates a common rejection reason that slows down account setup by one to two business days. The learning curve is steeper than it should be, but the platform becomes manageable once you stop treating it like a modern web application and start treating it like the legacy hybrid it actually is. The key is patience, systematic workflows, and knowing when to bypass the automated tools in favor of direct underwriter communication. Most problems that seem technical turn out to be process gaps that can be solved with a phone call or a spreadsheet adjustment.