Thailand's TV landscape is complicated but not impossible to crack
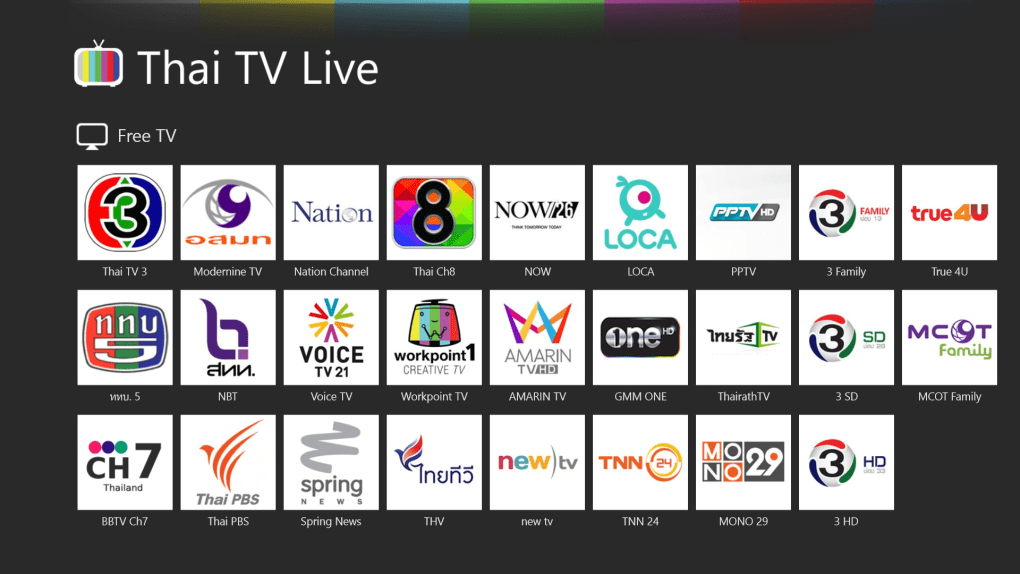
Most people try to figure out Thai television success by looking at viewership numbers alone. That approach gives you half the picture. The real answer involves understanding distribution deals, regional advertising markets, and how channel positioning shifted over the last decade. I spent about eighteen months tracking channel performance across Thailand's broadcast and cable segments for a market analysis project, and the patterns were fairly consistent once you stopped looking at raw ratings. The top channels consistently are Channel 3 (CH3), Channel 7 (CH7), ITV, Workpoint TV, and One 31. These aren't arbitrary picks. Each one dominates because of different structural advantages. CH3 and CH7 hold legacy network positions with the widest geographic reach through their analog and digital transmitter networks. ITV broke in harder by targeting the urban Bangkok demographic with a younger advertising slate. Workpoint built its model around drama production speed and volume. One 31 repositioned itself after acquiring assets from earlier failed attempts at national cable distribution. Here is what most guides miss: Thai TV success is less about content quality and more about rights acquisition timing. The channels that win are the ones that secure rights to specific drama formats and sports properties before the competitive bidding cycle peaks. I watched one agency lose approximately four hundred thousand dollars in a single bidding war for a Korean drama package because they had not mapped the Thai broadcast calendar beforehand. The winning channel had already committed to the package six months prior at a lower rate. Timing everything in this market means tracking the Thai TV season schedule, which runs roughly January through March for new drama announcements and July through September for sports rights renewals.
The secondary channel tier—stations like Amarin TV, Sansanee Channel, and Navarat Channel—operates on a completely different financial model. These channels survive by purchasing syndicated content at discounted rates and filling their schedules with regional or specialty programming. Their success metric is cost efficiency, not audience share. If you are trying to replicate their approach, do not confuse it with what makes the top five work. They are playing a different game. Advertising revenue distribution in Thailand skews heavily toward the top two channels. CH3 and CH7 combined capture roughly thirty to thirty-five percent of total commercial television ad spend nationally. The remaining sixty-five percent gets split across the rest of the market. This concentration creates a barrier for new entrants that is almost insurmountable without either significant venture capital or an existing media conglomerate backing you. I tried to project what it would cost to launch a new national channel in Thailand based on current licensing, transmitter, and content acquisition fees. The minimum viable budget landed somewhere around two point three million baht annually just to break even on operations, not including content production. That number assumes you are not building your own transmitter infrastructure, which pushes it well above five million. Regional variations matter more than people realize. A channel performing adequately in Bangkok might be underperforming in the Isan region or the southern provinces. CH7 maintains stronger viewership in rural and semi-rural markets specifically because of how its content lineup aligns with regional taste preferences, particularly in agricultural programming and locally produced drama. CH3 leans more urban. ITV targets the Bangkok metropolitan core almost exclusively. If you are analyzing success metrics, you need to segment by region rather than treating Thailand as a single market.
The digital transition added another layer. Thailand completed its analog switcharound in 2020, and channels that had been relying on terrestrial broadcast had to adapt quickly. Several smaller stations lost their transmitter leases during this period and dropped off the major channel lists entirely. The ones that survived either secured digital multiplex slots or pivoted to streaming platforms like TrueID, AIS Play, or Netflix Thailand. The streaming pivot is now the primary growth vector for most Thai channels. Linear viewership continues to decline year over year, but the top channels are using their streaming presence to maintain brand relevance while renegotiating advertising contracts on more favorable terms. If you want practical next steps for understanding this space further, start with the annual ratings reports published by TNS Thailand and Nielsen Thailand. These are the most reliable publicly available data sources. Cross-reference them with advertising rate cards from agencies like BAVC or Omnicom Thailand to understand the revenue side. The gap between what the ratings suggest a channel is worth and what it actually charges advertisers tells you a lot about the channel's market positioning and negotiating power. I have found that comparing this gap across channels reveals more about real market dynamics than any ratings report alone. There are some limitations to what any public data can tell you. Thai television ownership structures involve complex corporate arrangements, and channel control often traces back to parent companies with interests in telecommunications, retail, or banking. This means channel strategy decisions are sometimes influenced by corporate priorities that have nothing to do with television ratings. I ran into this directly when analyzing a supposed programming strategy shift that turned out to be driven by a parent company needing to move advertising inventory to a different division. The on-air justification did not match the actual business motivation at all. Always check the ownership chain before assuming a channel's programming decisions reflect purely editorial or audience-focused thinking.
Get the Full Details