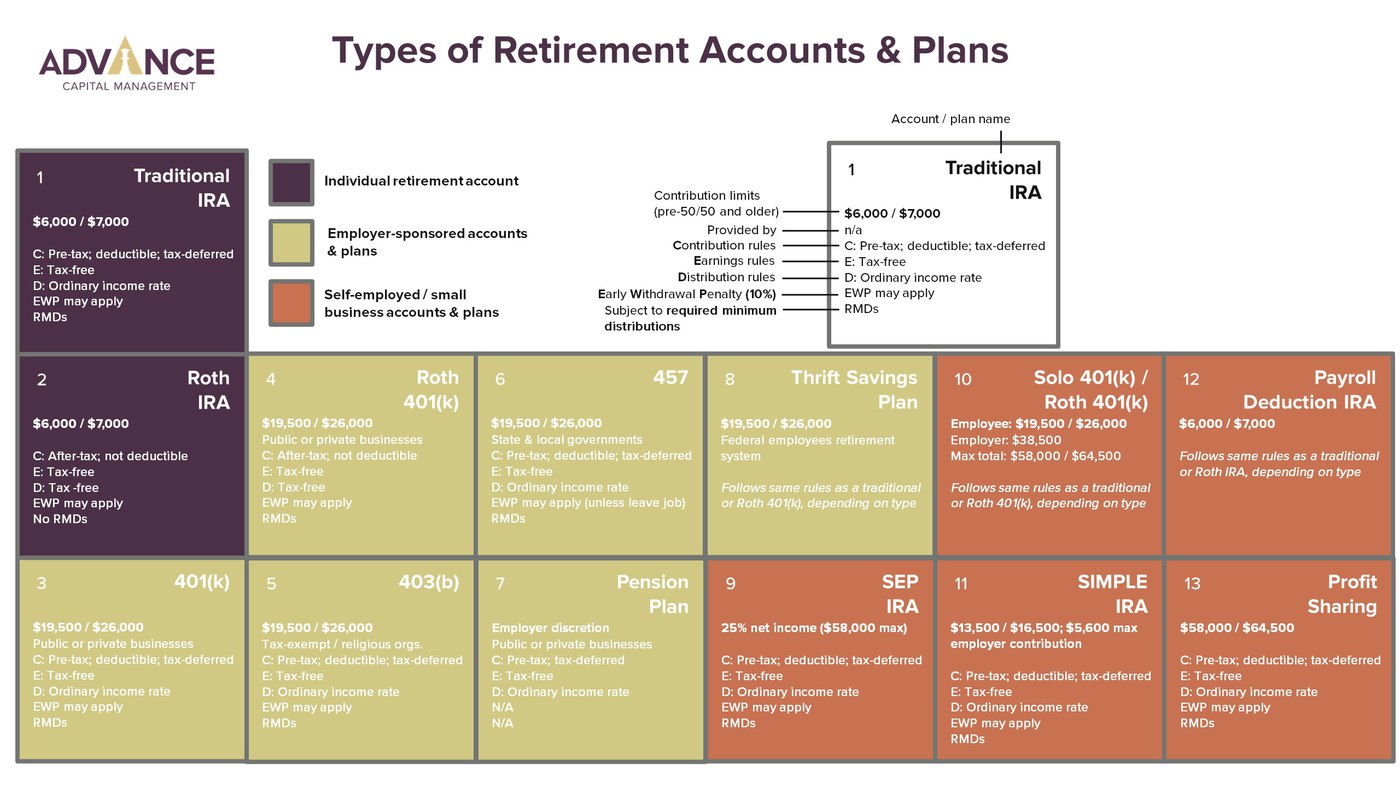
Understanding the Different Retirement Savings Vehicles Available to You
Most people pick their first retirement account because it was offered at their job. That usually means a 401(k), and that's fine. But the actual landscape is wider than most workers realize, and the differences between account types matter more than most people think they do. I've been working with retirement accounts for over a decade, and the thing I see most often is people stacking accounts without understanding how they interact. Let me walk through what actually exists out here, how they differ, and where the traps are. The big categories break down roughly into three buckets: employer-sponsored plans, individually-owned accounts, and government-backed options that have gotten a lot of attention recently.
The Employer-Sponsored Plans
A standard 401(k) lets you defer salary before taxes hit it. That traditional tax advantage is the whole point. You put money in pre-tax, it grows tax-deferred, and you pay ordinary income tax when you pull it out. The 2025 contribution limit is $23,500, with an additional $7,500 catch-up if you're 50 or older. Roth 401(k) options exist too, where you contribute after-tax dollars and pull it out tax-free in retirement. The 403(b) works basically the same way as a 401(k) but is restricted to employees of public schools and certain nonprofits. Same contribution limits. Same structure. It's just a different regulatory framework under section 403(b) of the tax code. The SIMPLE IRA is the small-business version. Both employer and employee contribute, but the limits are much lower—$16,000 in 2025, or $19,000 with catch-up. Employers have to match up to 3% of your salary or contribute 2% for everyone. It's simple by design, and that simplicity comes with a cost in flexibility.
The 457 plan is another one people overlook. It's for government and certain nonprofit employees, and here's the counter-intuitive part that catches most advisors off guard: 457 plans are NOT subject to the 10% early withdrawal penalty before age 59½. That means you can access 457 funds at age 50 if you leave your job, something no other retirement account lets you do cleanly. The downside is that 457 funds merge into a single limit with your 403(b) if you're in a government position, so you can't double-dip on contributions the way you might expect.
Get the Full Details

Individual Retirement Accounts
The traditional IRA is the fallback option. You can open one regardless of whether your employer offers a plan. Contribution limits are lower—$7,000 in 2025, or $8,000 with catch-up—but the tax treatment mirrors the 401(k). The catch is the income-based deduction phaseout. If you're covered by a workplace plan and your modified adjusted gross income exceeds certain thresholds, your deduction shrinks or disappears entirely. For 2025, the phaseout for single filers covered by a workplace plan starts at $77,000 and ends at $87,000. Married filing jointly covered by a plan phases out between $123,000 and $143,000. The Roth IRA has the same contribution limits but works in reverse tax terms. You contribute after-tax money, and qualified withdrawals in retirement are completely tax-free. There's no income limit on contributing anymore—you just can't directly contribute above certain MAGI thresholds and instead use the backdoor Roth method, which I'll get to.
The Backdoor Roth and Mega Backdoor Strategies
This is where things get technical and where most people miss opportunities. If your income is above the Roth IRA contribution limits, the backdoor Roth is the legal workaround. You contribute to a traditional IRA with nondeductible money—yes, that's allowed even if you earn too much for a Roth—then immediately convert it to a Roth IRA. The key word is immediately. If your traditional IRA balance includes any pre-tax money from rollovers or previous contributions, the pro-rata rule kicks in and a portion of your conversion becomes taxable. That's the trap most people fall into. I've seen people with $50,000 in an old 401(k) rolled into a traditional IRA try the backdoor Roth and end up owing significant taxes on what they thought would be a clean conversion. The workaround is to roll that old pre-tax IRA balance into your current employer's 401(k) if the plan accepts it, leaving only the nondeductible contribution in the IRA. That empties the pro-rata calculation down to zero. Not every plan allows inbound rollovers, so you need to check with your plan administrator before attempting this. The mega backdoor Roth is available if your employer's 401(k) plan allows after-tax (not Roth) contributions and in-service distributions or in-plan Roth conversions. You max out the standard 401(k) contribution at $23,500, then pile on after-tax contributions up to the overall limit of $69,000 in 2025 (or $76,500 with catch-up). That's potentially $45,500 in additional room going into a Roth. Very few plans allow this, but the ones that do offer a massive advantage for high earners.
HSA and Other Options
The health savings account isn't technically a retirement account, but it functions as one in practice. Contributions are triple-tax-advantaged: pre-tax, tax-free growth, and tax-free withdrawals for qualified medical expenses. After age 65, you can withdraw for any purpose without penalty—just ordinary income tax, same as a traditional IRA. Many people treat their HSA as a stealth retirement account once they hit that age threshold. The contribution limits for 2025 are $4,300 for self-only coverage and $8,550 for family coverage, plus a $1,000 catch-up if you're 55 or older. Taxable brokerage accounts fill the gap for people who've maxed out everything else. No tax advantages, obviously, but also no withdrawal restrictions or penalties. You pay capital gains rates on appreciation, which are typically lower than ordinary income rates, and you have complete access to your money whenever you want.

What Most People Get Wrong
The biggest mistake I see isn't picking the wrong account. It's not having an order. People throw money into whatever their paycheck deduction defaults to and never revisit it. Here's a more intentional approach: maximize any employer match first—that's free money and the highest return you'll get anywhere. Then max out your HSA if you're eligible. Then go back to the 401(k) or 403(b) and push toward the overall limit. Then hit the Roth IRA or backdoor Roth. Then return to the 401(k) if there's mega backdoor availability. Finally, anything left goes to a taxable account. The secondary mistake is ignoringRequired Minimum Distributions. Traditional IRAs and 401(k)s force you to take distributions starting at age 73 under current SECURE 2.0 rules. Those RMDs are calculated using IRS life expectancy tables and are taxed as ordinary income. Failing to take them costs you 25% of the amount you should have withdrawn. Many people assume Roth IRAs have RMDs too, but they don't—not during the original owner's lifetime at least. That's one concrete advantage of converting to Roth.
The Trade-offs You Need to Accept
No single account type is optimal for everyone. Traditional 401(k)s and IRAs make sense if you're in a higher tax bracket now than you expect to be in retirement. Roth accounts make sense if you're early in your career, in a lower bracket now, and expect to be in a higher one later. The honest middle ground is that nobody knows what tax policy will look like in 30 years. The SECURE Act and SECURE 2.0 have already changed RMD ages, contribution limits, and eligibility rules multiple times. What makes sense today might not in a decade. The real power comes from using multiple account types across different tax treatments. Having money in both traditional and Roth buckets gives you flexibility in retirement. You can control your taxable income by choosing which accounts to draw from each year, which matters enormously if you're trying to stay under thresholds for Medicare IRMAA surcharges or Medicaid eligibility. That kind of strategic withdrawal planning is impossible with a single account type. I worked with a client last year who had $800,000 in a single traditional 401(k) and was pulling $60,000 annually in retirement. He jumped into a higher Medicare bracket purely because of those withdrawals. If he'd split his savings across a Roth and a taxable account the way he should have, he could have kept his taxable income low enough to avoid the surcharge entirely. It cost him roughly $4,000 a year extra in Medicare premiums. That's not theoretical. That's a real, recurring cost that good account diversification prevents.