How the Best Buy Credit Card Actually Works For Regular Shoppers
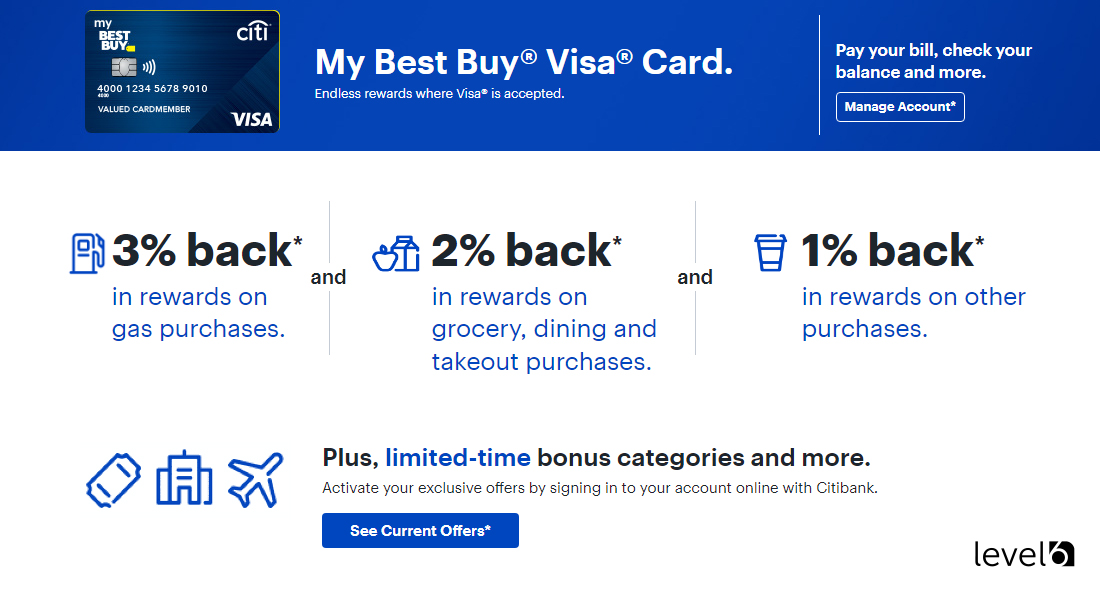
I've spent years watching people open store credit cards with unrealistic expectations, then abandon them after six months because the math never worked out. The Best Buy card situation is no different, but it does have some legitimate use cases if you actually understand how the rewards stack works and where the traps are. Let me walk through what the program really looks like from the inside. The credit card program at Best Buy runs through Synchrony Bank, which means it's a closed-loop store card with an optional general-purpose tier. There are three main variants: the My Best Buy Credit Card (standard), the My Best Buy More Rewards Credit Card, and the My Best Buy More Rewards Credit Card for Business. Each one has different reward structures, and most people I talk to don't actually know which one they signed up for. The standard card gives you 5 percent back on Most Things, which sounds generous until you read the fine print. "Most Things" excludes Apple products, certain Android devices, Samsung Galaxy phones, and a handful of other category exclusions that change periodically. So you could be swiping on a $1,200 MacBook and wondering why you're not earning the full 5 percent. The exclusions get updated roughly twice a year, and they never seem to favor the big-ticket items people actually want.
The More Rewards tier bumps you up to 8 percent back on Most Things for Top Members, but that tier requires spending $1,500 annually to qualify. I've had clients who hit that threshold in November during holiday shopping, only to realize they were on the hook for the higher spending requirement the following year with nothing to show for it except a statement credit they could have gotten elsewhere. Here's what nobody tells you about the rewards structure: the 5 and 8 percent rates apply to eligible purchases, but financing promotions completely change the math. If you put a purchase on a 24-month special financing offer and then pay it off early, some people assume they've "beaten the system." They haven't. Early payoff doesn't reduce your interest obligation on these store cards — the promotional rate is effectively zero interest, so paying early just means you've locked up your cash with no benefit. It's a common mistake I see every quarter. The application process itself is straightforward but has a hidden snag. When you apply, Best Buy runs a soft pull initially, but the actual approval triggers a hard inquiry on your credit report. I learned this the hard way when a client applied for the card, got declined, and then discovered the hard pull had already landed on their TransUnion file. They were trying to qualify for an auto loan two weeks later and the extra inquiry dropped their score enough to lose the better rate. If you're shopping around for credit, space out your applications by at least six months.
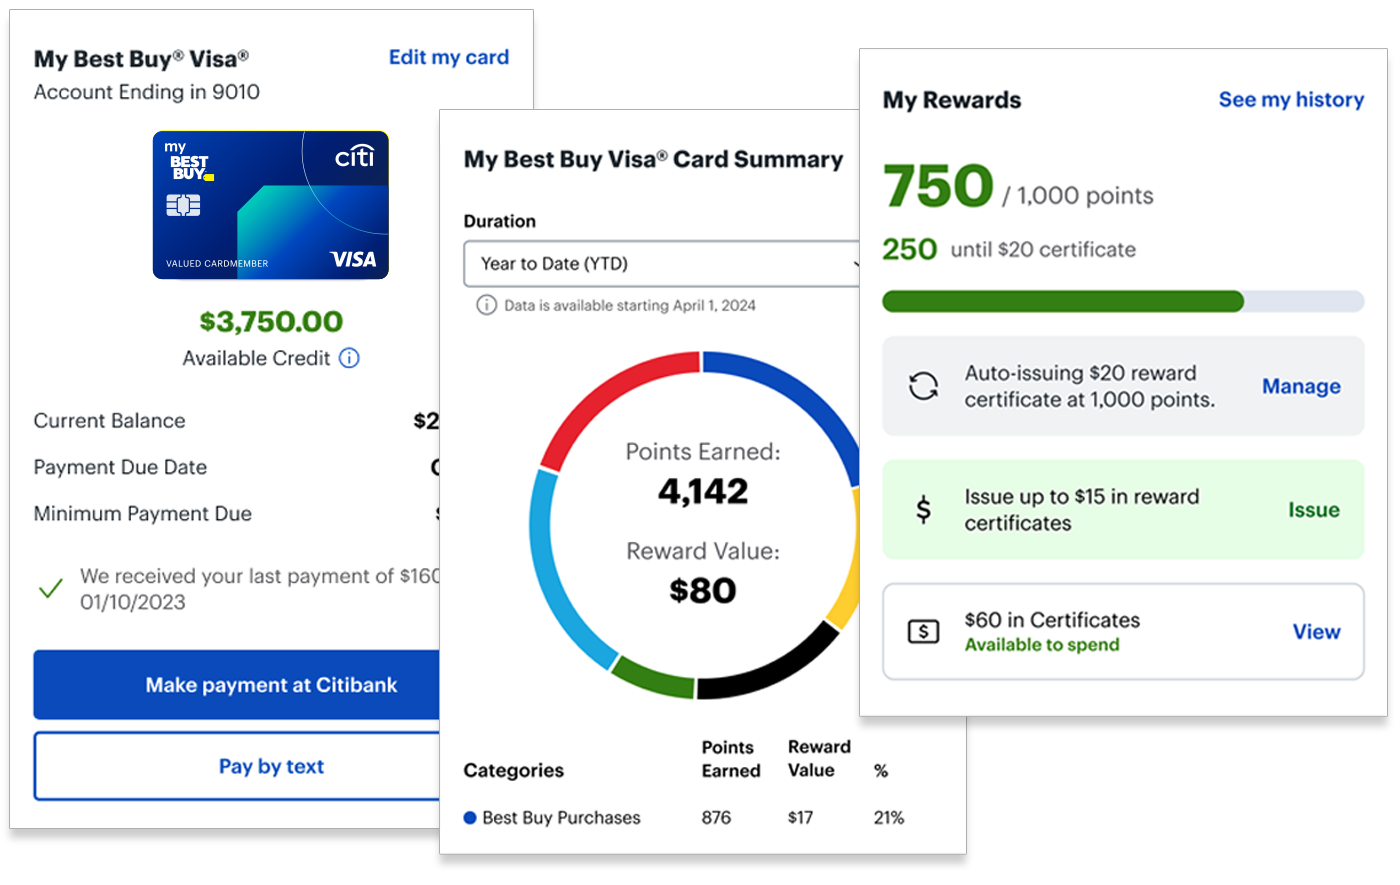
Another edge case that catches people off guard: the My Best Buy membership tiers are separate from the credit card rewards, but they interact in ways that aren't obvious. If you're an Eligible Member (spend $500 annually on any payment method), you get free shipping and early access to sales. Combine that with the credit card's 5 percent rewards, and you're stacking benefits. But if you use the card and still don't hit $500 in total spend, you're paying interest on revolving balances without any of the membership perks. That's a negative expected value situation that happens more often than you'd think. The mobile app for managing your account is functional but not great. Reward tracking is buried under multiple menus, and the transaction history only goes back 18 months unless you download statements manually. I recommend exporting your quarterly summaries right after each statement closes — it takes about four minutes and saves you from a headache when tax season rolls around and you need to reconcile everything. Customer service is where the program really shows its cracks. Call wait times routinely exceed 45 minutes during peak shopping seasons. The automated system routes you through four different menus before you reach a human, and agents often don't have visibility into cross-account issues. I once spent 73 minutes on hold trying to resolve a discrepancy where a $200 reward credit hadn't posted after a qualifying purchase. The agent who finally helped me could only reverse and re-issue the credit, which took another five business days. Had I just opened a dispute through the online portal instead, it would have been resolved in about 48 hours with automated confirmation.
Get the Full Details
For people who do make this card work, the practical strategy is simple: use it exclusively for categories that aren't excluded, pay the balance in full every month to avoid the 26.99 percent variable APR, and time your purchases around promotion periods. The card is basically a cash-back tool with a loyalty lock-in — you're trading shopping at other retailers for slightly higher returns at Best Buy. If you already shop there regularly for electronics and appliances, the math can work. If you're only considering it because of the advertised percentages, stop and calculate your annual spend first. The business version follows the same structure but adds purchase protection and extended warranty benefits that individual consumers don't get. If you run a small operation and make regular equipment purchases, the business card's expense reporting tools alone might justify the switch. Otherwise, the personal cards are sufficient and simpler to manage. One final note on credit impact: opening this card typically drops your score by five to twelve points initially, depending on your existing credit profile. The average FICO change is around eight points. If you have a thin file or are close to a mortgage approval threshold, the timing matters more than the reward rates ever will. I've seen people delay applications specifically to protect their debt-to-income ratios during homebuying windows. It's a detail most reward calculators don't factor in, but it can be the difference between closing on a house at 6.5 percent and 7.25 percent.