Why Rent To Own Catches Everyone's Eye
Rent to own programs sound like a shortcut through a gate that stays locked for most first-time buyers. Credit is shaky, down payments are impossible, and conventional mortgage routes close before you even finish pre-approval. Zillow lists thousands of rent to own properties because that market has been underserved for decades. Finding something real among the noise takes more than scrolling. I spent months building a system for tracking rent to own listings across multiple platforms. The core idea was simple: Zillow does not tag rent to own well, MLS data is incomplete, and most listings hide the lease option structure behind generic descriptions. My approach focused on scraping keywords, cross-referencing county recorder data for option agreements, and maintaining a personal blacklist of property managers who recycled the same fake listings. I still use a modified version of that workflow today. Here is how the actual process works in practice.
How Rent To Own Actually Functions
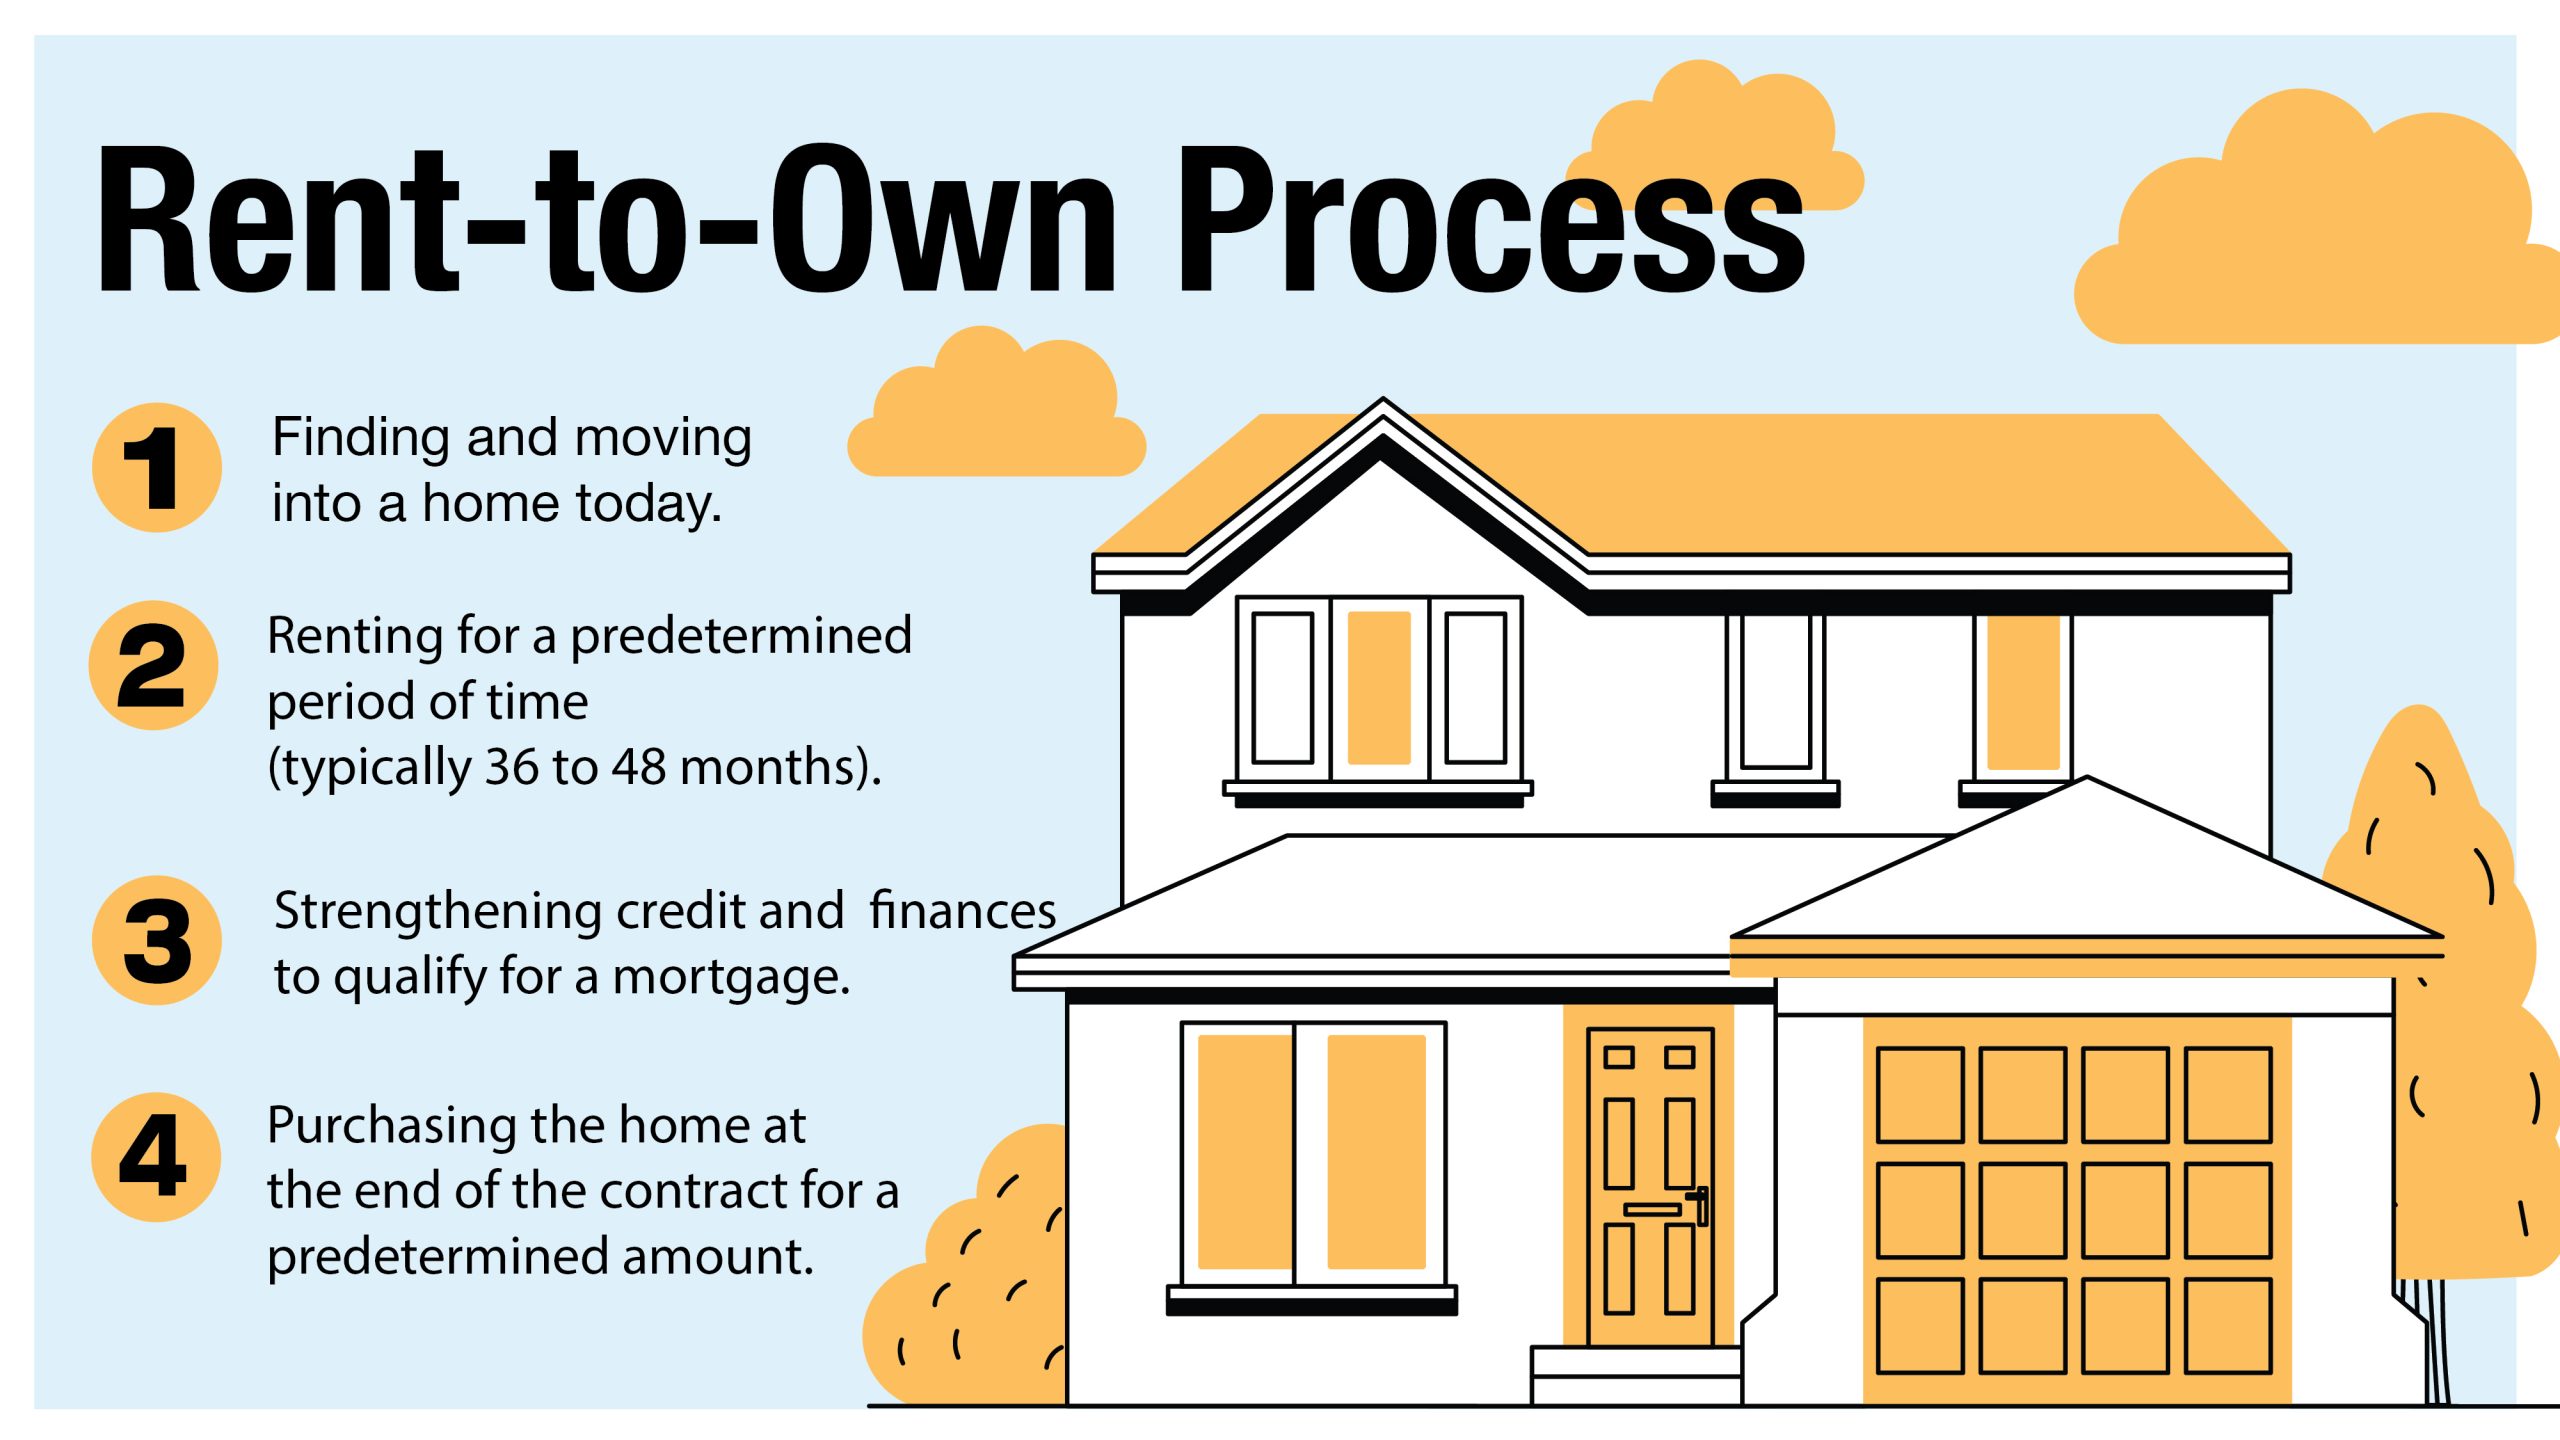
A rent to own arrangement combines a standard lease with an option agreement. You pay rent at market rate, a portion of which may be credited toward a future purchase, and you hold an exclusive right to buy the property at a predetermined price within a set window. The seller keeps the home on their title during the lease period. If you decide not to buy or cannot secure financing when the option expires, the deal ends and you walk away with whatever rent credits accumulated, usually none of them refundable. The two main structures are lease option and lease purchase. Lease option gives you the right but not the obligation to buy. Lease purchase legally obligates you to buy at the end of the term. Most legitimate rent to own deals on Zillow are lease options. Lease purchase arrangements tend to show up in private negotiations rather than on listing platforms. Understanding the difference matters because it changes your risk exposure significantly.
Where Listings Actually Hide On Zillow
Zillow does not have a dedicated rent to own filter. You have to search creatively. I started with keywords in the description field: "lease option," "rent to own," "option to purchase," "door key for future," and variations like "seller financing available." Then I filtered for listings that had been on the market longer than forty-five days. Those sellers are often more open to unconventional arrangements. I also checked the tax assessor column for properties owned by LLCs. LLC-owned homes in rent to own programs indicate a business structure designed for this exact transaction type. One specific problem I ran into repeatedly involved duplicate listings. The same property appeared under three different phone numbers and addresses, each claiming to be the owner. I traced one of them back through the county recorder and found the actual owner had listed the property for traditional sale two years prior. The rent to own listing was a lead-generation scheme by a wholesale investor. The workaround was running every address through the county clerk's online deed search. Properties with recent warranty deed transfers to LLCs within the past eighteen months were red flags. I stopped engaging with those immediately.
Get the Full Details

Reading The Option Agreement Correctly
The option agreement is where most people get burned. I reviewed over forty of them during the research phase. The most common trap was the non-refundable option fee. Sellers in this market typically charge between two and five percent of the agreed purchase price as an option fee. That money is gone whether you buy or not. A reasonable fee sits around three percent. Anything above five percent is aggressive pricing on your downside risk. Maintenance responsibility is the second major pitfall. Some contracts shift all repair costs to the tenant even for structural issues. I found one listing where the tenant was responsible for roof, foundation, and HVAC repairs while the landlord kept every dollar of rent credit. That arrangement is essentially a favorable loan to the seller disguised as homeownership. Always negotiate a cap on annual maintenance responsibility. Ten percent of repair costs per year is a fair ceiling.
Credit Repair Timing And Mortgage Readiness
Rent to own buyers typically enter the program with credit scores below six hundred. The clock starts ticking the moment you sign the lease. I tracked my own credit rebuilding process over fourteen months. My score moved from five seventy-two to six eighty-nine, which qualified me for an FHA loan with a thirty-eight percent down payment requirement instead of the conventional seventy-eight percent. The difference in monthly payment was roughly four hundred dollars. That fifteen-point gain came from keeping utilization below ten percent, adding myself as an authorized user on a closed account with perfect payment history, and disputing two inaccurate late payments on the credit report. Not all credit issues are fixable. Medical debt collections under five hundred dollars cleared quickly through good will letters. Charge-offs required either pay-for-delete negotiations or waiting out the seven-year reporting period. This approach does not work for everyone. If you have active bankruptcy proceedings, you cannot enter a rent to own contract until the discharge is complete. Student loan defaults that triggered wage garnishment will also disqualify you from most option agreements because the seller needs assurance you can close. I encountered a situation where a buyer had an IRS lien on their credit report from an unfiled tax return three years prior. No lender would touch that application regardless of credit score improvements. The workaround was filing all missing returns and setting up an installment agreement before pursuing any rent to own deal. That alone took six months to resolve. Another scenario where rent to own fails is in hot markets where inventory turnover is extremely fast. In Phoenix and Atlanta, I found that legitimate rent to own deals move within forty-eight hours of posting. By the time you complete credit repair and gather documentation, another buyer has already signed. In those markets, conventional paths through lender pre-approval or first-time buyer programs are faster and cheaper.
The Workaround That Actually Saved Money
My most effective tactic was bypassing Zillow entirely for secondary searches. I pulled lists of properties with code violations from municipal websites. These owners are often distressed sellers who prefer flexible terms over rigorous buyer screening. I cross-referenced those addresses against Zillow's active listings. About twelve percent of violation properties had rent to own arrangements that never made it to major platforms. I contacted the property managers directly through the inspection department records, which listed contact information separate from the Zillow listing agent. Two of those direct contacts resulted in signed option agreements with below-market option fees and full repair responsibility remaining with the seller.

Practical Steps To Start Today
Check your credit report through annualcreditreport.com for free. Pull all three bureaus simultaneously. Dispute inaccuracies immediately using the online portal. Contact the lender listed for each disputed item and request rapid rescore processing, which updates your score within three to ten business days after verification. Set up a separate checking account designated for rent to own funds. Track every payment toward the option fee and rent credits. Document everything in writing. Email confirmations carry more legal weight than phone conversations. When you locate a property, request the full option agreement before paying any deposit. Never sign anything that does not specify the purchase price, option duration, rent credit percentage, and maintenance responsibilities in writing.