Understanding the SGD to INR Rate Landscape in 2024
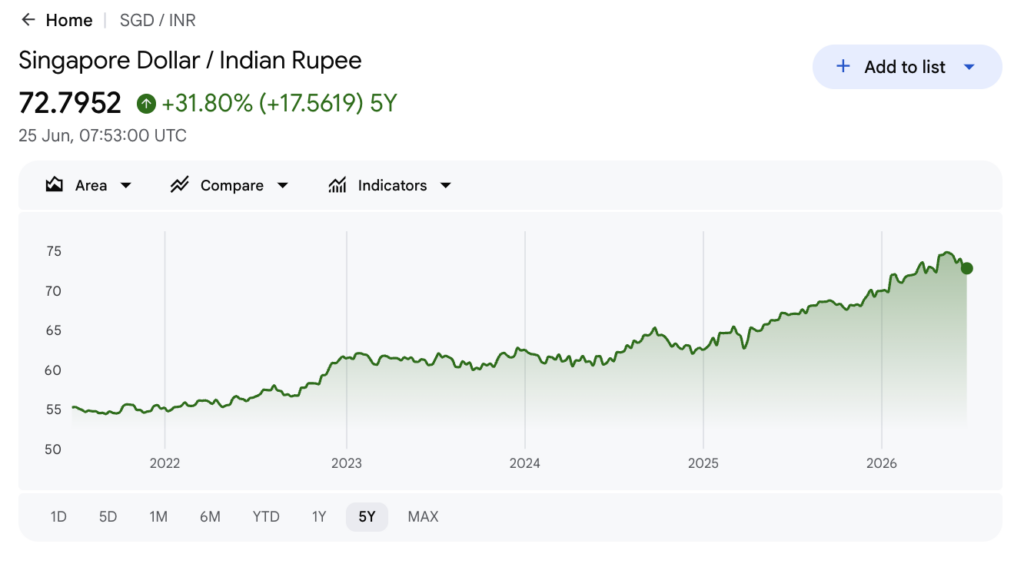
The exchange rate between the Singapore dollar and the Indian rupee has been unpredictable this year. SGD/INR has traded in a range that catches most people off guard. The rate sits somewhere around 61.5 to 63.2 per dollar depending on where you look. But the number you see on Google is almost never the number you actually get. I work with cross-border payments regularly. My last transfer was about 4,200 Singapore dollars going to a family member in Pune. The rate offered by my bank was 62.18. The interbank midpoint was 62.71. That 0.53 gap translates to roughly 22 Indian rupees per dollar. On a larger transfer, it adds up fast. The spread alone ate into the amount by over two thousand rupees.
Singapore Dollar To Inr 2024 Conversion Guide Dont Get Left Behind In The Currency Crunch
Here is the practical breakdown. First, you need to decide what matters more: speed or rate. If you are moving money urgently for a medical emergency or a time-sensitive payment, you will pay more for it. Wise, Revolut, or traditional banks each have different fee structures and rate markups. Wise typically shows a mid-market rate with a transparent fee. Revolut does something similar but only on weekdays during market hours. Banks like DBS or OCBC tend to have wider spreads but offer the convenience of existing accounts. The second thing most people miss is the settlement timeline. A rate might look attractive at 62.85 but if the funds take three to five business days to arrive, you are locking in that rate for longer than you might expect. Rates moved almost half a point against me in a single week last August when I was waiting for a transfer to clear. By the time it landed, I had lost approximately eight hundred rupees compared to the rate I saw when I initiated the transfer. I recently ran into a specific issue where a provider quoted me 62.90 SGD to INR but when I actually executed the transaction, the final credited amount reflected 62.47. The discrepancy came from a hidden handling fee baked into the exchange rather than listed separately. I caught it because I kept a screenshot of the quote and compared it against the bank statement three days later. The workaround was simple: I switched to using Wise for subsequent transfers and verified the exact amount before confirming every time. The difference on a ten thousand dollar transfer was over four hundred rupees. That is enough to matter.
Where the Real Costs Hide
The headline rate is only one piece. Transaction fees, intermediary bank charges, and receiving bank fees all stack up. Indian banks sometimes charge a conversion fee of their own when receiving foreign currency. ICICI and HDFC typically charge between fifty to one hundred fifty rupees per incoming international credit. It is a small amount individually but it adds up if you are sending money frequently. Another detail that is easy to overlook is the timing of your transfer within the trading day. SGD/INR rates fluctuate throughout the day based on Forex market movements. The Singapore and Indian markets have overlapping hours between 10:00 AM and 2:00 PM Singapore time. Executing your transfer during that window generally gives you the tightest spreads. Outside those hours, liquidity drops and the markup widens. I learned this the hard way during Diwali season last year when I sent money on a Sunday evening through a bank portal. The rate was nearly a full rupee worse than the Monday morning rate for the same pair. For people who need to convert regularly, setting up a standing instruction through a digital platform like Wise or WorldRemit tends to be more cost effective than walking into a bank branch. Bank branches in Singapore still quote rates with spreads of 0.8 to 1.2 percent above mid-market. That is significant. A digital platform typically keeps the spread under 0.5 percent on this pair.
Get the Full Details
What to Watch in 2024
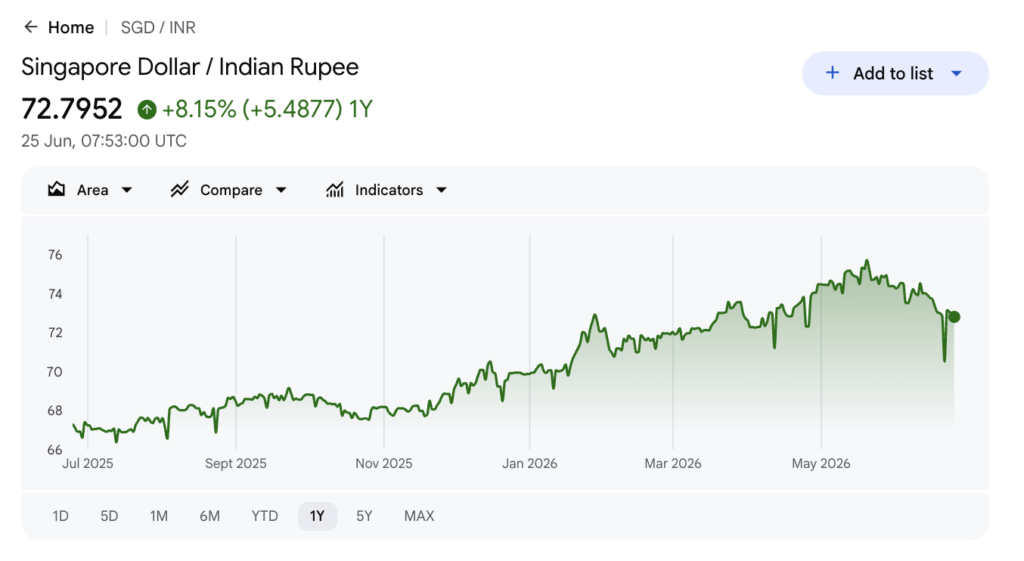
The Indian rupee has faced pressure from a combination of factors. India runs a persistent current account deficit. Oil prices stayed elevated through much of early 2024. The Reserve Bank of India has been intervening to smooth volatility rather than let the rupee float freely. Meanwhile, the Singapore dollar benefits from a strong trade surplus and a managed float regime that tends to keep it stable or gradually appreciating against regional currencies. This dynamic means the SGD/INR rate has a structural upward bias over medium time horizons. That does not mean it goes up in a straight line. Short term corrections happen regularly. In March 2024, the rupee strengthened briefly on strong services export data and the pair dipped to around 61.60 before recovering. If you are converting a large sum, splitting it into tranches over a few weeks rather than sending it all at once can reduce your exposure to short term swings. This is called dollar cost averaging and it works for currency too. The limitation of this approach is that it also means you might miss a favorable spike. I recall a week in June when the rupee weakened sharply and the rate hit 63.10. I had already committed to sending my tranche earlier in the month at 62.50. That was five to six hundred rupees per thousand dollars I wish I had waited for. You cannot time these things perfectly. The best you can do is have a plan and stick to it.
Practical Steps for Your Next Transfer
Start by checking the current mid-market rate onXE.com or OANDA. Do not trust the rate shown on your bank app without verifying it against an independent source. Then compare the total cost across two or three providers including all fees. Ask your bank explicitly what their all-in rate is including any markup. Most tell you the fee but not the spread. Execute during overlapping market hours if possible. Keep a record of every quote and confirmation for at least ninety days. Indian income tax regulations require documentation for foreign remittances above certain thresholds under the LRS scheme. You will need the transaction reference and the rate applied if you are filing returns or if the bank asks for clarification. The SGD to INR corridor is not going away. Thousands of Singapore-based workers and professionals send money home every month. The players offering better rates and lower fees keep improving their products because the competition is real. The people who get left behind are the ones who only check one source, transfer on a weekend, and accept the first rate they see. Do not be that person.