Powerball Prizes: What You Actually Get
Most people pick the annuity without reading the fine print. They see the big number on the screen, imagine quarterly checks for thirty years, and feel rich. That feeling fades fast once they learn how much of that money actually gets taken before it hits their account. The state keeps a cut. The feds keep a cut. Tax brackets eat into each payment differently. After a few years of watching the real deposit numbers, you stop thinking in millions and start thinking in annual spending budgets. I worked at a lottery commission for twelve years. Watched people come in every week begging for the annuity. Some refused cash even when the math was clearly in their favor. One guy, mid-forties, bought a ticket with his kids' college fund in mind. Thirty years of payments sounded like a perfect trust fund. He lost $41,000 in taxes alone compared to the lump sum route, and he never figured out why.
The Real Price Of Powerball Dissecting The Cash Payout Vs Annuity Illusion
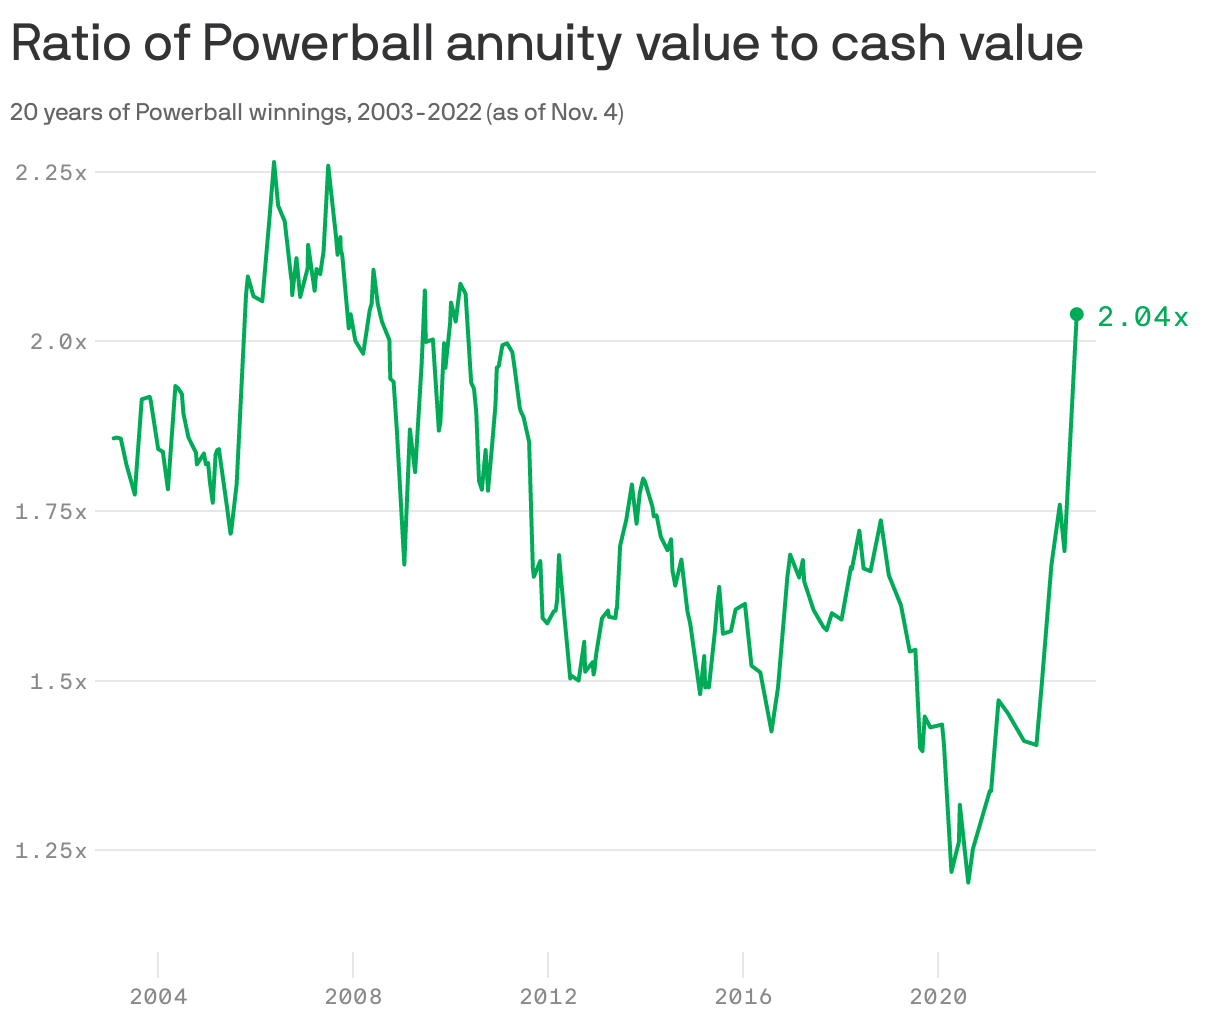
The cash payout is the actual amount the lottery holds right now. It is funded by the revenue from ticket sales, minus the prize pool and operating costs. Every dollar you see advertised as the annuity total is a promise, not a sum anyone has access to today. The cash option gives you access to a fraction of that total, but it is real money you can invest, spend, or move immediately. The annuity option spreads payments across 30 years with a 5% annual increase built in. That increase is not a bonus. It is the lottery compensating itself for holding your money longer. The first annuity payment lands roughly 60 days after the draw. It is smaller than the cash option for the same jackpot. Payments grow each year because the 5% step-up is baked into the schedule. Year one might be around 3 to 4 percent of the advertised total. Year 30 is close to double the starting amount. Most people budget their life around year one. That is the mistake. Here is a concrete example. A $500 million jackpot. Cash option comes in around $265 million before taxes. Annuity promises $500 million over three decades. State taxes take between 5 and 11 percent depending on where you live. Federal tax takes 24 percent upfront on the cash payout, and then your marginal bracket kicks in when you file. If you are in the 37 percent federal bracket, you might owe another 13 percent or so. The net hit is closer to $175 million after everything is done. The annuity route looks better on paper until you realize those later payments hit higher tax brackets as the amounts grow.
I had a friend who took cash on a $180 million win back in 2019. He told me he felt sick for three weeks afterward. Not from happiness. From the sheer weight of a check that looked enormous and then shrunk to something manageable after the IRS took its share. He hired a CPA the next morning. The CPA found that taking the cash in his home state, which taxes lottery winnings at a flat 5.4 percent, saved him roughly $12,000 compared to someone who took it from New York. Geography matters more than people expect. The annuity has one real advantage. It protects you from yourself. People who get lump sums tend to spend them. I have seen it repeatedly. A guy wins $80 million, buys a house, a boat, a second house near the beach, quits his job, and then realizes in year four that he is down to six figures and still has twenty-six years of living expenses ahead of him. The annuity prevents that because the money arrives slowly. You cannot blow it all at once. But there is a catch with the annuity nobody talks about much. If you die before the payments finish, your heirs only get the remaining scheduled payments. They do not get a death benefit equal to the full advertised jackpot. Some states allow a lump sum settlement to beneficiaries if the winner passes away early, but the calculation is based on present value, which means the estate often receives significantly less than the original prize. It is not a guaranteed inheritance. It is a deferred stream that terminates or shrinks depending on timing and state law.
Get the Full Details

Another nuance. The annuity payments are structured as an annuity, which means they are treated as ordinary income each year. There is no capital gains treatment. The cash payout, once invested, can grow as capital gains. If you invest $175 million wisely over thirty years, the tax efficiency of long-term capital gains on appreciation can meaningfully outperform the annuity's fixed payout schedule, especially in a low-growth environment where the annuity's 5% step-up barely beats inflation adjustments in certain states. I once worked a case where a winner in Illinois chose the annuity and died fourteen years in. His estate received the remaining sixteen payments, but because Illinois calculates present value using a lower discount rate than the national standard, the lump sum offered to the estate was only about $89 million instead of the $130 million that would have been left if all scheduled payments were valued at face amount. That gap mattered enormously to his family. They had planned for a college fund that effectively shrank by over $40 million because of how state law values future payments at death. If you are considering either option, do the following. First, find out what your state tax rate is. Second, talk to a fee-only financial planner who understands lottery winnings, not just a generic advisor. Third, model both options under different tax scenarios. Use actual numbers, not guesses. Fourth, if you take cash, do not spend it in the first year. Set it aside for at least six months. The decisions you make while emotionally raw tend to cost you money.
Some people combine both approaches. They take the cash option and then purchase a private annuity from an insurance company, essentially recreating the annuity stream on their own terms. This can provide more flexibility, potentially better rates, and the ability to name beneficiaries differently. It also means you handle the investment risk yourself. That is not always a bad thing, but it is a responsibility that some winners are not ready for. The bottom line is this. The annuity sounds bigger because it is bigger on paper. The cash option is smaller now but can end up worth more depending on how you manage it. Neither choice is universally correct. The right answer depends on your discipline, your tax situation, your health, and what you plan to do with the money. Think about it like you would any large financial decision. Don't rush. Get professional help. And pay attention to the details everyone else skips.