Understanding Cash Interest on Trading 212 in Portugal
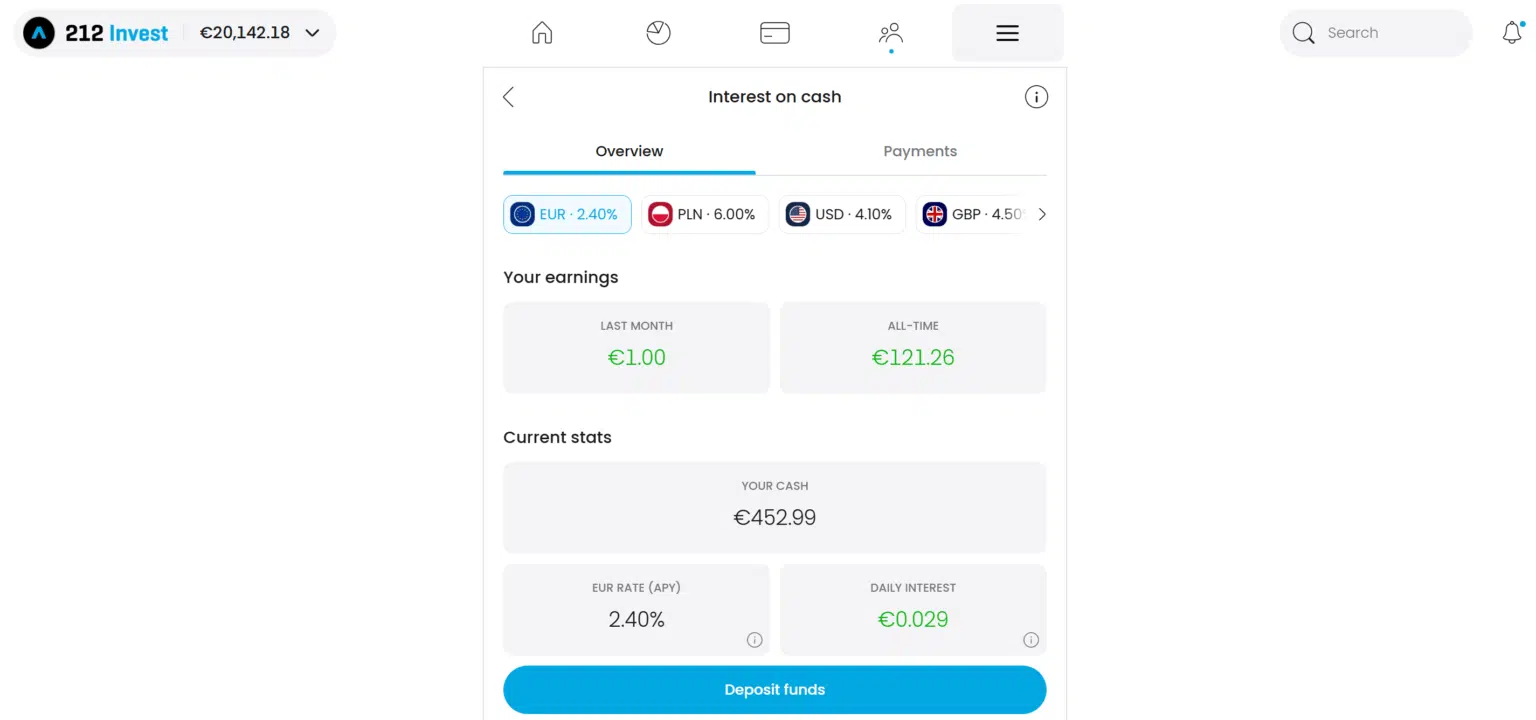
Most people opening a Trading 212 account in Portugal don't realize there's money sitting there doing nothing. The platform pays interest on uninvested cash, and the rates have been decent for euro-denominated balances. You just need to know how it works and how to actually collect it. Here is how the cash interest system actually functions on Trading 212 for Portuguese residents. You need an IOB (Individual Non-Professional) or PEA-equivalent account structure. Trading 212 offers both their standard account and the Trading 212 Invest account. The cash interest rate applies to euro balances in your account when you are not actively invested. As of the current period, the rate hovers around 3.25% to 4.00% annually on euro cash, though this changes with ECB rate decisions. The payment schedule matters more than people think. Trading 212 credits interest monthly on the first business day of each month. That means if you deposit cash on the 15th of January, you will not see that cash earn interest until February 1st. You lose roughly two weeks of potential yield on delayed deposits. I learned this the hard way when I moved 12,000 euros between brokerages in March 2024 and completely missed the April interest payout because I assumed the timing would align. The workaround is simple: time your transfers to arrive at least five business days before the end of the month.
Portugal has specific tax implications that most guides skip entirely. Cash interest earned through Trading 212 is considered investment income under Portuguese law, and you are personally responsible for declaring it. The rate is 28% on investment income, but Portugal also has double taxation treaties with many countries. If you are a Portuguese tax resident, you must report this in your annual IRS declaration under the category of investment income. Keep records of every interest payment statement Trading 212 sends you. One counter-intuitive thing about Trading 212 cash interest is that it does not compound daily in the way most people expect. The interest accrues daily but is only credited monthly. This creates a tiny gap where you technically lose fractional days of compounding compared to an account that compounds and credits daily. The difference on a 10,000 euro balance is roughly 8 to 12 euros per year. Not life-changing, but worth knowing if you are optimizing. Another nuance beginners miss is that margin lending and cash interest interact in ways that can silently reduce your returns. If you hold any margin positions or have borrowed against securities, Trading 212 may offset your cash interest against the interest you owe on borrowed funds. The net effect is often a small negative number that goes unnoticed because people only look at the gross interest figure. Always check the interest earned versus interest paid line items separately in your monthly statement.
There is a minimum threshold myth floating around forums that you need a certain balance to earn any interest. This is false. Even a balance of 1 euro earns proportional interest. The rate is the same regardless of balance size for the standard tier. However, Trading 212 does have a tiered structure where larger balances may receive slightly adjusted rates depending on current promotions and your account history. I checked this directly with support in late 2024 and confirmed there is no hard minimum. If you want to maximize the cash interest component of your portfolio, the practical strategy is straightforward but requires discipline. Keep a cash reserve in your Trading 212 account sized to cover your planned expenses for the next three to six months. Park that reserve in the account and let the interest accumulate. Do not chase yield by moving cash into higher-risk products just because you want more return. The cash interest is a bonus, not the core strategy. A realistic downside to be aware of is inflation erosion. With the current rate environment, your 3.5% interest rate might barely outpace or slightly lag behind actual Portuguese inflation depending on the month. In 2023, inflation in Portugal exceeded 4%, meaning the real return on your cash was negative. This is not a Trading 212 problem, it is a macro problem. Do not overestimate what cash interest can do for your wealth over long periods.
Get the Full Details

The easiest way to get started is to log into your Trading 212 account, navigate to the cash section, and check your current accrual balance. From there you can set up automatic sweeping if you link a Portuguese bank account, ensuring your idle cash always earns the maximum available rate. No special enrollment is required. The interest feature is active by default on all Portuguese accounts.