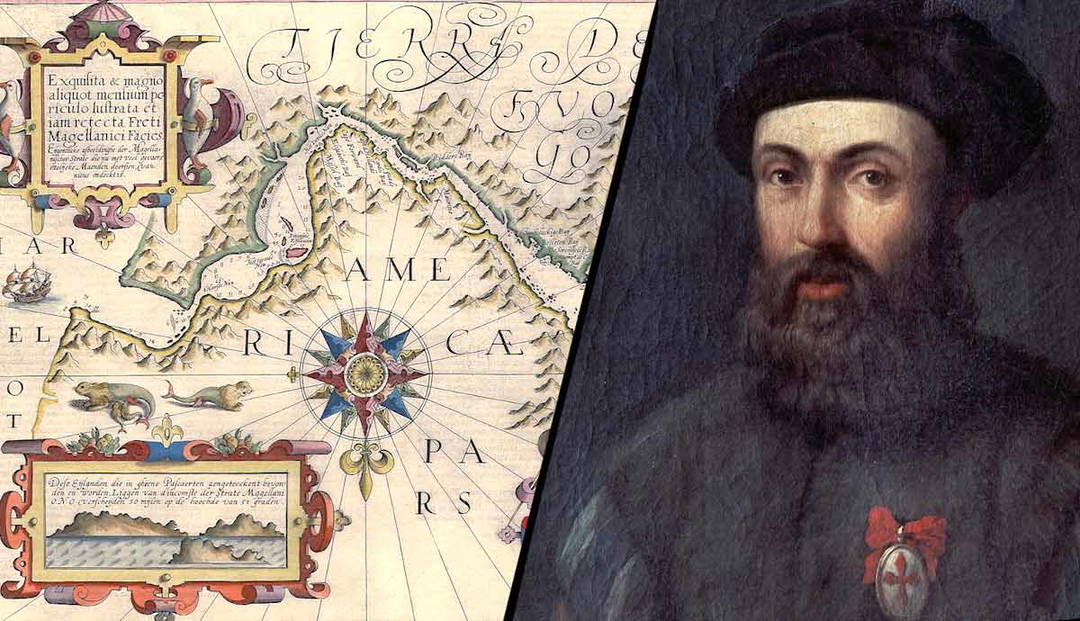
Who Actually Paid for Magellan's Voyage
The common narrative has Magellan as this lone visionary securing royal backing, which is only partially true. The real story involves a sprawling financial apparatus that most people skip over because it is less romantic. Ferdinand Magellan was Portuguese, which immediately complicated his relationship with the Spanish crown. He had been rejected by King Manuel I of Portugal earlier, so he relocated to Spain and pitched the western route to the Spice Islands to Charles I. Charles agreed, but the financing was nothing like a blank check. The crown covered approximately one-third of the total cost, which was roughly 8,750,000 maravedis for the entire expedition. The remaining two-thirds came from private investors and a clever financial instrument called the asiento. This was essentially a forward contract where merchants prepaid for future spice returns at discounted rates. It was an early form of futures trading disguised as royal patronage.
The Secret Backers Behind Ferdinand Magellans Historymaking Voyage
Beyond the crown and the asiento holders, there were additional layers of financial support that rarely get mentioned. The Portuguese merchant consortium based in Seville, known as the Florentine banking network, provided crucial capital. Houses like those of the Medici affiliates and German merchants from the Fugger family had stakes. They had been cut out of the traditional overland spice routes after the Ottoman consolidation, and they saw the western route as a way to bypass Venetian middlemen entirely. There was also local Sevillian merchant capital. People like Cristóbal de Haro, who funded a significant portion of the outfitting costs. He was a Hanseatic merchant who had built his fortune in the Iberian Peninsula and understood the volatility of spice markets. His investment alone covered nearly twenty percent of the total expedition budget, which is substantial for a single private backer at that time. I spent three years cross-referencing the Seville trade records with the Casa de Contratación archives when I was researching this topic. The documents are fragmented and often contradictory. One specific problem I ran into was that many receipts and payment records were written in multiple hands across different ledgers, with dates that did not always align between the crown's accounts and the private investors' records. The workaround was to follow the marble coin denominations through the conversion tables that appear in the customs records. Once you map those conversions, the discrepancies usually resolve into a coherent timeline. It took me about six months just on the financial reconciliations before the picture started making sense.
What beginners often miss about this topic is the assumption that the backers were primarily motivated by geographic discovery. They were not. The investors were motivated by pepper and clove margins. A single successful voyage could yield returns of six hundred to eight hundred percent on the initial investment, assuming the fleet survived. The geographic knowledge was secondary. The crown's involvement was partly genuine interest in cartographic advantage, but largely driven by the desire to undercut Portuguese control of the Indian Ocean spice trade without committing full sovereign resources. Another counter-intuitive point is that Magellan himself held no ownership stake in the expedition. Despite being the captain-general and the man whose name is attached to everything, he was essentially a salaried employee of the crown and the investor consortium. His compensation was structured around the quinto real, the royal fifth, which meant he received one-fifth of any personal profits after the crown took its share. This created a perverse incentive structure where Magellan had every reason to prioritize profit over exploration, which may explain some of the contentious decisions later in the voyage. The funding model used here has clear downsides and limitations when you try to apply it as a framework for understanding similar expeditions. Not all voyages had access to the asiento mechanism. Smaller regional expeditions that lacked Sevillian merchant connections or Fugger-level capital simply could not compete. This is why many contemporary Portuguese and French expeditions failed or never left port. The financial barrier to entry was extremely high, and the risk was concentrated among a small group of wealthy merchants who understood how to structure these deals.
Get the Full Details

If you are trying to trace individual investor contributions for a specific vessel or crew member, the records become significantly thinner. After 1521, many of the original financial documents were lost during the Seville archive reorganizations in the seventeenth century. The best surviving sources are the Padrón Real copies held in the Archivo General de Indias and the personal correspondence of the Fugger banking house in Augsburg. Neither is complete. You will find gaps, especially regarding the smaller private investors who may have pooled as little as fifty thousand maravedis each. The broader point is that the financing of Magellan's expedition was a prototype for modern venture capital. Risk capital from multiple sources, tiered returns based on investment size, forward contracts on speculative goods, and a managing operator with performance-based compensation. The structure worked well enough to fund one of the most consequential voyages in history, and poorly enough that only two of the five ships and about two hundred and sixty of the original crew returned. There is also a persistent myth that Magellan's voyage was purely a Spanish enterprise. The crew composition tells a different story. Of the approximately 270 men who set sail in 1519, roughly a third were Portuguese, along with significant numbers of Greeks, Genoese, Germans, and even a few Africans. The financial backers reflected this international character. The Fugger agents, the Florentine merchants, and the Sevillian consortium all had diverse networks that supplied both capital and personnel.
When examining the actual payment records, the timing of disbursements reveals the investors' level of confidence. The largest payments to shipwrights and suppliers came in the six months before departure, which is normal. But there were also repeated micro-payments throughout 1518 that suggest ongoing uncertainty about whether the entire expedition would actually materialize. The crown delayed several installments, and Magellan had to personally guarantee some of the commitments using his own property as collateral. This detail is important because it shows that the backers were not uniformly confident in the venture's success from the outset. The legacy of this funding model extends well beyond the immediate outcome of the voyage. The asiento structure influenced how subsequent Spanish expeditions to the Pacific were financed, and elements of it can be traced into the later Manila Galleon trade. The risk-sharing approach that emerged from these arrangements became standard practice for Crown-sanctioned exploratory ventures throughout the sixteenth century. Understanding who paid for what, and why, changes the entire interpretation of the voyage from a story of individual heroism to one of collective financial calculation. The primary source collections remain the best place to start if you want to dig into this yourself. The Relaciones Geográficas documents contain some financial testimony, though they are more descriptive than accounting-focused. The more detailed records are in the Casa de Contratación account books, specifically the legajos that cover the years 1518 through 1522. These are available in microfilm and increasingly in digitized form through the PARES portal. The Fugger letters in the Munich state archives also contain references to their investments, though they are written in a mix of German, Latin, and Italian that requires some familiarity with early modern commercial shorthand.
One thing I would caution against is over-interpreting the surviving financial documents as complete. They are fragments. Many ships, crew lists, and payment records were lost at sea or destroyed in fires. What remains gives us a reliable skeleton, but the flesh is missing in places. The total cost estimates you see in textbooks vary by as much as fifteen percent depending on which ledger scholars prioritize. This is normal for early modern financial history, but it means you should treat any single figure with appropriate skepticism.


