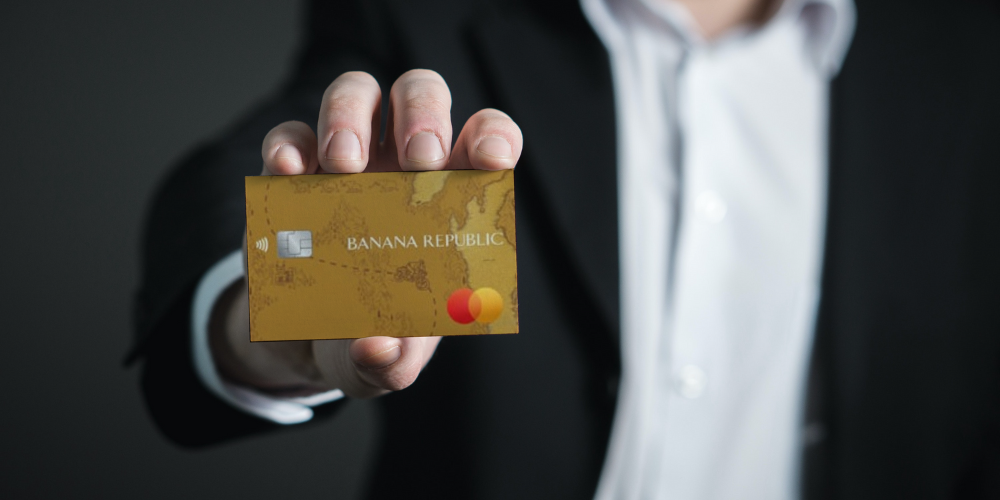
The Banana Republic Credit Card Actually Makes Sense If You Shop There Regularly
I've had the card for about four years now. Most of the people I talk to who open it end up dropping it after six months because they figure out they only shop at Banana Republic once or twice a year. That's fair. But if you actually buy clothes from them, it's one of the more straightforward store cards out there. The main thing that matters is understanding how the rewards structure works and what the perks actually are versus what the marketing materials make them sound like. Let me walk through what you're signing up for.
Unlock Exclusive Perks And Rewards With The Banana Republic Credit Card
You earn 5 percent back on all Banana Republic purchases. It's not points. It's not miles. It's Statement Credits that post directly to your bill. That matters because statement credits don't expire, you can't devalue them by booking flights at the last minute, and they can't be transferred to a program that randomly changes its conversion rate. It's just cash off your balance. Simple. The 15 percent off welcome offer that comes when you first open the card is the biggest number you'll see advertised. I've seen people get excited about that, but here's what nobody tells you - that 15 percent applies to your first purchase only, and it's capped at a certain amount depending on when you signed up. The fine print buried on the approval page will tell you the exact cap. Usually around $50 to $100 in credits, not on the full purchase price. There's also the free shipping on every order and early access to sales. The early access thing sounds nice but honestly it's not worth getting excited about. The sale items that get released early are usually the same ones everyone else already knows about. The real benefit there is just avoiding the worst of the crowd when items start going on sale.
How The Rewards Actually Stack Up
I'll give you the math from my own usage. I spend roughly $800 a year on Banana Republic stuff - shirts, pants, the occasional coat. At 5 percent that's about $40 a year coming back to me. Against the 0 percent APR for the first twelve months on purchases, it's decent if you carry a balance during that window, but you should never do that intentionally. Carrying a balance on any store card is a bad financial move regardless of the intro rate. Here's the thing most people miss: the 5 percent reward has no category limits, no rotating quarters, no activation requirements. You swipe, you get credited. A lot of people get burned by cards that offer higher percentages in rotating categories because they forget to activate them every three months. Banana Republic doesn't play that game. That's both its strength and its limitation. The rate is solid but it only works at one retailer. If you shop at Gap or Old Navy as well, there's no stacking benefit there. The card is Banana Republic only. Some people open it hoping they can use it across the whole Gap Inc. portfolio. They can't. It only posts rewards at Banana Republic and its sub-brands like HillCity.
Get the Full Details

What Happens After The Intro Period
After the twelve-month 0 percent APR window closes, the standard APR kicks in. It's variable and sits somewhere in the mid to high twenties depending on your creditworthiness. This is where the card becomes expensive fast if you're not paying it off every month. I've watched friends use this card during the intro period to finance a big purchase, then lose track of the payoff date and get hit with retroactive interest-like costs because they missed the grace period cut-off. The workaround I'd recommend is setting a calendar reminder for sixty days before the intro period ends. That gives you time to figure out whether you can pay the remaining balance in one shot or if you need to request a balance transfer to a card with a lower ongoing rate. Capital One does allow balance transfers between their cards sometimes, which can be a way to extend favorable terms without leaving the ecosystem.
Sign-Up and Application Process
You apply through the Banana Republic website or at checkout. Capital One handles the issuing. Approval is usually instant if you have decent credit - I got mine approved in under two minutes. If you get a soft pull situation, you'll see a pre-qualified offer first, which doesn't guarantee final approval but gives you a much better idea of your odds. The card is physical and digital. If you want to start using it immediately before the plastic shows up, the digital card in the Capital One app works fine for online purchases and Apple Pay or Google Pay at physical stores. I've used it this way countless times.
Edge Cases and Problems I've Run Into
One issue that caught me off guard: returns. If you return an item you bought with the card, the statement credit reverts to your account, but it doesn't always show up the same day. I had a situation where I returned a jacket two weeks after the credit had already posted as a reward. The system reversed the reward, and I was confused for about three days because my reward balance dropped below what I expected. The fix was just calling customer service and confirming the return had processed. They reconciled it manually within forty-eight hours. Another thing that trips people up - the 15 percent welcome discount doesn't combine with other promotions in the way you'd expect. I once tried using it during a sitewide sale and assumed I'd get both the sale price and the 15 percent off on top. I didn't. The welcome offer applies to your first purchase at regular price or during a promotion, but the discount is calculated on the final price after all other markdowns. So if something is already 50 percent off, your 15 percent comes off the reduced amount, not the original. It still adds up, but the math looks different than you'd guess at first glance.

Whether It's Worth Opening
Here's the honest answer: if you shop Banana Republic more than twice a year, open it. The 5 percent back is genuinely useful and the lack of category headaches means you'll actually use it consistently. If you shop there once a year or less, skip it. The annual fee is zero, which removes the biggest downside, but a card that only works at one store is still a narrow tool. It's also worth noting that applying for this card generates a hard inquiry on your credit report, which drops your score by a few points temporarily. If you're in the middle of applying for a mortgage or another major credit product, wait until after that process closes before applying. The inquiry stays on your report for two years even though the score impact fades after about twelve months. There's no annual fee, no foreign transaction fee, and no minimum reward redemption threshold. You don't need to accumulate points to unlock anything. The rewards post automatically each billing cycle. That's about as low-friction as a rewards card gets, which is maybe the most important thing to understand about this product.