Looking at VW Finance Payment Calculations
Most people I talk to who are trying to figure out their monthly payments on a new Volkswagen end up confused by the different options available. There's a dealer financing route, manufacturer incentives, lease versus buy decisions, and a bunch of numbers that don't always add up the way you'd expect. I've spent years looking at finance structures and payment schedules, and the short version is that you need to understand what you're actually looking at before you sign anything. Volkswagen offers several built-in tools on their website and through their mobile app that let you calculate approximate payments before you walk into a dealership. These aren't perfect - they're estimates based on standard assumptions - but they give you a baseline. The main ones I use are the payment estimator on vw.com and the app's own calculator feature. They ask for your zip code, the model you want, your intended down payment, and whether you're buying or leasing. Here's where most people get tripped up though. Those calculators assume a standard credit tier. If your credit score is below 680 or above 760, the actual rate you get will likely deviate from what the calculator shows. I had a client last year who used the online estimator for a Jetta and it showed him $289 a month. When he actually went to the dealer with his real credit profile, the rate was 5.9 percent instead of the 3.9 percent assumption baked into the tool. That pushed his payment to about $318. Not a dealbreaker, but enough to make him feel blindsided.
What I learned from that is to treat every online payment guide as a best-case scenario starting point. Add roughly five to ten percent to whatever number you see online if your credit isn't excellent. That gives you a more realistic expectation. It also prevents you from falling into the trap of walking into a dealership thinking you've already locked in a number, when really you're starting from scratch. Another thing most people miss is how Volkswagen's incentive structure works month to month. There's often a low APR offer running - sometimes as low as 1.9 percent or 2.9 percent on select models - that sounds great until you realize it's usually paired with requirements like higher down payments, shorter loan terms, or specific trim levels. The payment guide won't always flag which incentives apply to which configurations, so you have to dig into the fine print. I keep a folder of current Volkswagen incentive offers in my browser bookmarks and cross-reference them against whatever the calculator is showing me. It takes maybe three minutes and saves you from walking out of the dealership with a finance package that looks good on paper but costs more than you expected. Let me also say something about leasing versus buying that isn't obvious from the payment calculators. Leases often appear cheaper month to month, but they come with mileage caps, wear-and-tear charges, and you never build equity. If you're driving more than fifteen thousand miles a year - and I can't tell you how many people I've met who assumed they'd stay under that limit and ended up paying over a dollar per mile at the end - a lease can become expensive fast. The payment guide won't warn you about this. It'll just show you the lower monthly number and let you assume that's the whole picture.
Here's a practical workflow I recommend. Run your target vehicle through the VW payment estimator first. Write down the monthly number. Then call three or four dealerships in your area and ask for their current money factor if you're leasing or their current APR if you're financing. Compare those real numbers against the calculator's assumptions. If they're within two points, you're in a reasonable ballpark. If they're three or more points off, you've got leverage - because now you know the dealer's starting rate is worse than what the online tool is projecting, and you can negotiate from that position instead of walking in blind. One edge case worth mentioning involves Trade-In values and how they interact with finance calculations. Dealers often present your trade-in as reducing your down payment, which sounds good on the surface. But if you're financing the difference, you're rolling the trade value into the loan at the dealer's offered rate, not necessarily getting the best value. I've seen people roll in a trade worth two thousand dollars into a loan at six percent when they could have taken that as a straight cash reduction and saved money. The payment calculators don't highlight this distinction because they're designed for simplicity, not optimization. There's also the question of gap insurance. Volkswagen and most lenders will push it hard during the finance process. It costs somewhere between twenty and forty dollars a month depending on the lender, and it covers the difference between what you owe and what the car is worth if it's totaled. The calculators almost never include this in their monthly figures, so your actual out-the-door payment ends up higher than estimated. Factor it in yourself if you're putting down less than twenty percent or if you're financing a longer term like sixty or seventy-two months. Newer cars depreciate fastest in the first two years, and without gap coverage you could end up owing ten thousand dollars on a car that's only worth six.
Get the Full Details
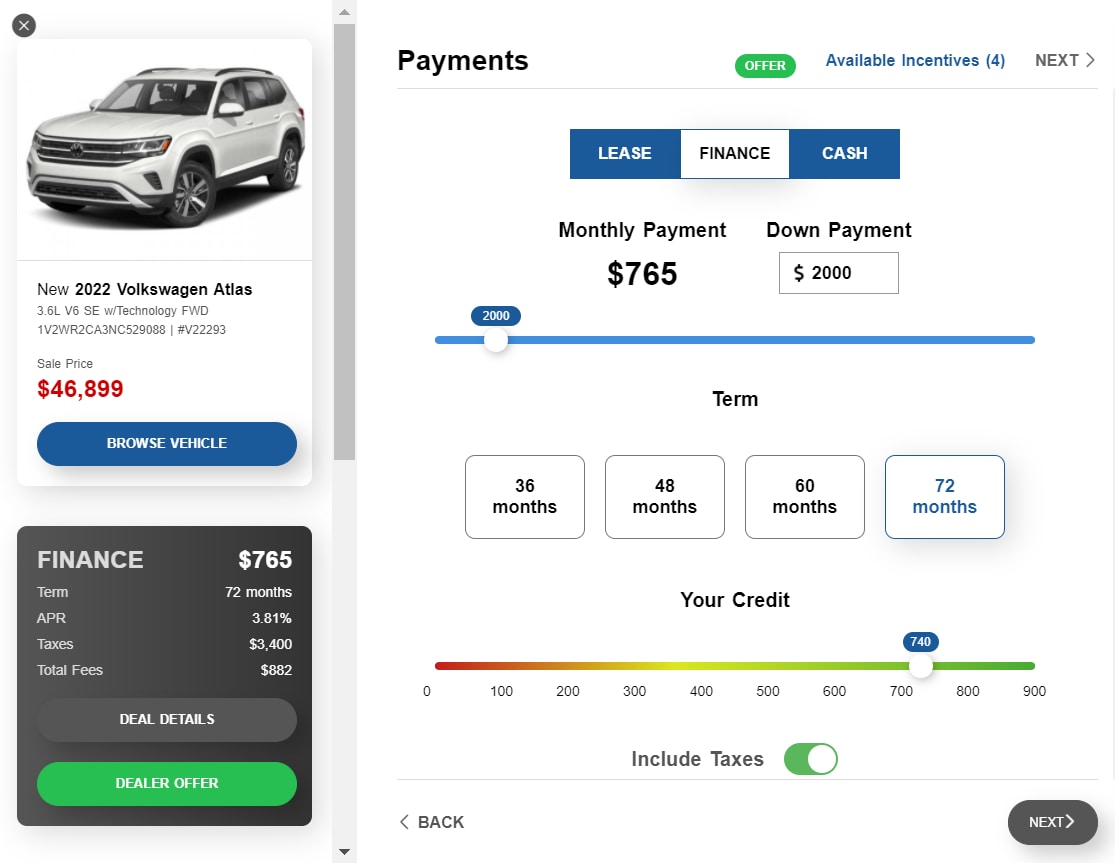
If you want a faster way to run multiple scenarios without going dealership to dealership, I've found that building a simple spreadsheet with the dealer rates you collect is more efficient than relying solely on the online tools. Put in the MSRP, your target trade-in value, the APR or money factor each dealer quoted, and watch how the payment shifts across different terms. You can see at a glance which combination gives you the lowest true cost instead of just the lowest monthly payment. It took me maybe ten minutes to set up after my first attempt, and I've used it on every purchase since. The reality is that Volkswagen's payment guides and calculators are useful for establishing a baseline, but they're not the final word. The actual numbers you'll deal with depend on your credit, the incentives running that month, your trade-in situation, and whether you're being sold gap insurance or other add-ons you may not need. Knowing how to read past the initial estimate and verify the real rates before you sit down at the finance desk makes the difference between feeling like you got a good deal and feeling like you were sold something you didn't fully understand.