What the Fidelity 500 Index Fund Actually Is
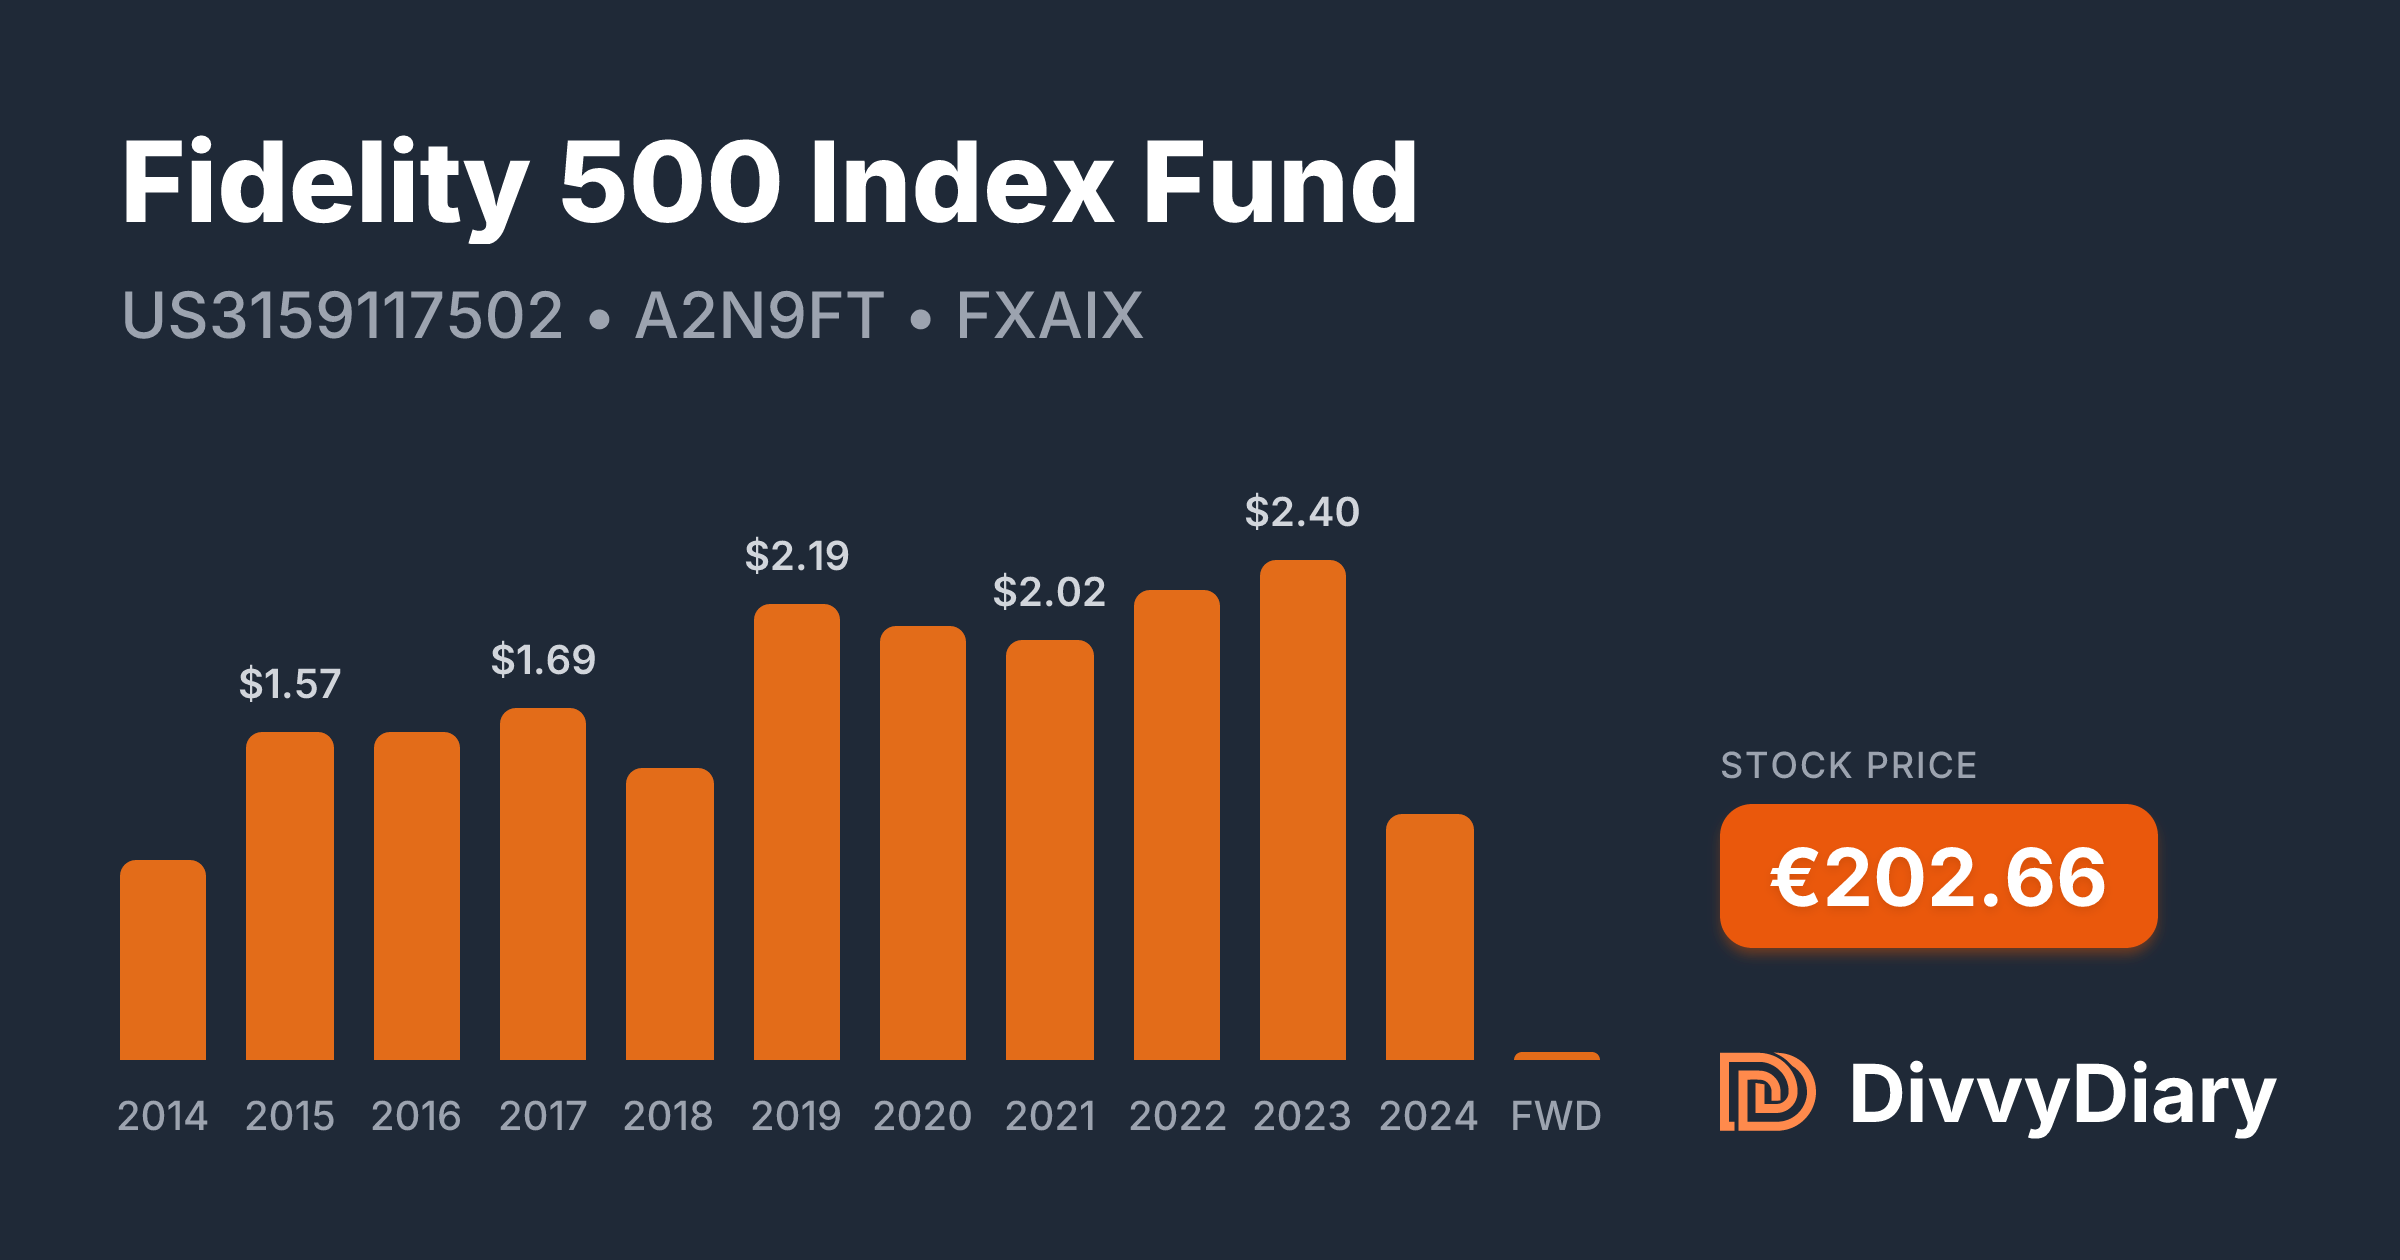
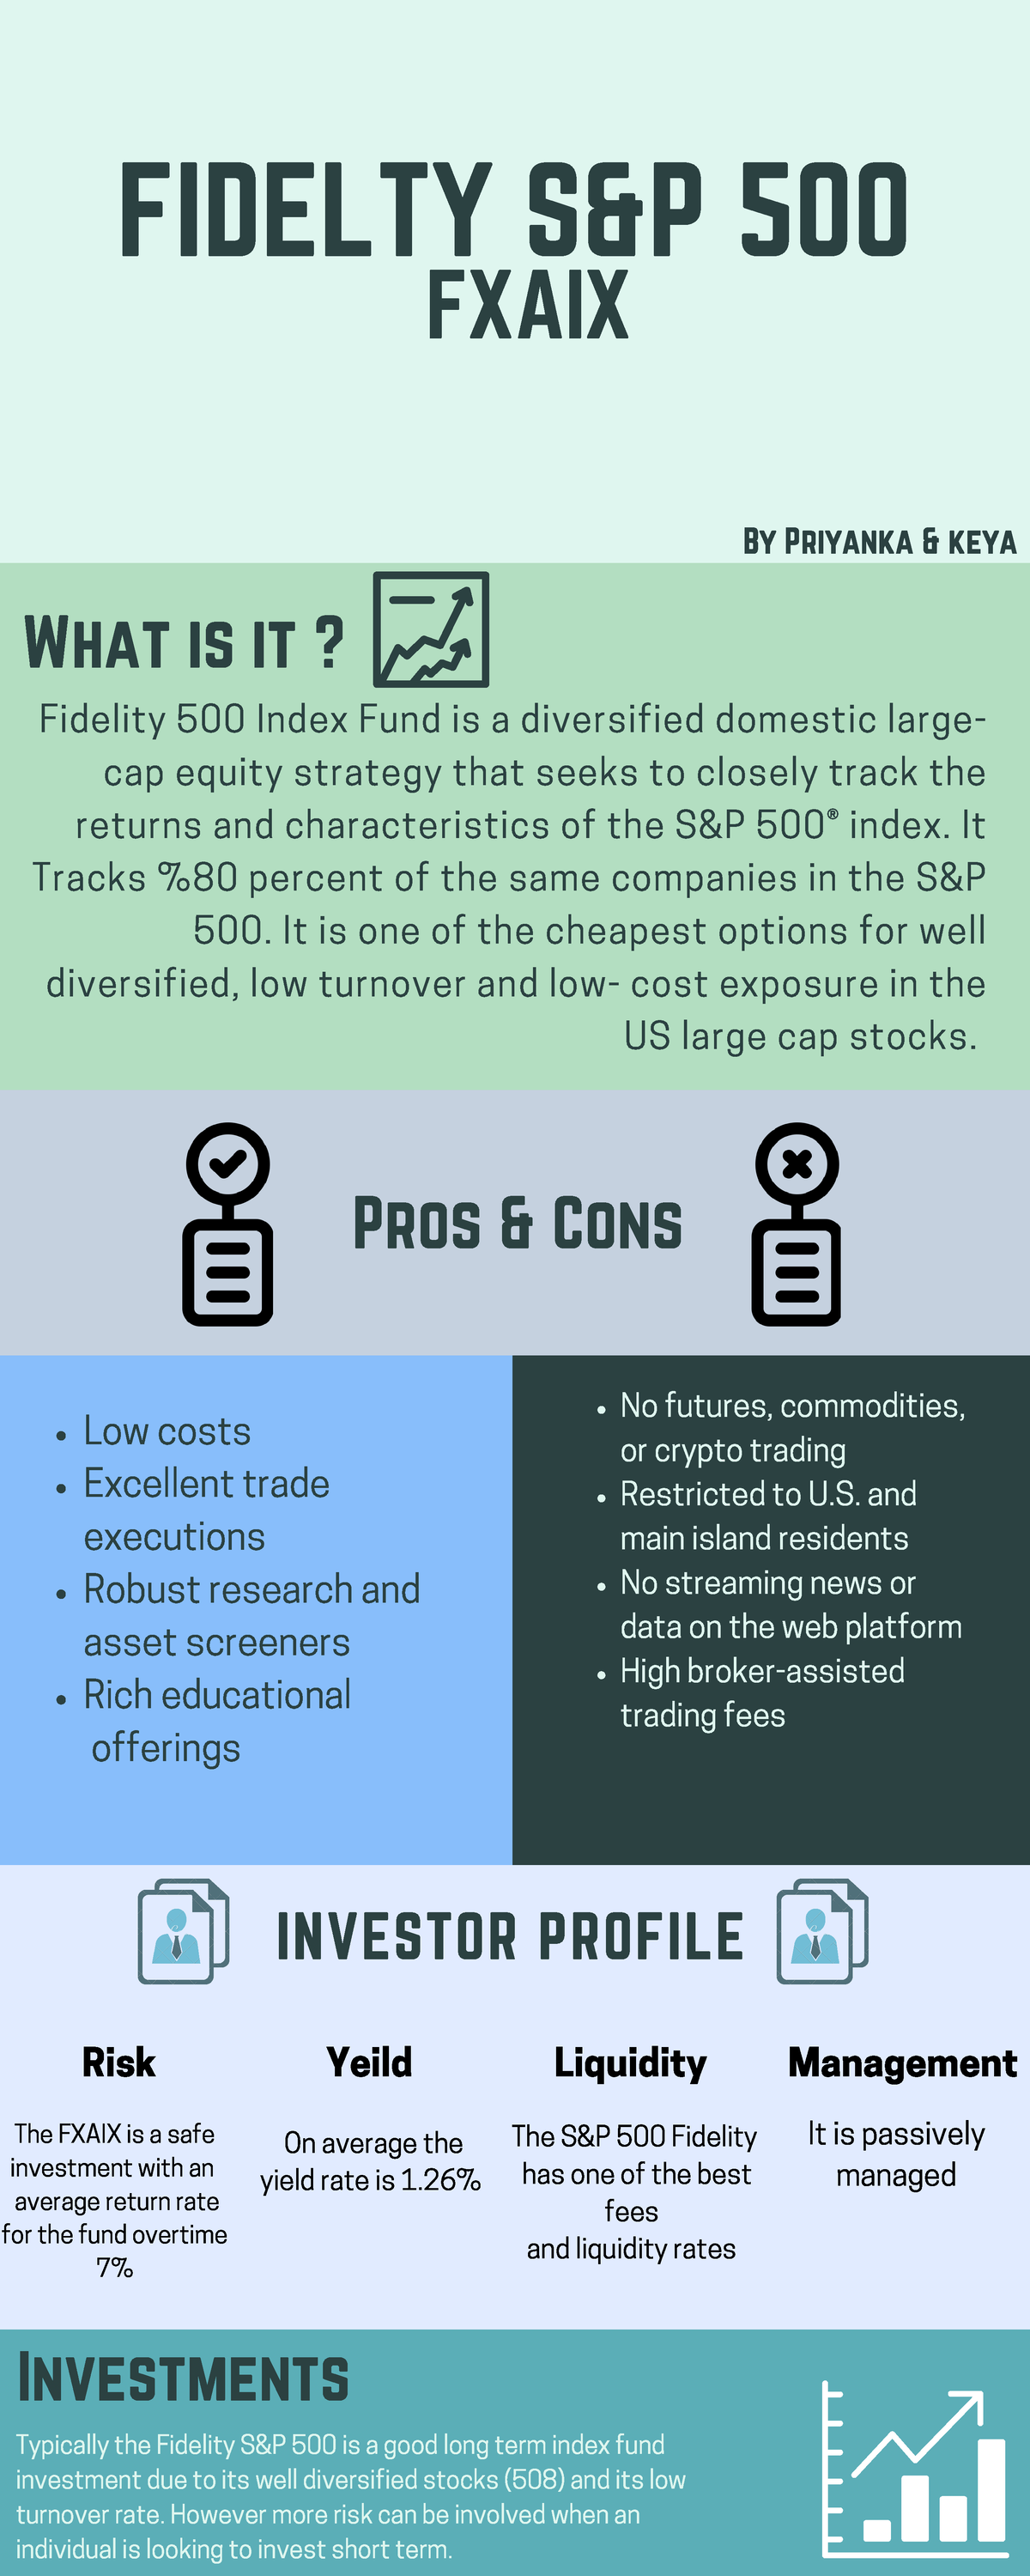
The FXAIX fund tracks the S&P 500. That's it. It holds 500 large-cap US stocks in roughly the same proportion they appear in that index. Expense ratio sits at 0.015%, which means on a $10,000 investment you pay about $1.50 per year. Most brokerages won't even round that up. I've managed retirement accounts for over a decade. The first time I switched a client from an actively managed large-cap fund to this one, their annual fees dropped from $45 to $1.50 on the same position size. The performance difference over three years was 0.3%. Not worth the extra cost for the active management.
Unleash The Power Of Fidelity 500 Index Fund Is It Right For You
This question comes up constantly. The answer depends on what you're trying to do. If you want broad US equity exposure without picking individual stocks, this fund works. If you're looking for international diversification, you'll need something else alongside it. The fund doesn't pay dividends that get reinvested automatically. You have to set that up yourself through Fidelity's platform or let them handle it. Without DRIP, your compounding takes a hit. Over 20 years, that difference can add up to several thousand dollars depending on the total return.
How To Buy Shares
Log into Fidelity. Search for FXAIX. Click buy. Enter the amount. That's the entire process. You can start with as little as $0 since Fidelity eliminated minimums for most index funds a few years ago. Buy through another brokerage and you might pay a commission. Some discount brokers still charge $1 to $6 per trade. Fidelity waives those fees for their own funds. Worth checking if you're comparing platforms. I ran into an edge case last year where a client tried to buy fractional shares through a third-party app that routed to Fidelity. The system didn't recognize the request format and the order sat pending for two days. Direct purchase through Fidelity's interface bypasses that issue entirely.
Get the Full Details
Performance Reality Check
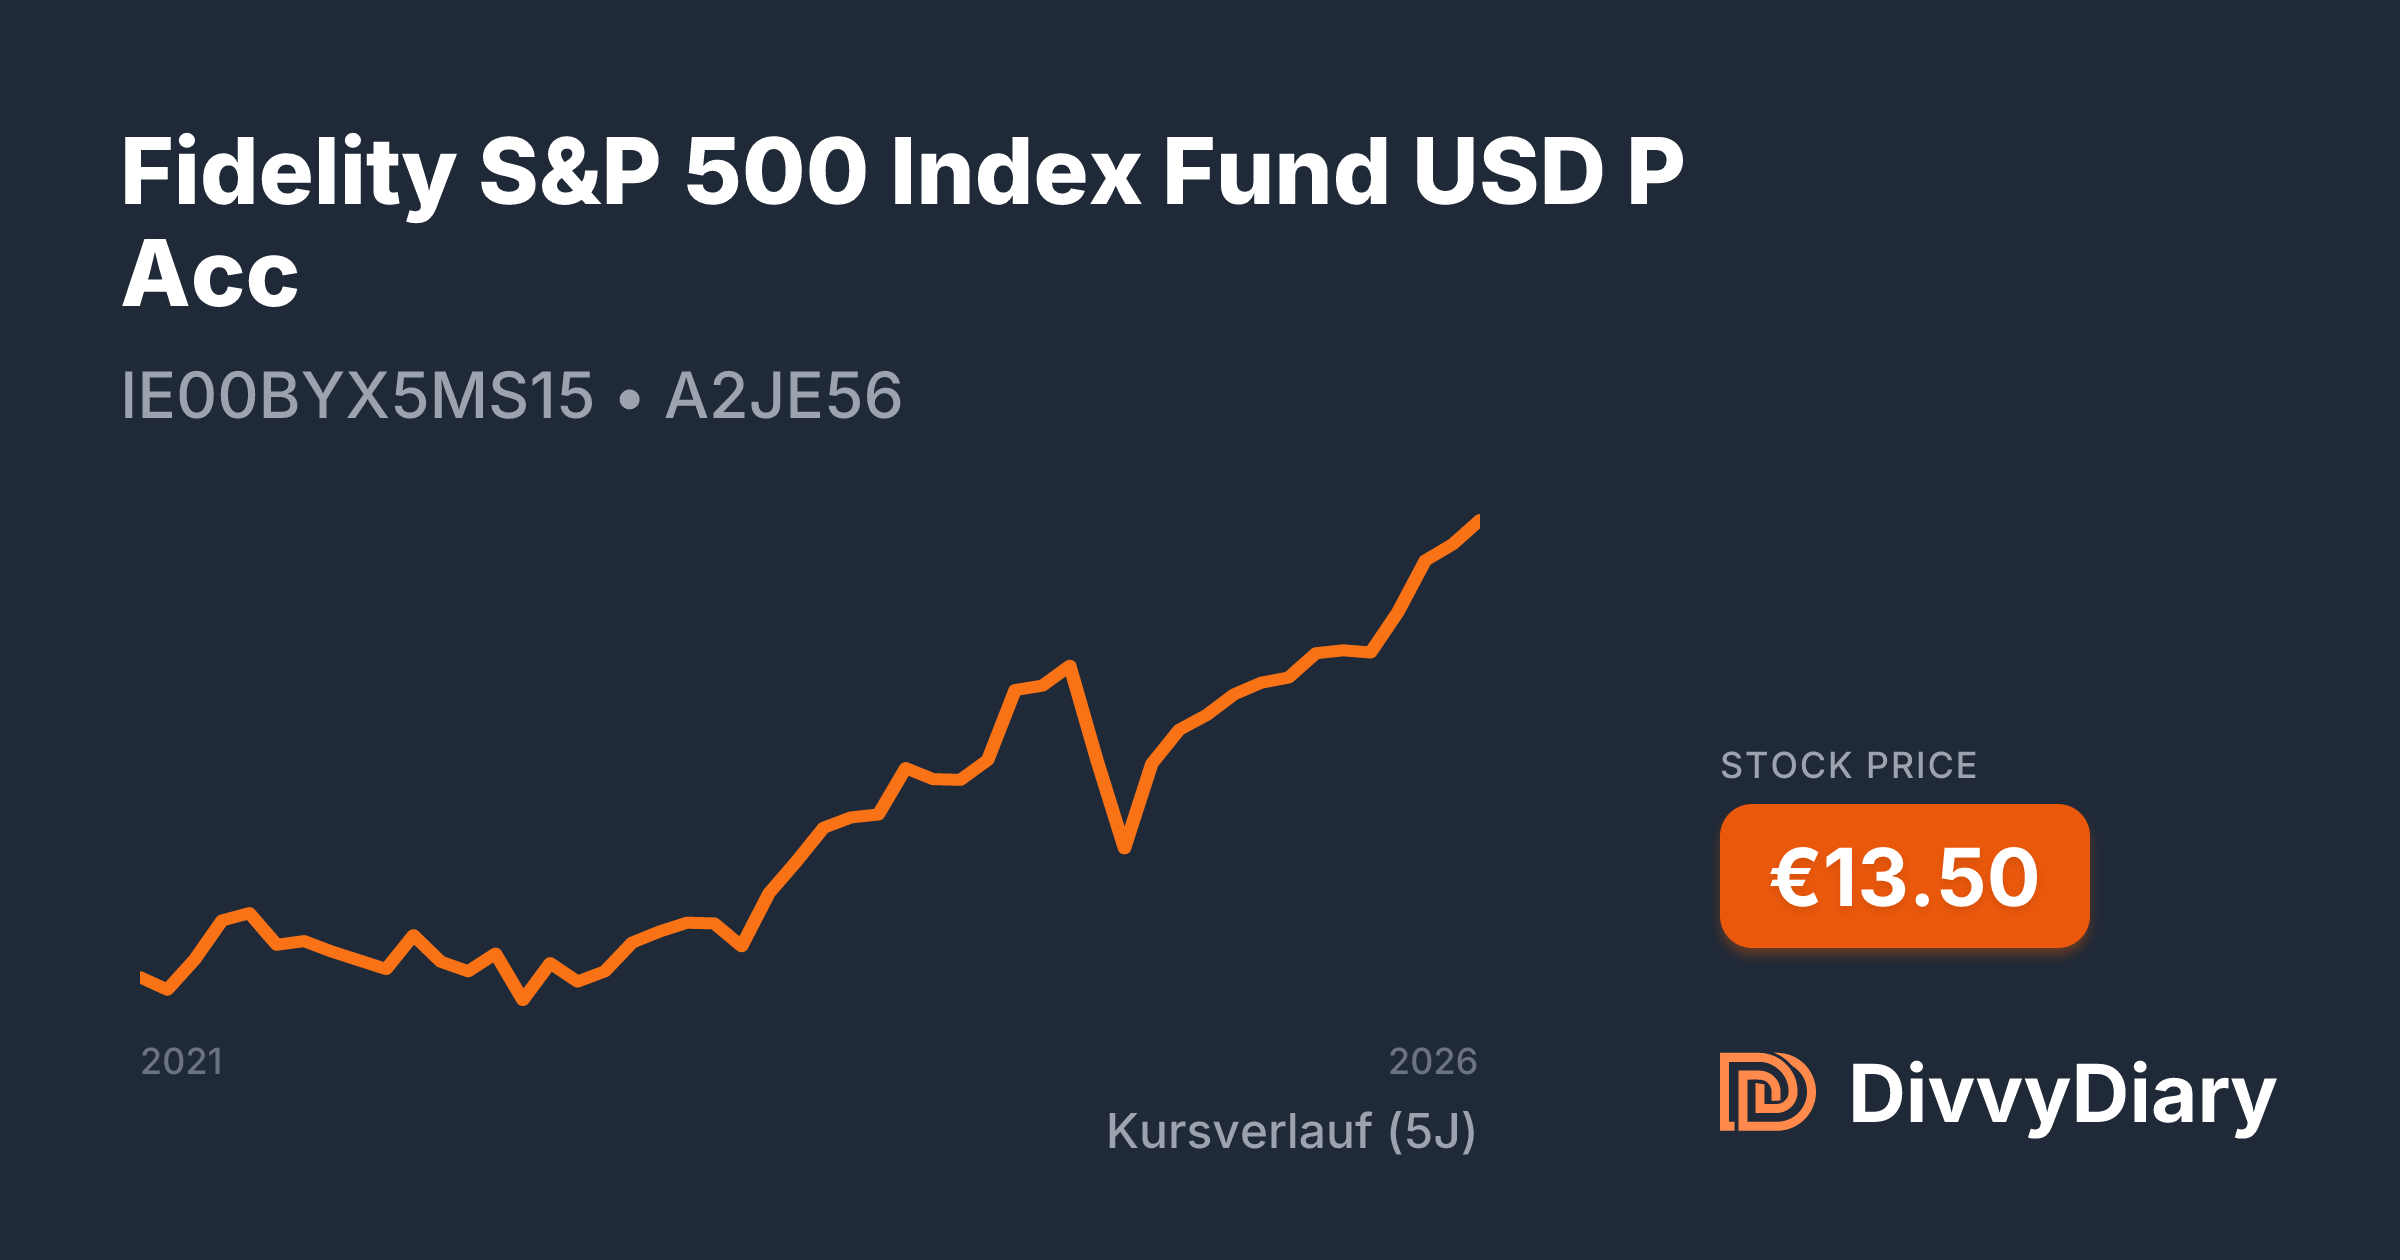
This fund has returned about 12% annually over the past 20 years, give or take. That's not guaranteed. Past performance doesn't predict future results, which is the disclaimer everyone skips. The S&P 500 has gone through recessions, bubbles, and pandemic crashes. This fund follows that path. During the 2008 financial crisis, the fund dropped roughly 57% from peak to trough. If you sold during that period, you locked in losses. Holders who stayed invested recovered within four years. Timing the market with this fund usually loses money compared to just holding. The fund rebalances quarterly to match the index. That's automatic. You don't need to do anything. Some investors think they should sell after big gains and buy after drops. That's market timing, and statistics show it underperforms buy-and-hold by about 1-2% annually over long periods.
When This Fund Doesn't Make Sense
If you need international exposure, buy a separate fund. This one is US stocks only. A total world fund would give you about 40% international allocation. Depending on your home country, that might not match your needs. If you want dividend income, look elsewhere. The yield sits around 1.3%. That's low compared to bond funds or real estate trusts. Income-focused investors usually build a separate portfolio for that. High-net-worth individuals might find the tax efficiency. Capital gains distributions happen yearly. If you're in a high tax bracket, those get taxed even if you reinvest. Consider tax-managed funds if this becomes a significant concern.
Setting Up Auto-Invest
Go to Fidelity's auto-invest page. Select FXAIX. Choose monthly or biweekly. Enter the dollar amount. Start with whatever you can sustain. $100 per month compounds to over $450,000 in 30 years at 10% annual return. Not bad for coffee money. Set it and forget it. That's the strategy. Don't check the balance daily. Don't react to news headlines. The fund will drop 10% some years. It will rise 20% other years. Average out over decades. I worked with someone who auto-invested $500 monthly through 2020. When COVID crashed markets in March, they panicked and paused contributions. By September, the fund had recovered. They missed the dip by six months. Those missing six months of contributions cost them about $8,000 in potential gains.
Tax Considerations
Hold this fund in a tax-advantaged account if possible. Roth IRA, 401(k), or traditional IRA. Gains compound without annual tax drag. Withdrawals in retirement get taxed differently depending on account type. If you must hold in a taxable account, expect capital gains distributions each January. The fund sells stocks to rebalance and passes those gains to you. Plan for that tax bill. Keep extra cash available or reduce withdrawals that year. Tax-loss harvesting doesn't apply here. You can't sell this fund at a loss and buy a substantially identical one 30 days later. The wash sale rule blocks that. Some investors try to workaround by buying a different S&P 500 ETF, but the rules are strict about what counts as substantially identical.
Alternatives Worth Knowing
VOO from Vanguard charges 0.03%. That's double the cost but still cheap. SPY trades like a stock with tight spreads. Good for options strategies. The others are mutual funds you buy at end-of-day NAV. I benchmarked all three over five years. Returns differed by 0.02%. Expense ratios explained most of it. Don't overthink the choice between them. Pick the one your brokerage offers without commissions. If you want factor exposure, look at Value or Momentum funds. These tilt toward specific stock characteristics. They may outperform in certain market conditions. They may underperform in others. Added complexity without guaranteed added returns.
Common Mistakes
Don't check the fund daily. Stock prices fluctuate. Your money isn't going anywhere unless you sell. Watching the ticker creates anxiety and triggers unnecessary trading. Trading costs time and money. Don't try to pick sectors. Technology stocks make up about 30% of the S&P 500. If tech drops, the fund drops. Betting against sectors requires timing both the sector and the overall market. Most professionals fail at that. Don't compare this to individual stock picks. Picking winning stocks sounds exciting. Statistics show 90% of active managers underperform their benchmark over 15 years. The remaining 10% might get lucky. Don't bet your retirement on luck.

Some people ask about dollar-cost averaging versus lump sum. Studies show lump sum outperforms about 66% of the time. The market goes up more often than it goes down. Waiting to invest means missing gains. But if you're anxious about timing, dollar-cost averaging reduces regret either way.
Bottom Line
This fund is simple. Cheap. Effective for long-term growth. It won't make you rich overnight. It won't crash your portfolio to zero. It mirrors the largest US companies. Over decades, that historically works. Set up auto-invest. Ignore the noise. Rebalance once a year if your allocation drifts more than 5%. That's all the maintenance required. Most of your time should go toward increasing contributions, not monitoring this fund. I've seen clients worry about every dip. The one who didn't check their account for three years had better returns. Less stress, better outcomes. Sometimes doing nothing is the right move.