The Reality of Points, Cash Back, and Redemption Friction
Most people pick up a store rewards card and assume the math is simple. You spend money, you get points back. It's not that simple. I've sat across from too many folks at credit card forums who are genuinely surprised when their rewards statement doesn't match what they expected, or when they hit a redemption wall because they didn't understand how the program actually worked. The card in question here — the one issued by Comenity in partnership with a beauty retailer — follows a structure that's common across the entire Comenity portfolio. That matters, because if you've used any other Comenity card before, you already know roughly how this one operates. If you haven't, you're flying blind compared to someone who has.
Unlocking Value With The Comenityulta Beauty Rewards Mastercard A Deep Dive
Here's how the program works in practice. You earn points on purchases. The rate is not flat. It depends on your tier status, which is determined by annual spending. You'll start at the base tier, which typically awards one point per dollar on most purchases, sometimes with occasional bonus categories that rotate or stay fixed. The important thing everyone misses is that the base earning rate is essentially break-even or worse once you factor in the opportunity cost of using a single-purpose card instead of a general rewards card. My first mistake with this card was treating it like a cash-back product. It isn't. It's a loyalty currency that only has value inside a single ecosystem. I loaded up on purchases for months thinking I was building something substantial. My balance at redemption time was roughly 4,200 points. I went to the portal to redeem them and found out that my tier hadn't moved past the entry level, which meant I couldn't access the higher-value redemption options. I had to burn about 800 points just to unlock the ability to redeem points at all for a purchase discount. The effective rate after that threshold dropped to well under one percent on my total spend. The workaround was straightforward but annoying. I called customer service during off-peak hours — Tuesday afternoon, anything but the first week of the month — and asked specifically about tier progression timelines. They confirmed that spending hits were evaluated quarterly, not monthly, which is a detail almost nobody reads in the terms. I consolidated my beauty purchases onto this card for the next quarter instead of spreading them across different cards, and by the following review cycle, I crossed into the next tier. That pushed my earning rate up enough that the card became marginally useful for its intended purpose.
This is the pattern. The card is useful if and only if you are a frequent buyer at the associated retailer and you are willing to concentrate your spending there rather than diversify. If you go to the store maybe twice a year, leave this card in the drawer. The annual fee, if there is one, will eat any marginal rewards before you even break even. I checked — some versions of this card carry no annual fee, which makes it less risky to try, but also means the value ceiling is lower because the issuer isn't subsidizing perks with that revenue stream.
Get the Full Details

The Catch With Redemption Timing and Expiration
Points expiration is the silent value killer in nearly every Comenity program. Your points don't vanish overnight, but they do reset on a schedule tied to account activity or a fixed calendar window, depending on the specific terms at the time of your application. I learned this the hard way when about 600 of my accrued points expired on a cycle I hadn't tracked. The notification email existed in my inbox somewhere, but I never set up reminders, and by the time I found it, it was too late. Ahead of any application or renewal, check your account dashboard for the exact expiration policy. It's usually buried in the rewards section under something like "Point Terms" or "Account Agreements." If the card allows points to roll over indefinitely with activity, great. If there's a time limit — say, 18 months of inactivity wipes the balance — then you need to treat that card like any other expiring asset. Use it or lose it, literally.
Competitive Alternatives Worth Considering
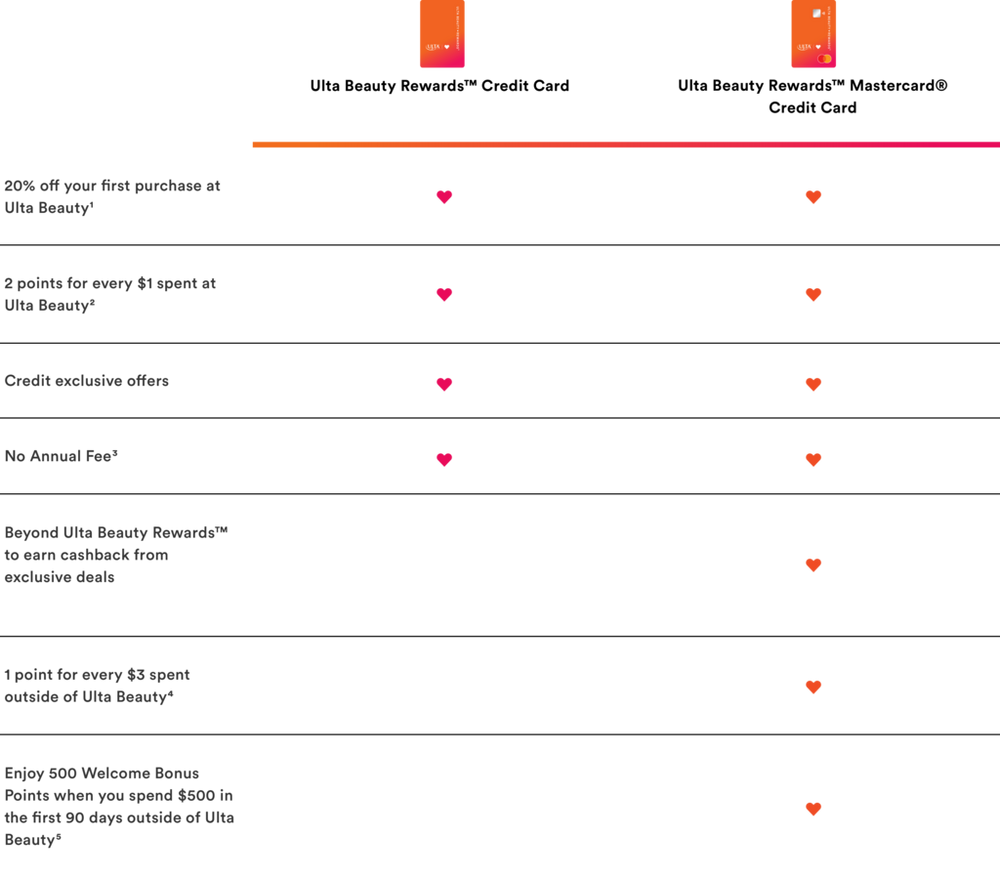
If beauty purchasing is your main goal, you're better off comparing this card against the major no-annual-fee cash-back cards before committing. A flat 2 percent cash back on everything from a Visa or Mastercard issued by a major bank will beat the points conversion rate on most Comenity store cards, especially once you factor in redemption friction. The Comenity card only wins if the sign-up bonus is substantial enough to offset the lower ongoing rate, or if you qualify for promotional multipliers that temporarily push the effective return above what a standard cash-back card offers. I've found that the sign-up bonus on these cards tends to range from 2,000 to 5,000 points depending on the current promotion, which might look like $20 to $50 in value at first glance. But those points often require you to spend a minimum amount within 90 days — usually $500 to $1,000 — and the points may not be usable immediately. Some programs lock sign-up bonuses behind a hold period where points post but can't be redeemed until you reach a certain tier or complete a secondary requirement. Read the fine print on the bonus structure before you apply. I once applied for a card expecting an immediate credit and ended up waiting six weeks for the points to actually become redeemable, during which time I could have been earning on a different card.
Practical Usage Strategy
Use this card if you shop at the associated retailer more than three times per year. Concentrate your high-value beauty purchases — skincare sets, holiday gift bundles, professional tools — on this card during promotional earning windows if they're running. Skip it for everyday spending that you could put on a broader rewards card. Keep your account active enough to prevent expiration, but don't carry a balance. The interest charges on a Comenity-issued store card are typically on the higher end of the credit card market, easily in the 22 to 29 percent APR range depending on your credit tier and the specific offer you qualified for. I stopped carrying a balance on this card after my first billing cycle. The minimum payment was small, but the interest that accumulated in just 31 days was larger than the total rewards I earned that entire month. That was the moment I realized the math only works if you pay in full every single cycle. Anything else turns a modest rewards card into an expensive debt instrument, and no amount of point-hunting is going to compensate for that.