The Cash Sweep Mechanism Most People Ignore Until They Need It
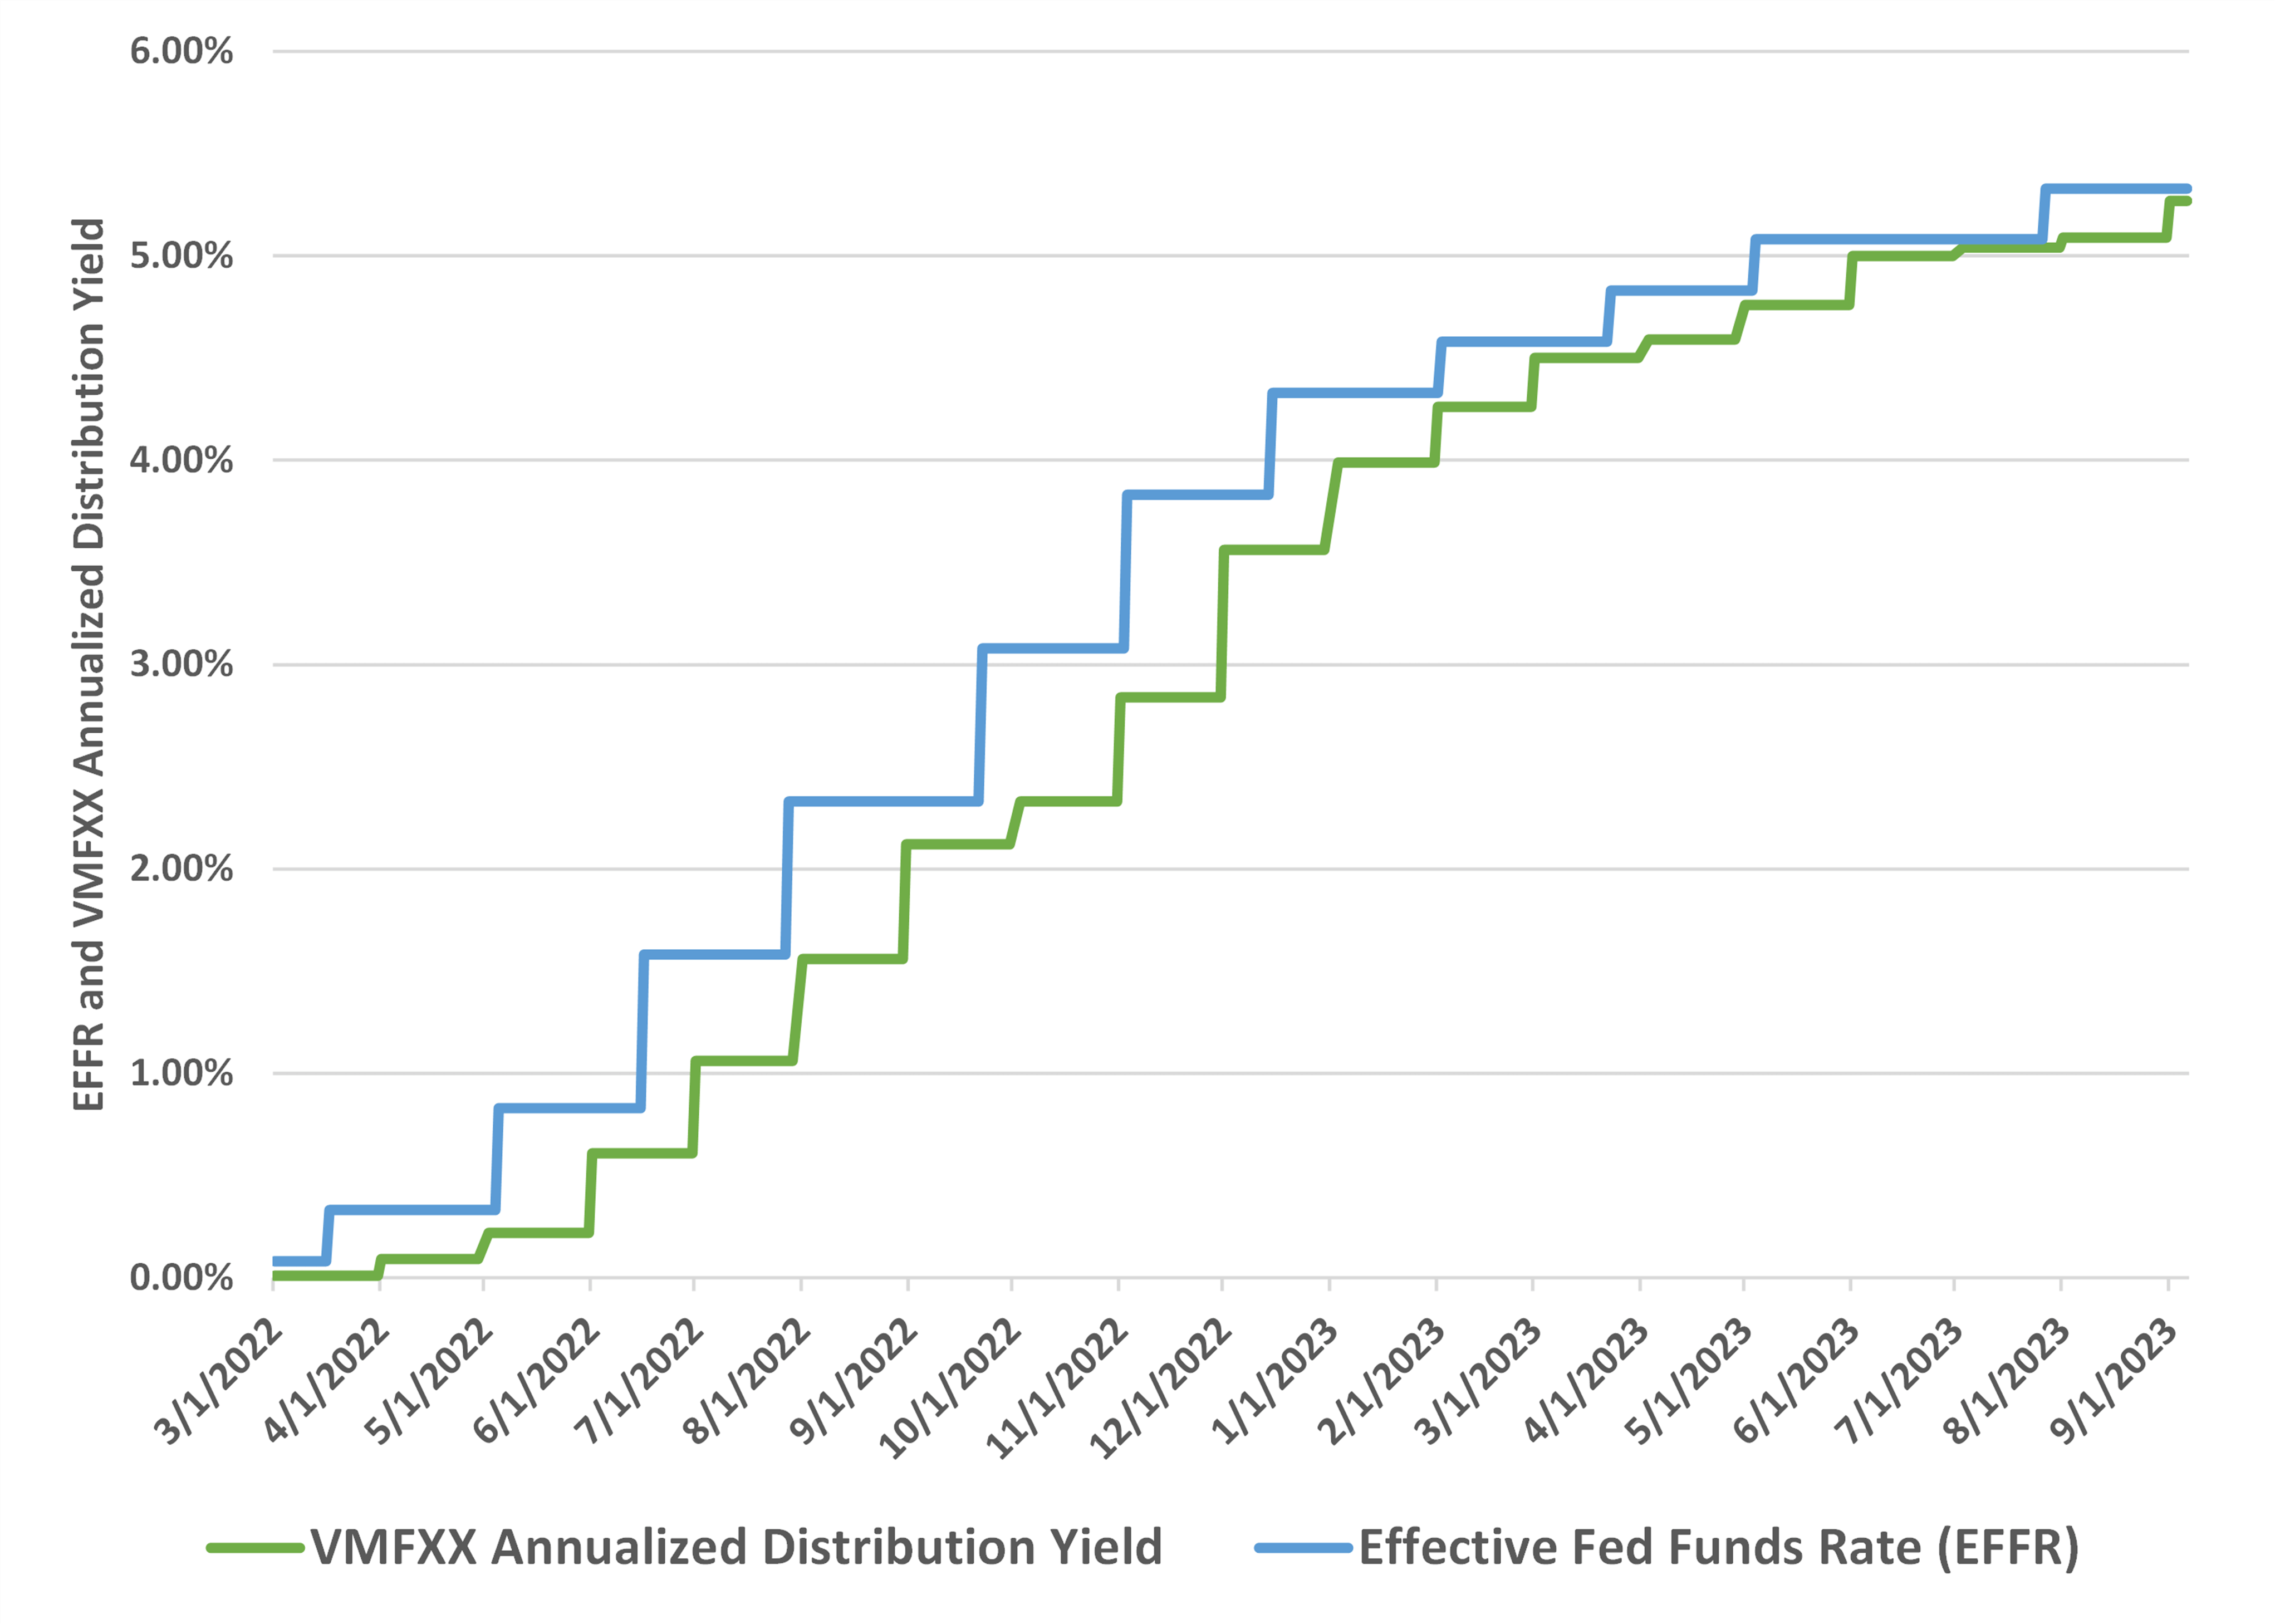
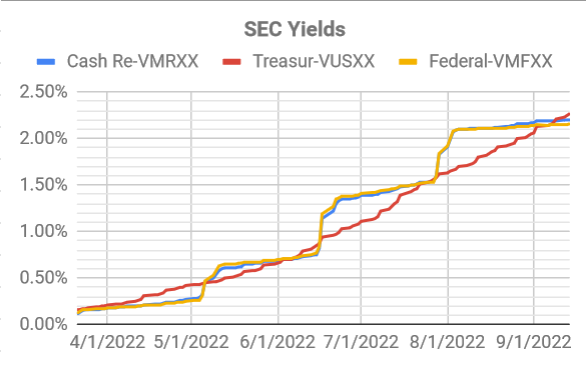
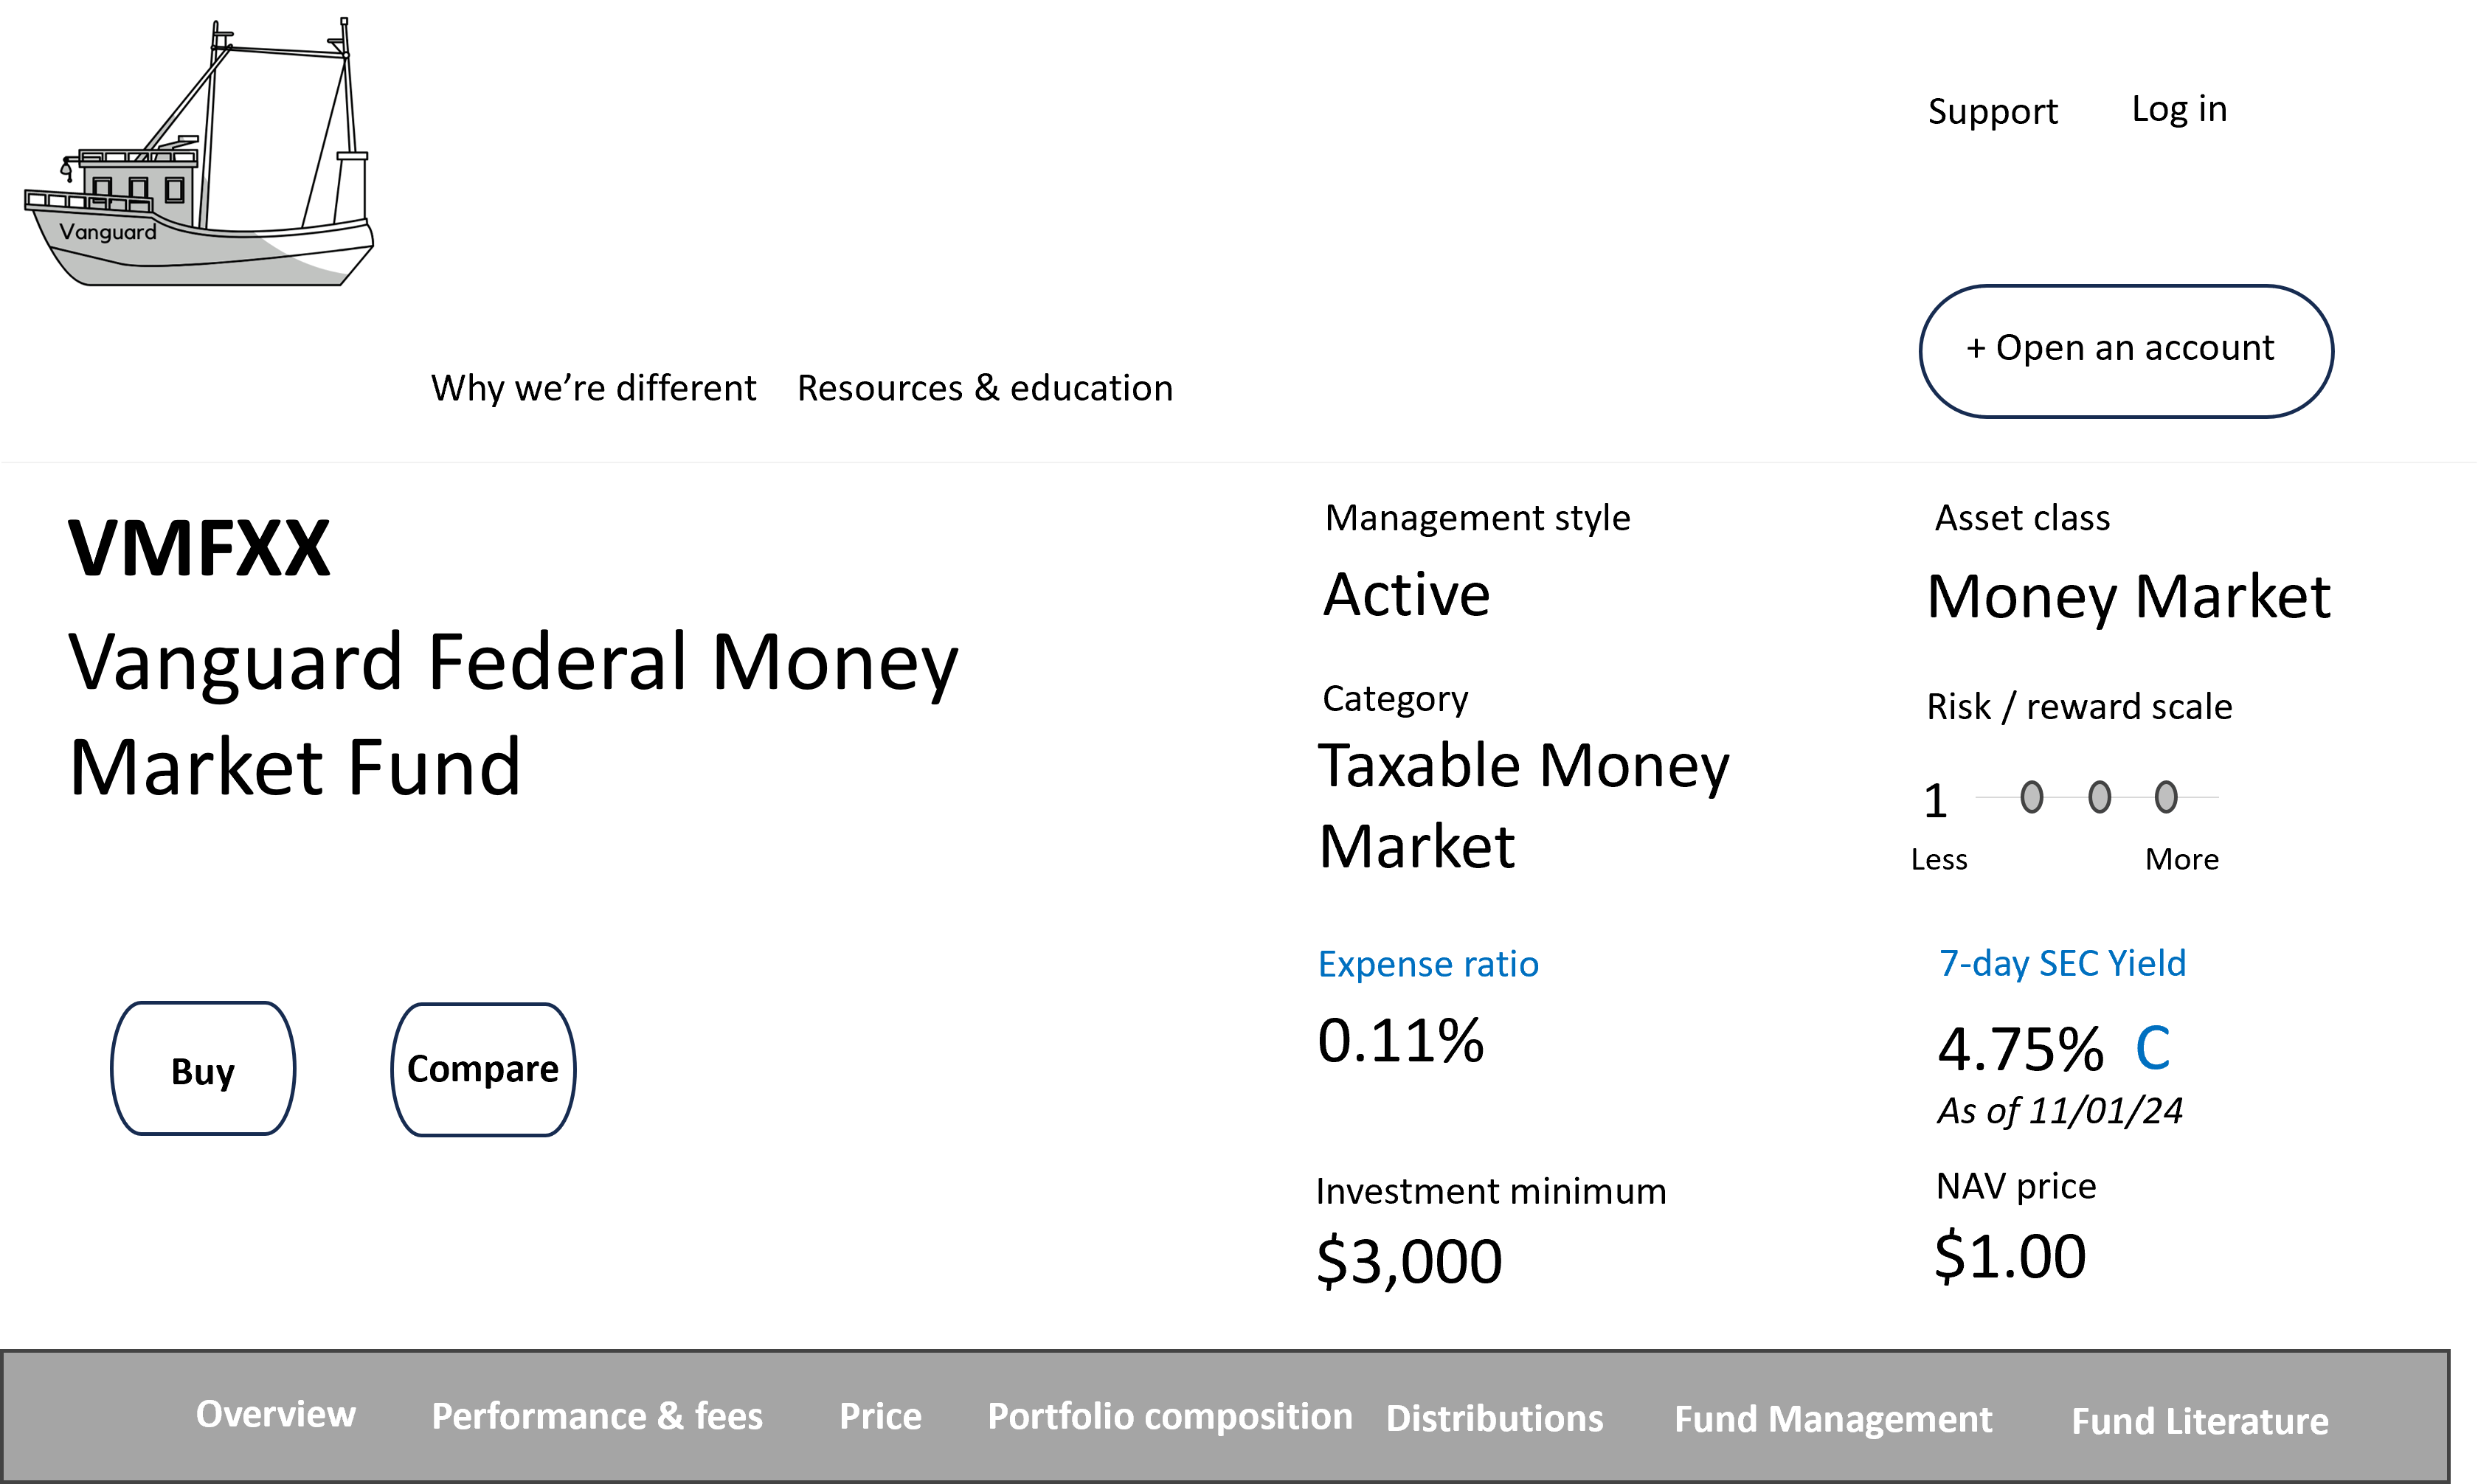
When you deposit money into a Vanguard brokerage account, it doesn't just sit in a checking-like pocket waiting for you to make a decision. It gets swept immediately into a money market fund. For most people, that fund is VMFXX, the Vanguard Treasury Money Market Fund. This is the default sweep destination. The cash earns yield while parked there. The yield changes every day based on short-term Treasury rates. You don't need to do anything to participate. The sweep happens automatically. The mechanics are straightforward. Your settlement cash gets swept into the fund at the end of each business day. On the Vanguard platform, this shows up as shares purchased at $1.00 per share. The share price stays flat because this is a government money market fund. The yield you see quoted is the SEC-compliant yield, which is a standardized way of expressing what the fund earned over a 30-day period, annualized and adjusted for any fees. The current yield sits somewhere in the low-to-mid 4% range as of mid-2025. That number moves when the Federal Reserve moves.
Understanding Vmfxx Sweep In Vanguard A Comprehensive Guide To The Funds Mechanics And Strategy
The fund invests in U.S. Treasury securities and repurchase agreements backed by Treasuries. This is different from a corporate money market fund or a prime fund. The credit quality bar is very high because the underlying collateral is the full faith and credit of the U.S. government. That is the main selling point. You get FDIC-like safety without being in a bank account, and the yield usually beats what a traditional savings account offers by a wide margin. The sweep also handles things like incoming wire transfers, dividend deposits, and proceeds from stock or bond sales. All of that settlement cash flows into VMFXX by default. If you set up automatic investment plans or have a recurring transfer going into a particular fund, the sweep logic still applies to any cash that hasn't been assigned elsewhere. The money sits in VMFXX until you move it. This is where the strategy question comes in. Should you leave cash there, or should you set up something more deliberate? I want to address something that comes up constantly. People see the yield and assume it is guaranteed. It is not. The fund aims to maintain a stable $1.00 NAV. That means it uses amortized cost accounting and maintains a weighted average maturity of 60 days or less. This keeps the price stable, but the yield itself is variable. If the Fed cuts rates, the yield drops. If rates stay elevated, the yield stays elevated. The fund cannot promise you a fixed return. It can only promise that your principal is preserved in dollar terms.
Here is an edge case that tripped me up once. I had a large sum parked in VMFXX and needed to move it to fund a tax liability payment. The sweep logic means your cash is technically in the fund, not in a bank account. When you initiate a payment from your Vanguard account, the system sells enough VMFXX shares to cover it. That sale settles in one business day. So if you schedule a payment on a Friday, it likely won't hit until Tuesday. I learned this the hard way when I tried to time a payment around a holiday weekend and missed the cutoff. The workaround is simple: schedule the payment early in the week, or keep a small buffer outside of VMFXX in a linked bank account for time-sensitive transactions. Do not assume instant availability just because the cash is in your Vanguard account. Another nuance that people often miss involves the tax treatment. Treasury money market fund distributions are subject to federal income tax. They are generally exempt from state and local taxes, which matters if you live in a high-tax state. The distributions are reported as ordinary income on Form 1099-DIV. You will see them broken down as interest income from the fund. There is no capital gains component in a typical month. The fund pays out almost all of its earnings as dividends, which keeps the share price at $1.00. The fee structure is minimal. The expense ratio for VMFXX is around 0.13%. That is taken out of the yield you see, so the quoted yield is net of fees. Compare that to a corporate money market fund, which might run slightly higher, and the difference is small but consistent over time. Over a year, a 0.13% fee on a large balance adds up. It is not dramatic, but it is real. The trade-off is the lower risk profile, which is the whole point of using a Treasury fund instead of a prime fund.
Get the Full Details
One thing that is worth understanding about the sweep mechanism is how it interacts with Vanguard's cash allocation features. You can set up multiple sweep destinations if you want. You can direct cash to go into a specific fund other than VMFXX, though you need to contact Vanguard to change the default. Some people do this to capture higher yields from a higher-rate treasury fund or an overnight repo fund. The standard VMFXX sweep is convenient, but it is not the only option. If you are moving significant amounts of cash regularly, exploring whether Vanguard offers a better rate sweep option could be worth the setup time. There are limitations to keep in mind. The fund has a large asset base, which means it can absorb redemptions without significant disruption. That is a stabilizing factor. But the yield is not locked in. If the Federal Reserve enters a cutting cycle, as it has done periodically throughout the past decade, your sweep earnings will decline. This is not a criticism of the fund. It is simply the nature of a Treasury money market fund. You are earning the short-term rate. When that rate falls, your income falls with it. There is no way to hedge against that at the VMFXX level. I have also seen people treat VMFXX as a savings account replacement and then get confused about the FDIC insurance question. Money market funds are not FDIC insured. They are different products entirely. The fund's assets are held in Treasury securities, which are among the safest instruments in the financial system, but they are not bank deposits. In a worst-case scenario where the U.S. government defaults on its obligations, the fund would be affected. This is an extremely low-probability event, but it is worth acknowledging because it changes the risk profile compared to a CD or a savings account.
The practical reality is that VMFXX works well for short-term cash parking. If you have a few thousand dollars sitting in a brokerage account waiting to be deployed, this is a reasonable place for it. The yield is competitive, the liquidity is immediate for trades, and the tax treatment is simple. It is not a strategy for long-term wealth building. It is a parking spot. The people who treat it as a long-term strategy tend to get uncomfortable when rates start falling and the yield drops from 5% to 3% to 1.5% over a multi-year cycle. That is normal. It is the mechanism working as intended. If you need to manage larger sums with more precision, you can explore using Treasury bills directly or considering a short-term Treasury fund. Those options give you more control over duration and yield curve positioning, but they require more active management. VMFXX is the hands-off version. You choose between convenience and optimization. Most people choose convenience and never look back.