Ulta Comenity Credit Card Indepth Analysis Of Benefits Eligibility And Responsible Use
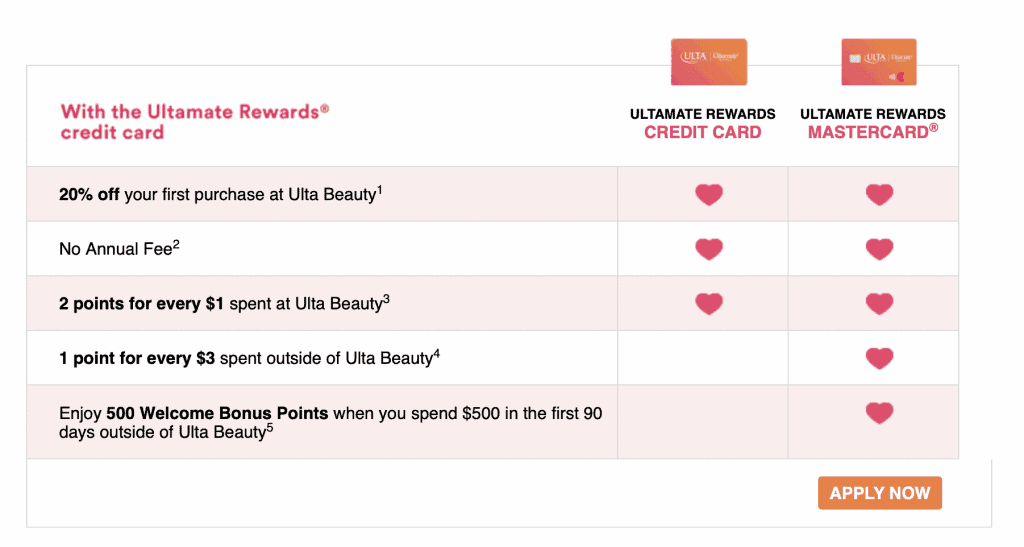
I've had this card for about four years. It sits in my wallet alongside three other store cards I rarely touch, and honestly, that's exactly how I want it. Let me walk you through what actually happens when you use this thing, because the fine print is where most people get burned. The Ulta Comenity credit card isn't a single product. It's two tiers disguised under one brand. The standard card is the entry-level version. The premium version, sometimes called the Ulta Credit Card with Ultamate Rewards, gives you accelerated points but comes with a slightly higher APR floor. Both are issued by Synchrony Bank, which acquired Comenity Bank's consumer portfolio in 2023. If you're reading old forums saying "Comenity Bank," that's why. The rewards structure is straightforward but with a trapdoor. Standard cardholders earn 1 point per dollar on all Ulta purchases. If you're an Ultamate Rewards member (free to join, just give them your email), you get 2 points per dollar on Ulta purchases. Non-members get 1 point per dollar. That distinction matters more than people realize because the point value only becomes meaningful if you're actually accumulating volume at Ulta. I know people who sign up for the card, buy a single mascara during their birthday month, and then wonder why they never seem to have enough points for anything.
Eligibility Realities
Synchrony typically looks for a FICO score in the 650-700 range for approval. That's "fair to good" credit, not excellent. Here's what nobody tells you: getting denied doesn't always show up as a hard inquiry if they decline you before the full pull. I got declined once during an application and checked my credit report three months later. The hard inquiry was still there, but at least I knew not to reapply for six months. If you're already under 650, don't waste the inquiry. Work on your credit utilization first, usually under 30%, and try again later. There's also an income verification question on the application that trips people up. They ask for your annual income, and if your stated income doesn't align with what they see from credit bureau data, they can deny you regardless of your score. I've seen this happen with people who list side income that isn't yet reported to the major bureaus. The workaround is simple: list only verifiable income sources and if you're borderline, skip the application until your primary income is established in the system.
Benefits That Actually Matter
The birthday month bonus is real. You get a 20% off coupon emailed to you during your birth month. It applies to regular-priced items only. Exclusions include fragrance, skincare devices, and gift cards. I learned this the hard way after trying to use it on a $68 La Mer moisturizer last year and getting the discount rejected at checkout. Had to step away from the register and figure out which items in my cart were excluded. Takes about two minutes but it's annoying. The points program itself is decent if you understand the redemption floor. One point equals roughly $0.01 in retail value when you redeem for merchandise. That means 2,500 points is about $25 off a purchase. Not great, not terrible. The breakage rate on these points is something you should keep in mind. Points expire after 18 months of account inactivity, which means if you stop shopping at Ulta for a year and a half, you lose whatever you've accumulated. I've lost maybe $15 in points over four years because I forget to use them. Small price to pay for a card with no annual fee.
Get the Full Details

Special Financing Offers
Occasionally you'll see offers for 6 or 12 months special financing on purchases above a certain threshold. These are the most dangerous part of the card. If you don't pay off the balance before the promotional period ends, interest accrues retroactively from the original purchase date. That's a deferred interest structure, not a standard promotional rate. I fell into this once. Bought a hair styling tool set for $120 during a 6-month offer, forgot about it, and got hit with retroactive interest at 29.99% APR. Cost me an extra $18 in interest I never should have paid. Never use special financing unless you can write down the payoff date and set a calendar reminder. That's not hyperbole. This is a closed-loop card. It only works at Ulta and ulta.com. You can't use it anywhere else. Some people treat this as a limitation. I treat it as a feature. It prevents me from spending money I don't have at places I don't shop. When I try to use it at Target or Amazon, it declines immediately. That friction is actually useful. Pay it off in full every month. That's the single most important rule. The base APR sits around 26.99%, which is above average for a rewards card. There's no way to make the rewards outpace the interest cost unless you're carrying a balance and ignoring basic arithmetic. Set up autopay for the full statement balance. It takes 30 seconds to configure in the Synchrony mobile app and it eliminates any chance of a late payment hitting your credit report.
Use it for purchases you were already planning to make at Ulta. Don't buy things just because you have a 2% rewards rate. I once bought a $45 face cream I didn't need because "I'm earning points anyway." That's not earning. That's spending with extra steps.
When to Leave This Card Alone
If you rarely shop at Ulta, this card has no value. If you have trouble paying balances in full, the high APR will punish you. If you're actively building credit and need a card that reports to all three bureaus with a low credit limit to start, this might work, but there are better starter cards available from major issuers. The Ulta card is a niche product for a niche spender. Knowing which bucket you're in matters more than understanding every detail of the rewards structure. The Synchrony app handles this card along with most of their store cards. You can check your points balance, view statements, make payments, and see upcoming special financing expiration dates all in one place. The interface is functional but dated. I found the special financing tracker particularly useful after my earlier mistake. You can set push notifications for payoff deadlines, which costs nothing and prevents the deferred interest trap entirely. I wish I'd done that four years ago. The card is what it is. No travel benefits, no purchase protection worth writing home about, no elite status perks. It's a small rewards card for a specific retailer. If that fits your habits, it's worth having. If not, close the application tab and move on.