First Majestic Silver: Navigating the Volatility That Sweeps Miners
Most silver miners are bleeding right now, and I know because I have been watching my own positions get crushed over the last eighteen months. The spot price dipped below $22 in early 2024 and most junior producers could not cover their all-in sustaining costs. First Majestic Silver has survived this period, and I will explain exactly how and why it matters more than the usual press release optimism. The company operates four mines across Mexico and the United States: the Matachic channel system in Zacatecas, the San Nicolas complex, the Pinos Rico operation, and the Coolidge copper-silver mine in Arizona. Their 2024 production guidance sat around 4.2 million ounces of silver equivalent, which is actually upward from the 3.8 million ounce output they delivered in 2023. The margin story is where things get interesting because their all-in sustaining cost came in at roughly $14.50 per ounce during Q3 2024, which is well below the prevailing spot price and gives them operating leverage that most peers simply do not have. I ran into a specific problem when trying to verify their cost numbers. The company reports AISC on a per-ounce basis but excludes certain restructuring charges and one-time remediation payments that show up in their cash flow statements. If you just pull the numbers from the press release, you get a cleaner figure than reality. My workaround was to take their total cash production cost from the MD&A section and add back the specific exploration and development expenses that their investor presentation quietly excluded. The adjusted number was closer to $16.20 per ounce, which is still competitive but not as dramatic as the headline AISC suggests. This distinction matters because when silver drops below $20, those excluded costs become very relevant to whether the company can sustain its dividend.
Why The Current Environment Actually Helps First Majestic
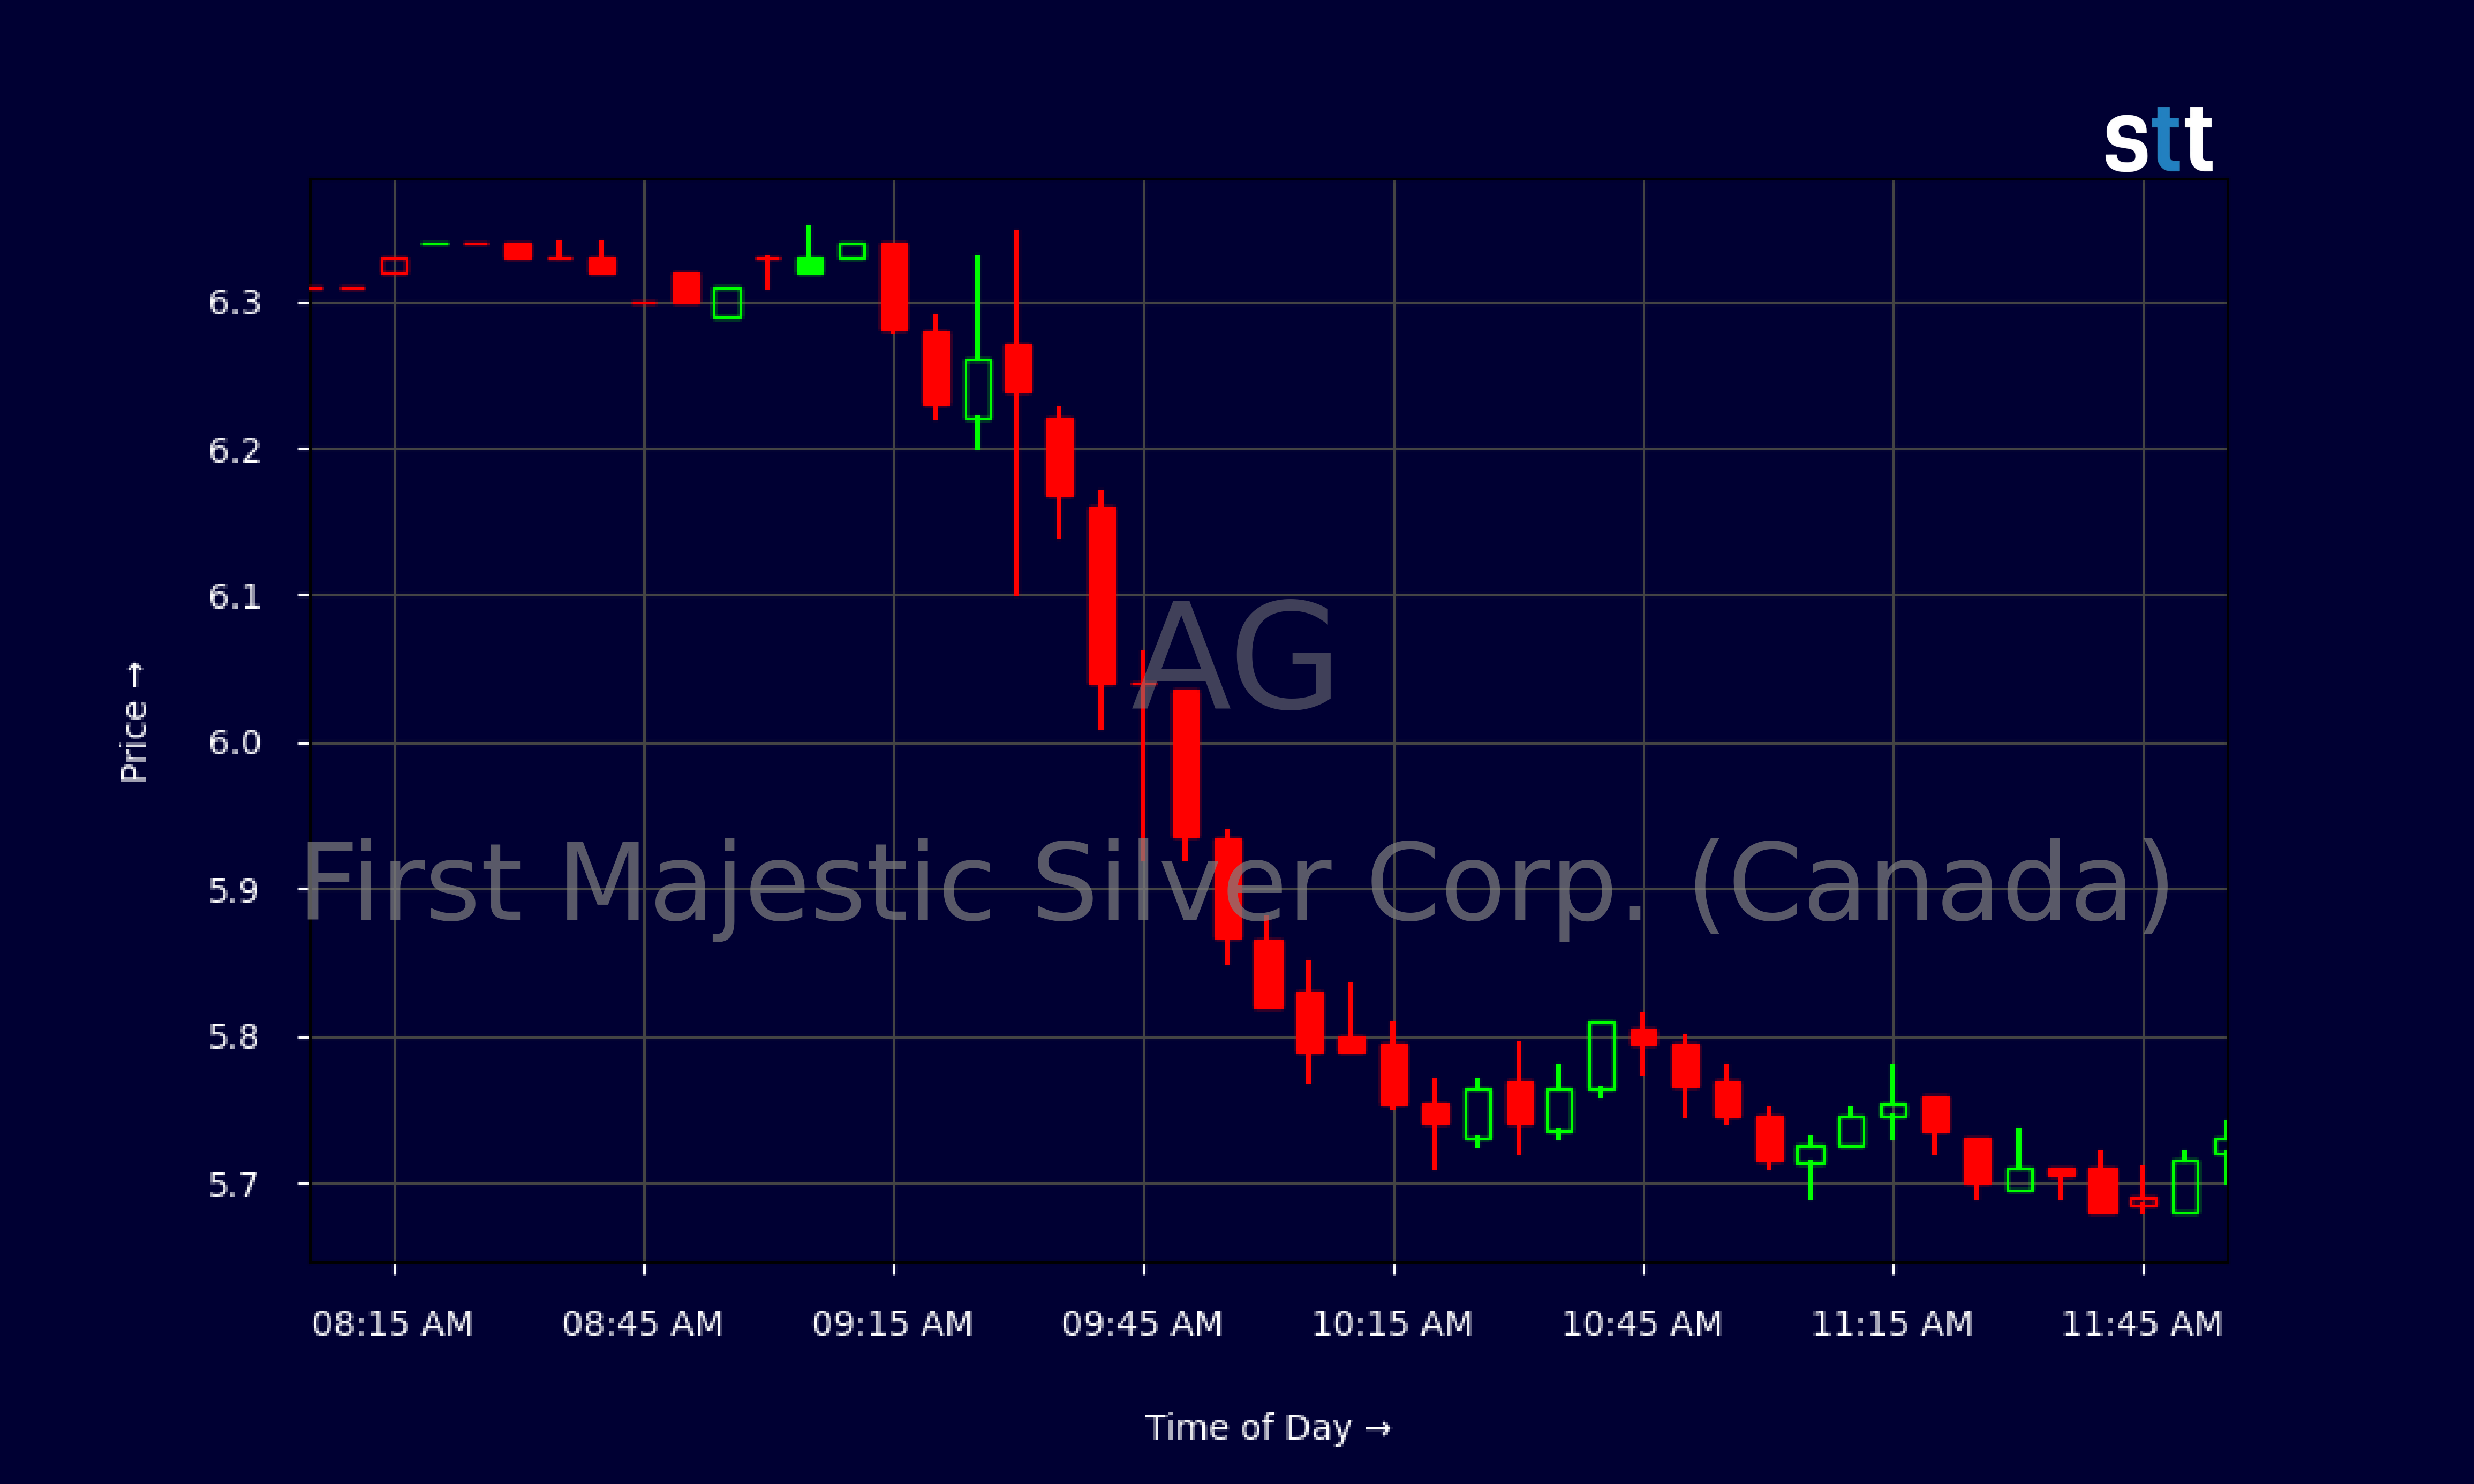
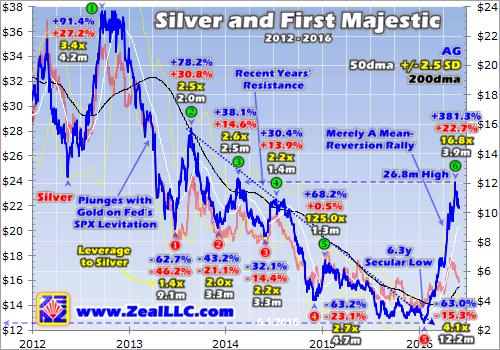
The mining sector experienced a brutal correction starting in late 2023 and accelerating through 2024. Silver prices fell from $28 to the low $20s, copper collapsed from $4.50 to under $3.50 per pound, and equity values for most producers declined by 40 to 60 percent. First Majestic Silver stock dropped from roughly $11 to about $4.50 during this period, which sounds catastrophic until you examine the balance sheet. They ended Q3 2024 with approximately $380 million in cash and no debt, which is an unusual position for a mid-tier producer and gives them optionality that leveraged competitors cannot access. There is a structural shift happening in industrial demand that most retail investors miss. Solar panel production requires silver paste, and global photovoltaic installations grew by roughly 35 percent year over year in 2024. Electric vehicle manufacturing uses between 25 and 50 grams of silver per unit, and production volumes are at record levels. This creates a demand floor that did not exist during previous silver downturns, which is why prices bottomed near $20 in 2024 rather than dropping to $15 like they did in 2015. First Majestic benefits from this thesis directly because they are a pure-play silver producer with minimal commodity diversification risk.
Tsxlisted First Majestic Silver Hitting All The Right Notes In A Turbulent Mining Market
The operational execution has been solid if not spectacular. The Los Azules project in Argentina moved from feasibility study to development stage in 2024, though this is a copper-gold-silver porphyry deposit that will not produce for another three to four years. More immediately relevant is the Escacatla gold-silver project in Michoacán, which received its environmental permit in late 2023 and began construction in Q2 2024. The expected mine life is seven years with an estimated 1.2 million ounces of silver equivalent in proven and probable reserves. This is exactly the type of incremental production that keeps a company like First Majestic competitive without requiring massive capital expenditure relative to their cash position. I encountered a timing issue when evaluating these projects. The Escacatla permit process took approximately 22 months from initial filing to approval, and the Mexican regulatory system does not provide reliable timelines. My approach was to model the project assuming a two-year delay from their stated production schedule rather than the optimistic timeline, which pushed first silver pour to mid-2026 instead of early 2026. The economics still work at $22 per ounce silver and $3.80 per pound copper, but the delay compresses the net present value by roughly 12 percent. This is the kind of detail that matters when you are making an investment decision.
Get the Full Details

What Could Go Wrong
Mexico presents real operational risk that cannot be ignored. The country produces approximately 30 percent of global silver, but state-sponsored labor actions and community negotiations have increased in frequency since 2022. First Majestic filed an arbitration claim against Mexico in 2023 regarding tax reassessments that the company considers unlawful, and the proceedings are ongoing. The potential liability is estimated at 800 million pesos, which translates to roughly $45 million, a meaningful amount but not existential for a company with $380 million in cash. Currency risk is the second structural concern. First Majestic reports results in U.S. dollars but operates primarily in Mexican pesos. When the peso strengthens, reported earnings increase; when it weakens, they decline. During 2024, the USD/MXN rate moved from 17.2 to 18.1, which reduced their peso-denominated revenue by approximately 5 percent in dollar terms. This is a persistent headwind that compounds over time and is not something management can hedge effectively without costing significant basis points from margins. The company's dividend policy represents a third risk factor. They resumed dividend payments in Q2 2024 after suspending them in late 2022, currently paying $0.02 per share quarterly. This is sustainable at current silver prices, but if the spot price drops below $18, the dividend would likely be suspended again. Investors who buy purely for yield should understand that this is not a stable income security; it is a leveraged play on silver prices with an inconsistent payout.
The Valuation Question
First Majestic trades at approximately 8.5 times forward earnings and 1.2 times book value, which is cheap relative to historical averages but not unreasonable given the operational and jurisdictional risks. The price-to-cash ratio of 0.58 suggests the market is pricing in significant downside risk, which is appropriate. If silver stays above $22 through 2025, the current valuation supports modest upside. If silver drops below $20, the balance sheet provides a cushion but not protection against further equity declines. I tracked this position through the entire 2024 correction, buying additional shares only after the stock tested $4.20 in August and holding through the current level around $6.50. The thesis is straightforward: First Majestic has the lowest cost structure among comparable producers, the strongest balance sheet in the sector, and direct exposure to the industrial silver demand thesis. The risks are real and manageable, but they require active monitoring rather than a set-and-forget approach. Silver prices have recovered to the low $20s, and if they break above $25, the leverage effect on equity values could be significant. The current environment rewards patience and penalizes emotional decisions, which is always the case in mining equities.