Why Zillow Estimates Are Not Your Final Answer
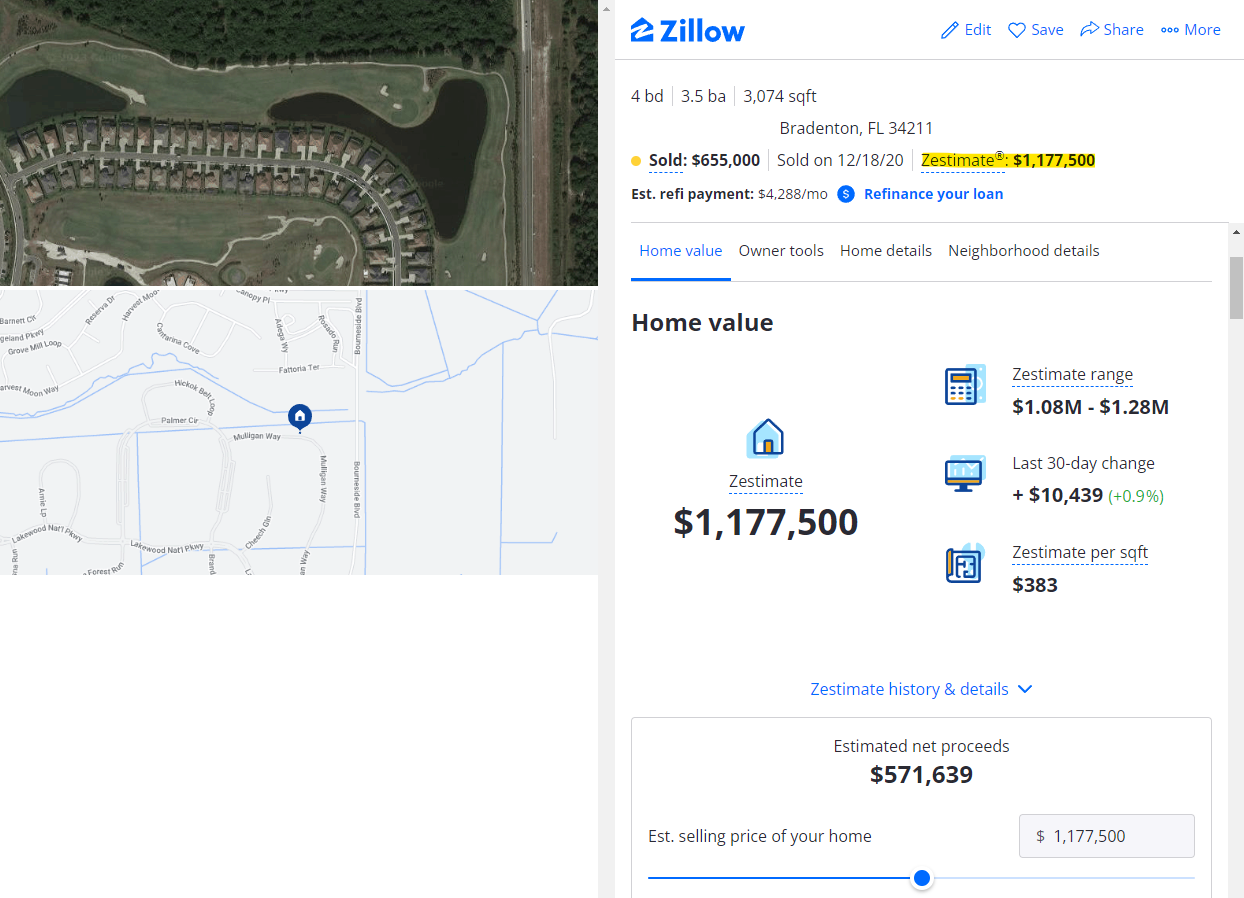
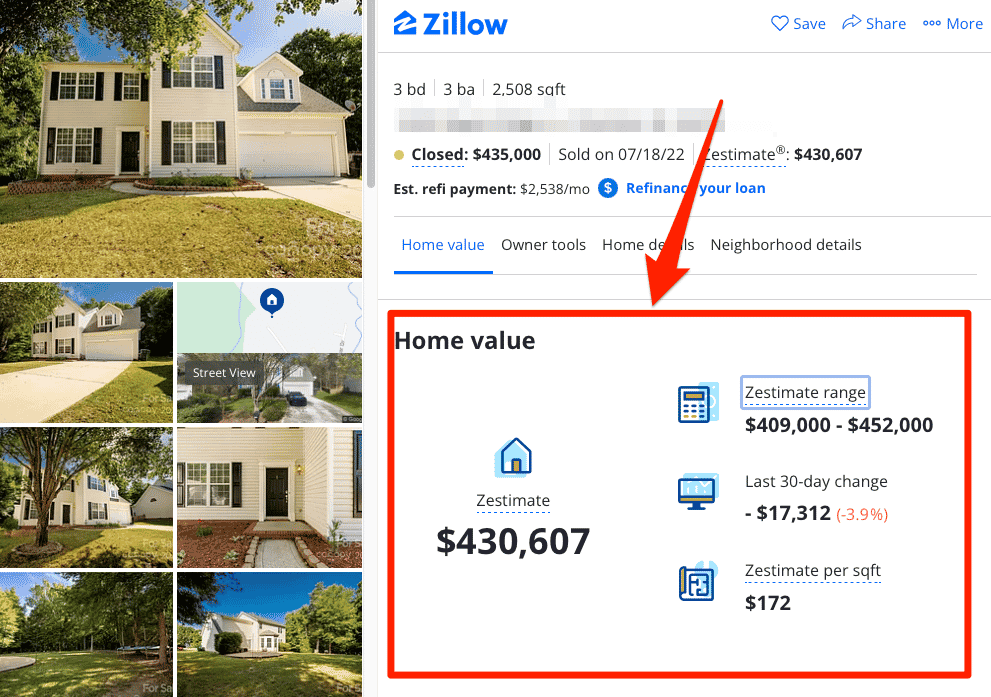
Zillow's Zestimate is a starting point, not a conclusion. I have walked through dozens of home sales over the last several years and the gap between what Zillow says and what the house actually sells for is usually in the five to eight percent range. That sounds small until you are talking about a three hundred thousand dollar home and suddenly you are looking at a twenty four thousand dollar discrepancy. The algorithm pulls from public records, recent sales comps, and user submitted data. It does not know that the basement has water damage. It does not know the HVAC was replaced last year unless someone typed it in. It does not see the new roof unless the tax assessor's office caught it. The real work happens when you stop treating the Zestimate as a number and start treating it as a data point you can pressure test. Here is the method I use when I need an accurate figure fast. First, pull the Zestimate for the subject property. Then pull Zestimates for at least five comparable homes within a half mile radius that sold in the last ninety days. Look at the ratio between each comp's Zestimate and its actual sold price. If Zillow underestimated a comp by twelve percent, apply that same directional bias to the subject. If Zillow overestimated another comp by five percent, weigh that more heavily because overestimation tends to happen with poorly maintained homes while underestimation clusters around over-improved properties where the upgrades are not reflected in public records.
I ran into this exact problem last spring on a rehab in the South End. Zillow had the house at four hundred and ten thousand. The after repair value was clearly higher but the estimate would not budge because the automated model had not indexed the finished basement addition. The basement was permitted and on the tax record but Zillow's data aggregator had missed it. I pulled the actual recent sales of similarly finished homes in the neighborhood and found they were trading at roughly fourteen percent above their Zestimates. I applied that adjustment to the subject and landed at four hundred and sixty five thousand. The house sold at four hundred and seventy two thousand a month later. The Zestimate had been off by nearly ten percent. The second step is pulling the county assessor's value and comparing it to Zillow. These two numbers often diverge for reasons that reveal useful information. If the assessor's value is significantly lower than Zillow's estimate, it usually means the property has appreciated beyond the last reassessment cycle. That is a green flag for equity. If the assessor's value is higher, the area may be cooling or the property may have issues the market is pricing out that the assessor has not caught up to yet. CMA substitution is the third layer. You do not need a full appraisal. Run a quick comparative market analysis using active listings, pending sales, and closed sales. Weight them in that order. Active listings show current competition. Pending sales show what buyers are actually committing to. Closed sales are the only hard evidence but they are backward looking. Zillow does not weight pending transactions correctly because it lacks real time contract data. That is a structural gap you can fill manually.
There are situations where this approach breaks down entirely. In newly developed subdivisions with fewer than ten closed sales in the past year, the comp pool is too thin for meaningful ratio analysis. In luxury markets above two million dollars, Zillow's accuracy drops further because the model cannot properly account for non-standard features like pools, guest houses, or waterfront views. In those cases, skip the algorithm entirely and go straight to a licensed appraiser or a local broker CMA. The Zestimate becomes noise rather than a baseline. The fourth step most people skip is checking the zestimate change history. Zillow tracks how the estimate has moved over time. A rapid increase in one direction often signals a data update from the county or a wave of recent sales the model just absorbed. If the estimate jumped fifteen thousand in two weeks, something changed in the underlying data. Pull the source transaction or record update and verify it before building your valuation on top of it. Finally, look at the price per square foot derived from Zillow's data and cross reference it against your comp set. This catches outlier properties where the interior livable area may be miscalculated in the public record. I have seen Zillow's model assign a smaller square footage than what actually exists, which artificially inflates the per square foot number and throws off the entire estimate. When that happens, use the confirmed square footage from your own measurement or the local assessor's most recent revision and rebuild the per square foot comparison from scratch.
Get the Full Details
None of this replaces a professional appraisal when you are refinancing or litigating. But for quick decision making, offer pricing, and portfolio monitoring, combining the Zestimate with manual comp ratios, assessor comparisons, and pending sale adjustments will consistently land closer to the final sale price than relying on the algorithm alone.