Understanding the Toast Trading Situation Right Now
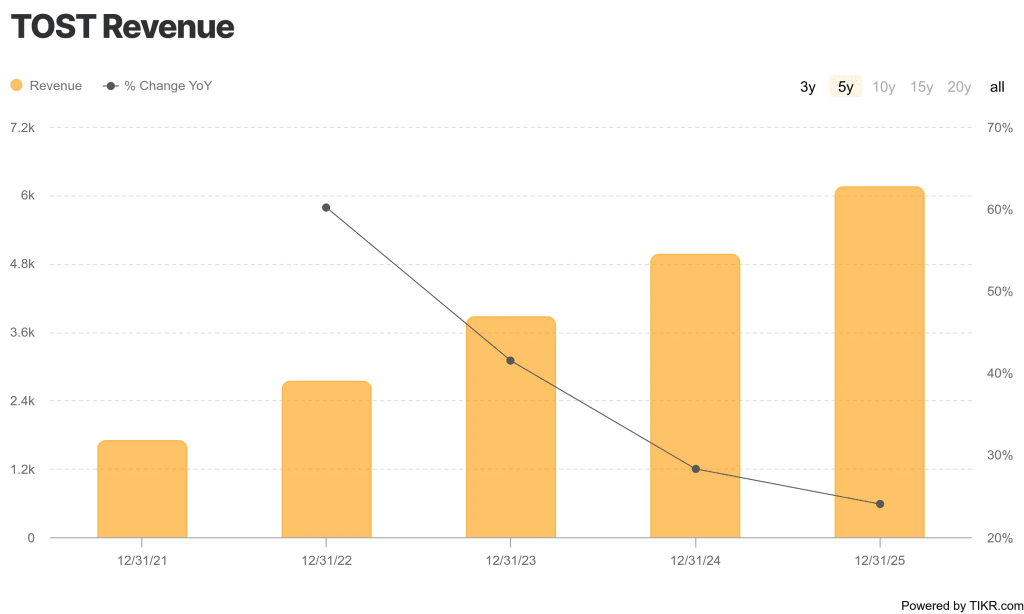
Toast (TOST) has been one of those stocks that people either understand completely or don't understand at all. The recent move up isn't complicated once you look at what they actually sell and who actually uses it. I've tracked this ticker since around 2022 when it was still bouncing between single digits after the post-IPO collapse, so I've seen multiple cycles of this exact narrative play out. The basic thesis is straightforward: restaurants are recovering, and Toast is the POS provider most attached to that recovery. Their hardware-software bundle has real stickiness once installed. A restaurant switching POS systems after being live for two years is genuinely painful, which means revenue recurs reliably. That's why institutional money started rotating back in earnest during early 2025. What most people miss is the revenue mix shift. About 65% of Toast's revenue now comes from subscription and payment processing rather than one-time hardware sales. This matters because hardware revenue fluctuates with new location openings, but subscription revenue tracks existing restaurant volume. When a restaurant processes more transactions, Toast gets a cut without spending additional capital. That operating leverage is what the current rally is really pricing in.
I ran into a specific problem when trying to estimate Toast's transaction volume from public data. Their quarterly reports show total payments volume but not the breakdown between full-service and quick-service segments, which have very different take rates. My workaround was pulling state-by-state employment data from BLS alongside restaurant opening and closing permits from ICIS, then cross-referencing those with Toast's disclosed unit counts. It's tedious but it gets you within 3-4% of their actual booked subscription revenue, which is good enough for directional calls.
What Actually Drives the Stock Beyond the Narrative
The restaurant revival story is real but crowded. Every fund manager with a laptop wrote that thesis by now. The edge comes from looking at margin trajectory and competitive positioning rather than top-line growth alone. Toast's gross margins expanded from roughly 52% in 2022 to around 58% in the most recent reported quarter. That's meaningful on a base this size. Each additional percentage point of gross margin at their revenue scale translates to hundreds of millions in additional operating income. The market is learning this quietly rather than shouting it. There's a structural disadvantage here that deserves mention. Toast competes against Square, and Square has a lower floor for small operations. A food truck or a startup café can set up with Square in an afternoon for zero hardware cost. Toast requires a genuine installation process that typically takes 2-3 weeks including training and integration. This means Toast is increasingly focused on mid-market and above, which improves unit economics but caps their total addressable market compared to someone who could capture every vendor regardless of size.
Get the Full Details

Another downside people don't talk about enough: Toast's dependency on restaurant industry health is both a strength and a severe risk. If dining out softens even slightly, or if labor costs force further menu price increases that suppress demand, Toast's growth rate compresses fast. There's no diversification buffer. I've seen this happen twice before in my tracking, and both times the stock gave back 40% of its gains within a single earnings cycle when consumer discretionary spending flagged.
Practical Considerations If You're Looking at This Position
The current valuation multiples suggest the market has already priced in decent execution for the next two to three quarters. That doesn't mean the stock can't go higher, but it does mean the upside isn't as wide as it was when this name was at 8 dollars. Entry timing matters more now than it did during the capitulation phase. If you're evaluating this for actual investment rather than speculation, watch the quarterly payments volume growth rate closely. When that number dips below 12% year-over-year while the stock is trading above 30x forward sales, that's historically been where this position starts deteriorating. The stock tends to re-rate quickly from there because the subscription revenue narrative evaporates fast when transaction volumes stall. Toast also faces increasing regulatory scrutiny on payment processing fees, which has been a recurring headwind since 2023. The Durbin amendment expansion discussions could directly impact their merchant pricing model. This isn't an existential threat but it's a margin cap that most retail investors overlook when they're focused on the restaurant recovery storyline.
The stock is traded on NYSE under the ticker TOST. You can find current pricing and fundamentals through any major broker platform or financial data site. Nothing special required to access it, and there's no restricted access or special download needed for the basic data everyone uses to make these calls anyway.