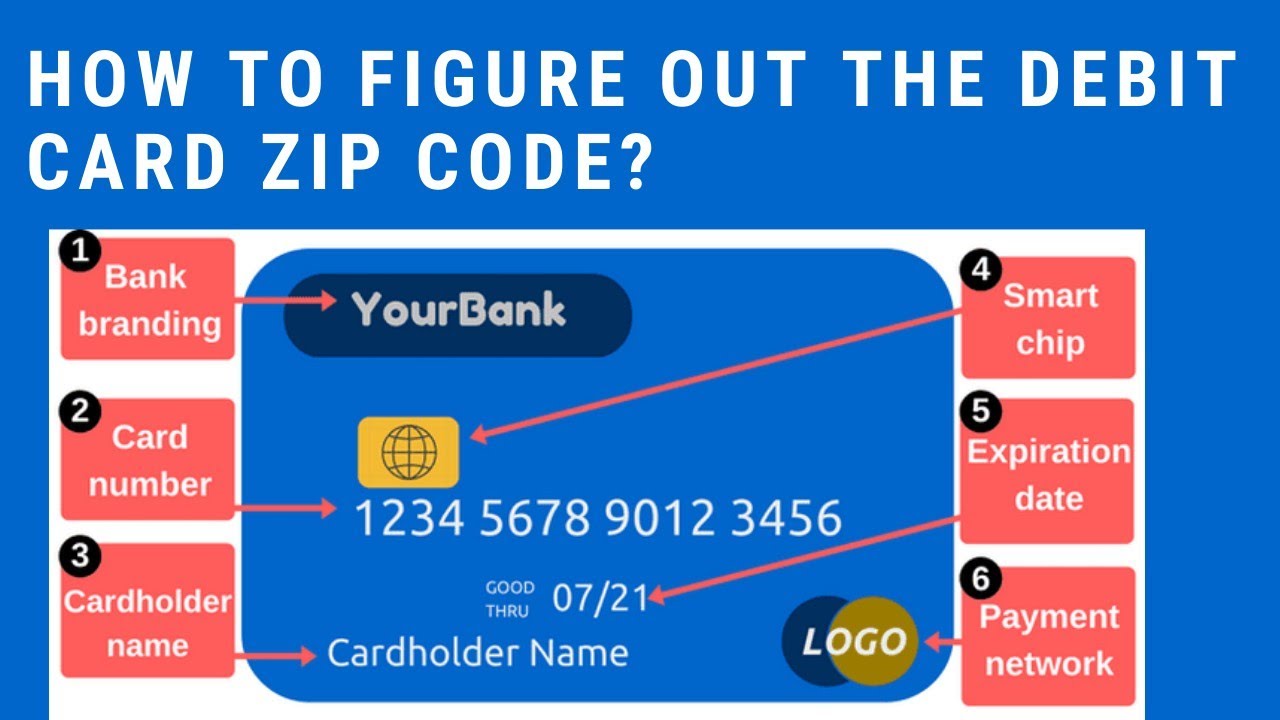
What The Zip Code On Debit Card Actually Does At The Terminal
When you swipe or insert your debit card at a point-of-sale terminal, the system asks for a five-digit number. Most people think they're entering their home address zip code because that's what they were told when they opened the account. They're not. It's a verification code mapped to the card through the payment network, and it functions as a PIN alternative in environments where typing a full four-digit passcode feels clunky or insecure. The entire mechanism runs on something called AVS — Address Verification Service — combined with the card verification value system. When you enter the zip, the merchant's processor sends that data along with the card number and expiration to the issuing bank. The bank checks whether the zip matches what's on file. If it matches, the transaction goes through. If it doesn't, the transaction either gets declined or routed to a manual review queue that slows everything down significantly.
The Zip Code On Debit Card Why It Matters More Than You Think For Security And Convenience
Here's the part most people don't understand: the zip code on your debit card isn't necessarily your current residential zip code. Banks often lock it to whatever zip you provided during the initial account setup, sometimes even years ago. I learned this the hard way in 2019 when I moved from Portland to Austin and couldn't process a single contactless payment at a gas station. The terminal kept rejecting my zip code. I stood there for ten minutes watching three other cars pull up behind me while I frantically tried every zip code I'd ever lived under. Eventually I just paid with cash and went home frustrated. The workaround was simple but ridiculous. I called my bank's support line, waited twenty-two minutes on hold, and had them update the zip code associated with my card. That's it. Two minutes of work on their end and I was unblocked. The lesson here is that your zip code is a living credential, not a static piece of information printed on the card. If you move, change neighborhoods, or even just travel frequently, that mismatch between what the terminal expects and what you're entering becomes a real operational problem. This is why the zip code matters for security: it creates a second layer of authentication without requiring you to memorize another number. A stolen card number alone is useless if the thief doesn't know the zip code tied to it. But this only works if the zip code is actually correct and current. A stale zip code defeats the entire purpose and becomes a liability rather than a safeguard.
For convenience, the system cuts transaction time at checkout. Entering a five-digit zip takes about two seconds. Typing a four-digit PIN takes longer, especially on older terminals with sluggish keypads. Many merchants prefer the zip code flow because it reduces queue times and decreases the number of transactions that stall out due to hardware or user error.
Get the Full Details
How The System Actually Processes Your Zip Code Behind The Scenes
The payment network — usually Visa or Mastercard — routes the zip code through a standardized protocol called the ISO 8583 message format. When you tap or insert your card, the terminal captures the card data and your zip entry, packages them into that message format, and sends it through the acquiring bank to the card network and then to your issuing bank. The issuing bank has a lookup table that maps your card to the zip code on file. It compares the two values and returns an approval or denial code within milliseconds. Most people assume the zip code is checked strictly as an exact match. That's not always true. Some banks implement fuzzy matching logic where a zip code within a certain radius or sharing the same postal prefix may still pass verification. This is particularly common with international transactions or when you're shopping online from a merchant that uses a different billing address format. I encountered this when ordering equipment from a supplier in Canada — my US zip code worked fine even though the invoice was billed to a Canadian address. The issuing bank had pre-approved cross-border fuzzy matching enabled on my account. Not all banks do this. Some enforce strict exact-match policies that cause legitimate transactions to fail when traveling or shopping across borders. If you frequently cross the US-Canada or US-Mexico border, check with your bank about whether their AVS implementation is strict or flexible. The difference can mean the difference between a smooth purchase and a declined card in front of everyone at the register.
Common Pitfalls That People Miss Completely
The biggest issue I see repeatedly is people entering their mailing address zip code instead of the zip code associated with their card. These are often the same, but not always. If you use a postal forwarding service, a PO box, or a mailbox company, the zip on your card might differ from where your mail gets sent. The terminal doesn't care about your mail. It cares about what the bank has on file. Another frequent problem arises with military addresses. APO and FPO zip codes don't follow the standard geographic pattern. Some merchants' payment processors don't handle military zips correctly, and the AVS check fails even when you're entering the right code. I've seen this cause entire orders to get rejected at checkout, not because of insufficient funds or a blocked card, but because the merchant's payment gateway simply doesn't recognize the zip format. There's also the issue of shared household accounts. If you and a family member share a checking account but each have your own debit card, the zip code on file might be one person's address while the other person lives at a different location. The card still works as long as both people enter the same zip code that the bank has registered. But if the bank updates the zip to match one person's current address, the other person's transactions may start failing until they update their profile or switch to a different verification method.
When The Zip Code System Completely Fails And What To Do Instead
Online merchants are the weak point in this whole setup. Many e-commerce platforms don't require a zip code match at all, or they use soft checks that don't actually block the transaction. This means the zip code provides virtually no additional security for online purchases compared to in-person ones. A fraudster who has your card number, expiration date, and CVV can often complete an online purchase without ever being asked for your zip. For online shopping, your actual security depends on whether the merchant supports 3D Secure authentication or similar protocols. These add an extra verification step through your bank, usually via a text message or app notification, that has nothing to do with your zip code. If a merchant doesn't offer this, treat your card information as exposed regardless of what zip code settings you have configured. In physical stores, the system breaks down when the terminal is old or poorly maintained. I've encountered POS systems where the zip code field was disabled entirely, or where the merchant had turned off AVS checks to reduce friction at checkout. In those cases, your zip code literally does nothing. The transaction processes based solely on the card number and expiration date. This is more common at smaller independent businesses that use cheap payment processors or older hardware that hasn't been updated in years.

If your zip code keeps getting rejected at the same location, the problem might not be your information. It could be the terminal's configuration. Ask the cashier to try a different card or a different payment method. If the same error occurs across multiple cards, the terminal or its processor is the bottleneck, not your account.
Practical Steps To Make Sure Your Zip Code Works Correctly
First, log into your bank's online portal and verify the address and zip code currently associated with each of your debit cards. Don't assume it's correct. Banks frequently retain outdated information, especially if you've moved or changed your profile multiple times over the years. Second, if you have multiple cards from the same bank — a checking account card and a savings account card — confirm that they both have the same zip code registered. They should, but I've seen cases where one card was updated and the other wasn't during a routine profile change. Third, test your card at a low-stakes purchase before relying on it in situations where a decline would be problematic. Buying coffee or groceries is plenty of testing. If the zip code entry works consistently, you're good. If it fails, call your bank immediately rather than waiting for an emergency situation to force the conversation.
Fourth, if you travel often, consider enabling travel notifications or international transaction permissions on your cards. Some banks automatically flag transactions that originate outside your registered zip code area as suspicious, even when the zip code itself is correct. This isn't about the zip code verification failing — it's about the bank's fraud detection layer kicking in separately and blocking the transaction before it ever reaches the zip code check. The zip code on your debit card is a small detail that most people ignore until it causes a problem. It's not complex technology, but it's also not trivial. The difference between a smooth checkout experience and a public embarrassment at the register often comes down to whether that five-digit number is accurate and current. Keep it updated. Pay attention when it stops working. And don't assume the system is checking it when it clearly isn't.