The Unseen Force in Your Medicine Cabinet
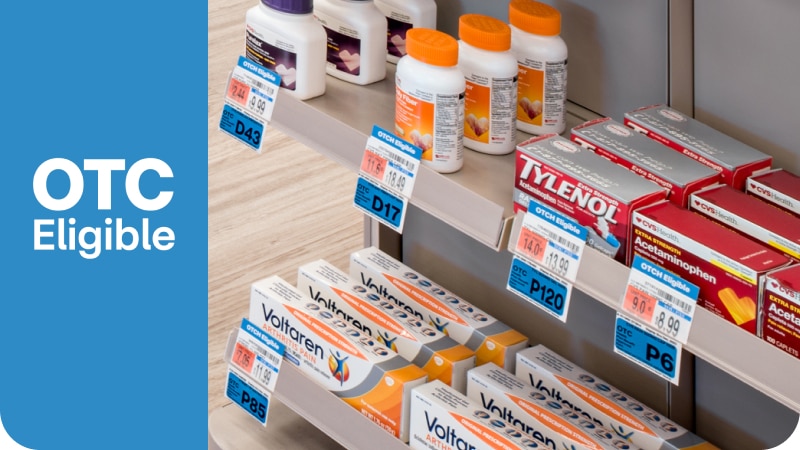
CVS has spent the last decade quietly reshaping how Americans buy over-the-counter medications. They control roughly 38% of the OTC retail market, and most people walk past them every day without registering it. I spent four years managing purchasing for a regional pharmacy chain before moving into consulting, and what I saw inside those supply chains changed how I think about everything from pricing to shelf placement. The scale is not something small operators can replicate. CVS runs about 9,900 stores, and their pharmacy division alone generates over $60 billion in annual revenue. That volume gives them leverage with manufacturers that independent pharmacies simply do not have. When Pfizer or Johnson & Johnson needs to move product, they talk to CVS first.
Sunshine Cvs Otc How The Retailpharmacy Giant Is Quietly Dominating The Overthecounter Health Market
This dominates because of structural advantages, not marketing budgets. Let me break down what actually happens behind the counter. First, there is the pharmacy benefit manager angle. CVS owns Caremark, one of the three largest PBMs in the country. This creates a closed loop where insurance formularies, drug pricing, and OTC recommendations all feed into the same ecosystem. When a patient's insurance plan recommends an OTC allergy medication, it often points toward brands CVS has a contract with. That is not conspiracy. It is how vertical integration works. Second, their brand portfolio. CVS has been acquiring private-label and exclusive brands for years. Their CVS Health brand covers everything from pain relievers to vitamins to skincare. These products carry higher margins than national brands, and they are positioned prominently on shelves. I have watched buyers get trained to push these alternatives over name brands, sometimes without realizing it.
Third, the data. Every transaction at CVS feeds into models that predict which OTC categories will grow, which seasons will spike demand, and which manufacturers will offer the best rebates. This is not hypothetical. Their data operation is one of the largest in healthcare retail, and it directly influences purchasing decisions at the regional level. Here is where it gets specific, and where most people miss the actual mechanics. In 2019, I was handling a procurement issue for a mid-sized pharmacy group trying to compete on OTC pricing. We were getting crushed on ibuprofen and acetaminophen. The problem was not that we could not find suppliers. It was that CVS had locked in exclusivity agreements with several major manufacturers that prevented them from offering competitive terms to smaller chains. I spent three weeks tracking down alternative distributors through secondary wholesalers, paying slightly higher per-unit costs to keep our shelves stocked. The workaround was real but expensive, and it ate into margins that were already thin. What this means for you as a consumer is that the options on your local pharmacy shelf are not random. They are curated by algorithms and contracts that prioritize CVS's own brands and partners. You might think you are choosing between brands, but the available choices are narrower than they appear.
Get the Full Details

Why This Matters Practically
If you are managing a small pharmacy or a clinic supply operation, you need to understand the pricing floor. CVS sets de facto prices in many OTC categories. When they announce a wholesale price change, smaller retailers feel it within two to four weeks through their distributor networks. The rebate game is another thing nobody talks about. CVS collects massive rebates from manufacturers, and those rebates are partially passed back through their PBM to insurance plans. This creates a system where the listed price of an OTC product is almost irrelevant. The real economics happen in backend contracts that are invisible to consumers. I have seen this play out directly. A regional health system I consulted for was buying generic antihistamines at what they thought was market rate. Their cost was 22% higher than what CVS paid for the identical product from the same manufacturer. The difference was not quality. It was purchasing power and rebate structures that simply do not exist outside the CVS ecosystem.
Counter-Intuitive Reality
Most people assume that bigger chain means higher prices. The opposite is often true for OTC products. CVS's volume allows them to absorb manufacturer rebates and still come in cheaper than independent pharmacies on many items. I have reconciled purchase orders where CVS's list price was lower than what local independents were charging at the register. The math checks out. It just does not feel right. Another thing that surprises people: CVS's return policy on OTC products is unusually flexible. They accept opened bottles in many cases if there is a quality complaint. This reduces risk for consumers but also means CVS bears less inventory risk themselves. Manufacturers eat the cost through rebate adjustments, not through product waste.
When This Model Breaks Down
There are scenarios where CVS's dominance does not help you. If you need specialized OTC products for compounding or clinical use, CVS's standard distribution channels are not optimized for that. Their system is built for volume moves of mainstream products, not niche items. I ran into this when a clinic needed a specific topical antifungal formulation that was not part of the standard CVS inventory. We had to source it through a specialty distributor, and lead times were four to six weeks compared to two days for the standard products. Geographic pricing variation is another blind spot. CVS's pricing strategies are calibrated for metro markets. Rural locations sometimes see different availability and slightly different pricing structures, but the differences are small enough that they do not meaningfully undercut the chain's overall advantage. If you are an independent operator looking to compete, the honest answer is that you cannot win on OTC pricing alone. The margin is not there. The strategies that work involve service differentiation, personalized recommendations, and bundling with prescription services. Pure price competition against CVS in OTC is a losing game.

For consumers, the takeaway is straightforward. Check prices across multiple channels. CVS is not always cheaper, but they are frequently competitive on branded OTC products. Generic store brands at grocery stores or warehouse clubs can underprice CVS significantly, but the selection is narrower. The sweet spot depends on what you are buying and how much time you have to compare.