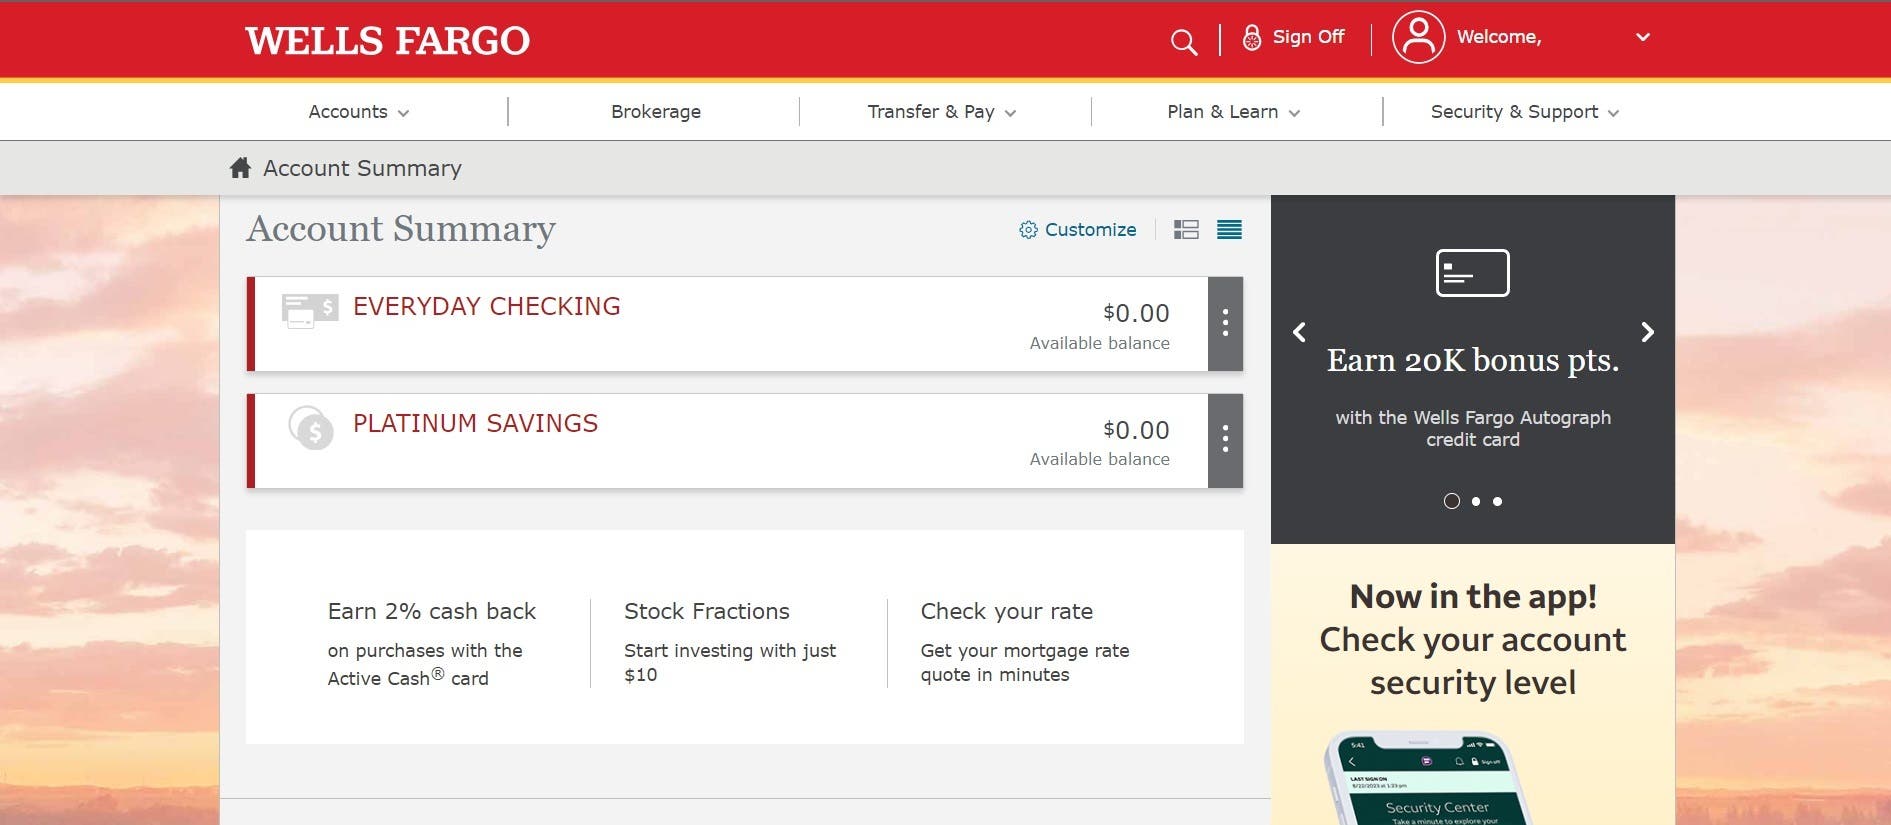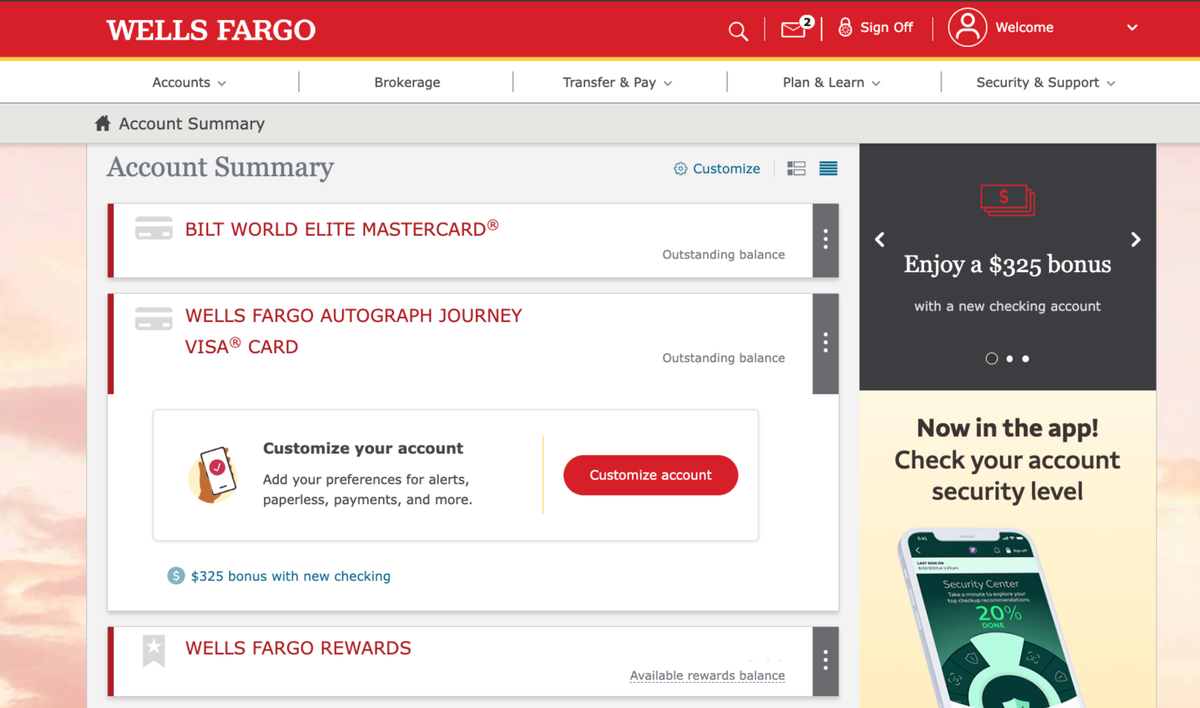
Wells Fargo Online Banking: What Actually Works And What You Should Know Before Using It
Most people sign up for online banking because they don't want to stand in line at a branch on a Friday afternoon. That's fair enough. Wells Fargo's platform has been around long enough that some parts of it feel like they were designed by committee in 2008 and nobody ever updated them. I've been managing my own finances through Wells Fargo Online for several years now. The good stuff is genuinely useful. The bad stuff is... well, you'll see.
The Ultimate Guide To Wells Fargo Online Features Benefits And Security Insights
Getting Set Up Properly
Download the Wells Fargo mobile app from your phone's official app store. Go to the website directly if you're on a desktop. Do not click any links sent to your email or phone claiming to be from Wells Fargo. That sounds obvious, but phishing attempts targeting Wells Fargo customers are among the most common in the industry. They always look convincing because they use the actual branding. When you register, you'll need your account number and Social Security number handy. Set up multi-factor authentication immediately. I know it's annoying to enter a code every time you log in from a new device, but skipping this step is how people lose access to their accounts. The app will ask you to verify your phone number and email. Do both. There's a setting under "Security" where you can manage which devices are recognized. Review that list quarterly. If you see something you don't recognize, call the number on the back of your debit card right away.
Features That Actually Save You Time
The bill pay system is the part most people find useful. You can set up recurring payments for utilities, rent, car payments, everything. When I moved to automating twelve different bills through the platform, I stopped missing a single payment for about eighteen months straight. That alone prevented two late fees and kept my credit score from dipping. Mobile check deposit works reasonably well. You photograph the front and back of a check, enter the amount, and it deposits within one business day in most cases. The catch is that checks over a certain threshold might get flagged for manual review. I learned this the hard way when I deposited a $4,200 settlement check and it sat in pending status for four days instead of the usual next-day turnaround. The workaround was calling customer service and verifying the check details verbally. They manually approved it that same afternoon. The transaction alerts feature is probably the most underutilized tool available. You can set up custom notifications for transactions above a certain dollar amount, deposits, withdrawals, even when your balance drops below a specific threshold. I run alerts on anything over fifty dollars. It caught a fraudulent charge on my card within twenty minutes of it happening. That speed matters more than people realize.
Get the Full Details
What About The Security Side Of Things
Wells Fargo uses 256-bit encryption, which is the industry standard. They also have fraud monitoring systems that run continuously. The problem isn't usually that the technology fails. It's that customers don't understand how to use the security tools properly. The lock feature on your debit card is one example. If you misplace your card, you can freeze it instantly through the app. This prevents any new transactions from going through while you figure out what happened. I lost my card at a grocery store once and had the replacement ordered within forty minutes. Without that lock feature, I'd have been waiting on hold with a representative for potentially an hour before anything got resolved. Watch for unusual activity reports. Wells Fargo sends these periodically through the app and via email. They're not just formalities. A few months ago I got a notification that my account was being accessed from an IP address in a city I'd never visited. I hadn't shared my password with anyone, but the alert prompted me to change it anyway and review my recent transactions. Nothing was compromised, but it was a reminder that automated monitoring can catch things you might otherwise miss.
Pain Points You Should Expect
The interface hasn't changed dramatically in years. Navigation feels cluttered compared to newer banking platforms. Finding specific features sometimes requires clicking through multiple menus. The search function within the app is basically nonexistent. If you're looking for a particular transaction from three months ago, expect to scroll or use the date filter, which is buried under the "Activity" tab. Customer service through the app can be hit or miss. The chat feature exists, but representatives often seem to be reading from scripts. For straightforward issues it's fine. For something complicated like a disputed charge that's been ongoing for weeks, you're better off calling directly. The wait times vary depending on the time of day and day of the week. Early Tuesday mornings tend to be the least crowded. There's a known limitation with international transactions. If you're traveling outside the United States and plan to use your card, you need to notify Wells Fargo beforehand. They flag overseas activity as potentially fraudulent, which means your card could get temporarily blocked at the point of sale. Setting a travel notice through the app takes about thirty seconds and prevents that headache entirely. I missed this once in Canada and spent twenty minutes on hold at an ATM before a representative manually verified my trip and reactivated the card.
Advanced Tips Most People Don't Know About
You can link external accounts from other financial institutions to Wells Fargo Online for consolidated viewing. This doesn't give you the ability to manage those accounts, but it does let you see your total net worth in one dashboard. The linking process uses Plaid's verification system, which is generally reliable but occasionally fails when the other institution has unusually strict login requirements. The Zelle integration is built directly into the platform. Sending and receiving money between Wells Fargo accounts is instant. Transfers to accounts at other participating banks typically complete within minutes during business hours. There's a limit of $2,500 per transaction for standard accounts, and the daily sending cap is $2,000. If you need to move larger amounts, you'll have to use a wire transfer instead, which comes with fees and longer processing times. There's a feature called "SafePass" that generates one-time passwords for when you're logging in from a new device. It's separate from your regular two-factor authentication. Some people find it redundant. I've found it useful in situations where my phone battery died and I couldn't receive a text message code. SafePass codes are stored in the app and don't require cellular service to access.
The Downsides Nobody Talks About
The fee structure is where things get complicated. Wells Fargo has a variety of account types, and the monthly maintenance fees vary significantly. The Advantage Plus Banking account charges $12.95 per month unless you meet certain criteria like maintaining a minimum daily balance or having qualifying direct deposits. That's not uniquely bad compared to other major banks, but it's easy to overlook if you're not paying attention to the fine print. Overdraft protection isn't automatic. If you don't set it up and your account goes negative, the fees add up quickly. Wells Fargo charges $35 per overdraft item, and there's no limit to how many they'll assess in a single day. I've seen people get hit with multiple fees on the same transaction when it processes in stages. Setting up a link between your checking and savings accounts as overdraft protection costs nothing and prevents this scenario entirely. The online-only experience has real limitations. Certain products, like notary services or safe deposit box access, still require an in-person visit. Cash deposits at branches have daily limits unless you have additional verification set up. If your primary banking needs involve large cash transactions, you might find the digital tools insufficient for your day-to-day operations.
Bottom Line On Whether It's Worth The Effort
Wells Fargo Online gets the job done for everyday banking. The core features work as advertised. The security tools are solid if you actually use them. The interface is dated but functional. The main drawbacks are navigation friction and occasional customer service delays during peak times. If you're someone who values automation and set-it-and-forget-it banking, this platform delivers on that promise. The bill pay, mobile deposit, and alert systems all reduce the mental load of managing finances. If you prefer a more modern, streamlined experience, you might find other banks more appealing. There's no objective wrong answer here, only what fits your habits. The one thing I'd emphasize is getting comfortable with the security settings before you need them. Most people don't think about fraud monitoring or account lock features until something goes wrong. Setting up your alerts, reviewing your authorized devices, and understanding how to freeze your accounts takes about ten minutes and could save you hours of stress later.