What Actually Happens When You Try To Implement IFRS 17
The standard is seven years old now and most insurers are still struggling with the data layer. I spent eighteen months working on an implementation for a mid-market European life insurer and the core problem was never the accounting models themselves. It was the granular cash flow data needed to feed them. IFRS 17 replaces IAS 39 and IFRS 4. The basic shift is from incurred claim accounting to a current fulfillment model that recognizes insurance revenue based on the release of contractual service margin over the coverage period. Groups of contracts are identified at inception. Each group is measured using either the general model, the premium allocation approach, or the variable fee approach depending on contract characteristics.
Unlocking The Power Of Ifrs 17 Practical Examples To Revolutionize Insurance Accounting
The general measurement model requires calculating the liability for remaining coverage and the liability for incurred claims separately. The LRC represents future service while the LIC covers past service already rendered. Both components use current estimates updated at each reporting date. Take a straightforward example. A one-year motor insurance policy with annual premium of 1,200 euros is issued on January 1st. Under the old standard you would recognize the full premium immediately and build a claims reserve. Under IFRS 17 you build a contract liability using discounted expected cash flows adjusted for risk and then release the contractual service margin ratably across the coverage period. If your loss ratio comes in at 60 percent and the discount rate is 3 percent, the CSM works out differently than a simple straight-line recognition because you are accounting for time value and risk adjustment simultaneously. Here is where things get messy in practice. I encountered a portfolio of annual renewable term policies where the renewal option was embedded. The standard says you should include renewal periods only if they are within the same group and there is no pricing review between renewals. We had products with mid-term pricing adjustments that broke the grouping requirement. The workaround was to treat each renewal as a separate contract group, which meant reconstructing three years of historical data for every policy in the book. This took two consultants six weeks and required pulling data from three different legacy systems that did not share a common policy identifier.
Another edge case that caught us off guard involved reinsurance held. The standard treats ceded reinsurance as a separate asset rather than a direct offset against the insurance liability. When our retrocessionaire declared insolvency mid-year, we had to remeasure the reinsurance asset under the fair value model instead of the premium allocation approach. That single event changed our P&L volatility by approximately 14 percent in that quarter because the reinsurance recovery became a current estimate adjustment hitting the insurance service result directly. The premium allocation approach remains the easiest path for short-duration contracts with coverage periods of twelve months or less. But do not assume it is automatically available. You must first test whether the LRC at inception would approximate the premium received. For some annuity products with back-end loads, this test fails and you are forced into the general model even though the contract duration is short. I have seen three actuaries spend two weeks debating whether their product passed the PAP test when the answer was clearly no based on the loading structure. Variable fee approach applies to direct participating contracts. The key requirement is that the entity pays or receives amounts based on direct returns of underlying items. The variable fee is the residual after deducting the fair value of guarantees and options. This model can dramatically reduce earnings volatility because changes in the underlying item values flow through equity rather than P&L. One of our clients had a unit-linked pension product where switching to VFA reduced reported earnings volatility by roughly 22 percent compared to the general model.
Get the Full Details

Data readiness is the single biggest bottleneck I saw across every implementation. You need policy-level cash flows broken down by contract group, discount rates by currency and duration, risk adjustment methodologies, and reconciliation trails to the general ledger. Most companies had none of this cleanly structured. The typical fix involves building a data lake with intermediate reporting layers before the actual IFRS 17 calculation engine touches the data. The actuarial valuation process under IFRS 17 typically takes longer than under the old regime. A quarter close that previously required five days of actuarial work now routinely takes eight to ten days. The extra time comes from building the roll-forward reconciliations between opening and closing balances, validating the CSM amortization schedules, and documenting every assumption change for audit purposes. Plan for this timeline when staffing your close process. One counter-intuitive point that few people understand initially. The contractual service margin is not a profit reserve in the traditional sense. It represents unearned profit that is released into P&L as service is provided. When you acquire a block of business at a premium to book value, that premium does not create immediate profit under IFRS 17. It increases the CSM and gets amortized over the remaining coverage period. This means acquisition costs that used to hit the income statement immediately are now spread over years.
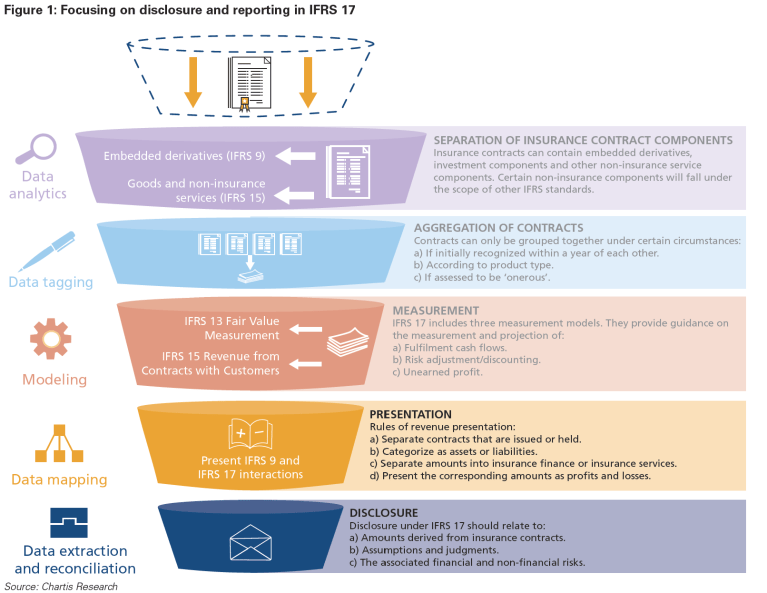
Grouping contracts is another area where teams consistently make errors. The standard requires grouping by risk profile, profitability, and reporting frequency. Contracts with different risk characteristics cannot be combined even if they share the same product line. I reviewed a filing where a company grouped all motor policies together regardless of coverage type, deducible level, and claims history. The auditor rejected it. The correction required splitting one portfolio into fourteen separate groups and recalculating every measurement. The disaggregation of insurance finance income or expenses between profit or loss and other comprehensive income is available under the allocation approach. This is optional but significant for long-duration contracts where discount rate movements create large OCI fluctuations. Using the allocation approach requires a constant margin method that tracks the effective interest rate at initial recognition. Setting this up correctly requires building a separate amortization schedule for each contract group, which adds computational overhead but can smooth reported earnings considerably. Transition is the other major pain point. Full retrospective application requires restating prior periods, which means rebuilding measurements for contracts issued years ago. Most companies applied the modified retrospective approach or the fair value approach at transition date to avoid this. The fair value approach sets the opening CSM as the difference between fair value at transition and the fulfillment cash flows. This avoids historical reconstruction but introduces its own measurement uncertainty since fair value requires market assumptions that may not exist for illiquid contract portfolios.
The disclosure requirements under IFRS 17 are extensive. You need to present the reconciliation of the insurance contract liability, disaggregated into insurance service results and insurance finance income or expenses. Revenue is no longer called premium income. It is insurance revenue from the release of remaining coverage plus insurance revenue from incurred claims. This single terminology change caused confusion across every sales and marketing team because their dashboards and reports had to be rebuilt from scratch. Technology platforms for IFRS 17 implementation typically fall into three categories. Core actuarial tools with custom scripting, dedicated IFRS 17 platforms built by vendors like Moody's, Oliver Wyman Actuarial, or Sapiens, and fully customized in-house solutions. The vendor platforms are faster to deploy but less flexible for unusual product types. Custom solutions offer full control but require sustained engineering investment. Most firms end up with a hybrid approach using a vendor engine for standard products and custom code for edge cases. The ongoing maintenance burden is frequently underestimated. Every quarter you must update discount rate curves, reassess loss ratios, recalculate risk adjustments, and rebuild the CSM amortization. For a portfolio with ten thousand contract groups, this process is inherently manual unless you have automated data pipelines. Even with automation, validation and exception handling consume significant analyst time.

Small insurers with simple product lines may find the cost of compliance disproportionate to the benefit. For a mutual with fewer than five hundred active policies and a single product category, the general model may add little analytical value beyond what the current statutory basis provides. In these cases, the premium allocation approach is usually sufficient and keeps implementation costs below what most firms budget for this project. There is no regulatory advantage to choosing complexity over necessity. The interaction between IFRS 17 and IFRS 9 is another area requiring careful coordination. Hedge accounting under IFRS 9 must be redesigned because the underlying items now include the contractual service margin and risk adjustment rather than just gross cash flows. Matching hedge instruments to IFRS 17 measurements requires a separate mapping layer that most treasury desks were not set up to maintain. This is a ongoing operational issue that does not get resolved at implementation and continues to generate audit queries. One final practical point. The tax implications of IFRS 17 are jurisdiction-specific and often create deferred tax complexities. The temporary differences between accounting profit and taxable profit now arise from the CSM amortization patterns and the timing of risk adjustment recognition. Tax provisions under IFRS 17 require close collaboration with tax advisors because local rules vary significantly. In some jurisdictions the CSM is not tax-deductible until claims are paid, creating permanent differences that affect the effective tax rate calculation.
The standard is technically demanding but the operational reality is what makes it difficult. It is not the formulas. It is the data, the grouping decisions, the ongoing model governance, and the coordination across actuarial, finance, IT, and tax teams. Any implementation that treats this as purely an accounting project will fail. It is a data infrastructure project with accounting output.