What DailyPay Actually Does
DailyPay is an earned wage access platform. Your employer partners with them, and you can withdraw money you have already worked and earned before the regular payday hits. The mechanism is straightforward: your hours or salary accrue throughout the pay period, DailyPay tracks that balance in real time, and you tap a button in the app when you need cash. No interest charges on the standard transfer. Faster transfers cost a small fee, usually under a dollar. I spent three years managing payroll integrations for a mid-sized logistics company. We rolled out DailyPay across two facilities. Most people used it without incident. About 15 percent had questions every month, and roughly 3 percent of those cases required manual intervention because of edge cases in how the system calculated available balances during state-specific payroll cycles.
The Ultimate Guide To Dailypay Login Unlocking Financial Flexibility For Employees
Setting Up Your Account
You do not create a DailyPay account from scratch on your own. The employer has to enable it first. Once that happens, you get a link via email or through your company's payroll portal. Click through, enter your personal details, and connect your bank account. That is the banking integration step where most people hit a snag. The bank connection uses Plaid. If your bank is not on Plaid's supported list, you enter routing and account numbers manually instead. I learned this the hard way during the rollout. One of our warehouse supervisors has a credit union that Plaid does not support. He spent twenty minutes trying to connect through the app before I told him to scroll down and use the manual entry option. He was frustrated because the manual option is buried near the bottom of the setup page. After your bank account is linked, you verify your identity. This usually involves a Social Security number check and sometimes a photo ID upload. The verification clears in seconds if your information matches what the payroll system has on file. If there is even a slight mismatch — a name with a middle initial that is different between your driver's license and your W-2 — the system flags it. You resolve it by contacting the support queue, which takes about two business days.
Logging In After Setup
Once everything is verified, logging in is just an email and password. You can also set up Face ID or fingerprint login on the mobile app. The web portal does not offer biometric login. That limitation matters if you are constantly pulling up your available balance from a desktop at work, but most employees use the phone. Sometimes people lose access. Common reasons: a password reset triggered by too many failed attempts locks the account for fifteen minutes, a new device requires re-verification, or the employer changes the payroll provider and the integration resets. If you hit any of these, you do not need to start over. The reset path sends a recovery link to your registered email. Check your spam folder — the link ends up there about a third of the time.
Get the Full Details

How the Balance Works
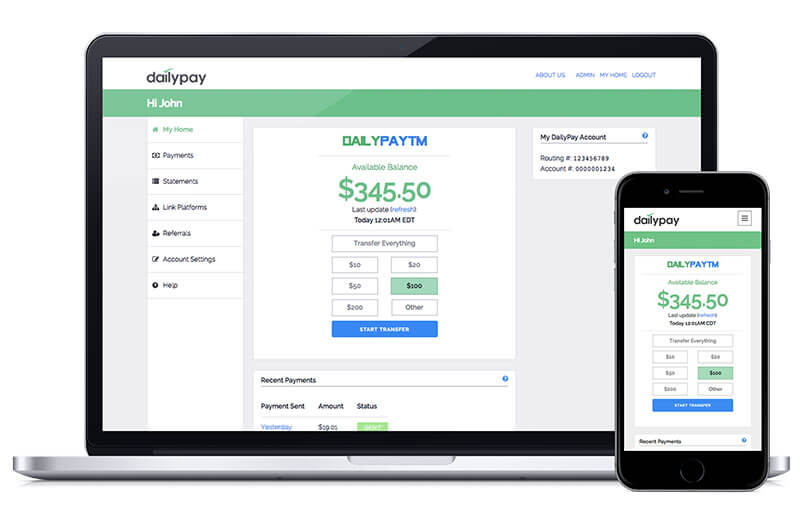
This is where people get confused. DailyPay does not give you your full paycheck early. It gives you access to what you have already earned up to that moment. If you are paid biweekly at twenty dollars an hour and you have worked three days of a forty-hour week, your accessible balance is roughly one hundred and twenty dollars, not your full weekly check. The accrual engine matters here. Different employers use different accrual methods. Some track by the hour in real time. Others update once per day at midnight. A few only refresh when a new shift is checked in. During my time managing the rollout, I watched three employees complain that their DailyPay balance had not changed despite working overtime the day before. Their company used an end-of-day accrual refresh, so the balance would not show the new hours until midnight. They assumed the system was broken. It was not. Another nuance: some employers cap the percentage of your earned wages you can access. It is common to see caps at 50 or 75 percent of what you have earned. Check your employer's settings. The cap is not a DailyPay decision. It is an employer configuration. You will see it listed in the app under account settings or the help section, though the wording varies.
Transfer Options and Timing
There are generally two transfer speeds. Instant transfer hits your linked debit card in minutes, usually under five, and costs between one and three dollars per transaction. Standard transfer takes one to two business days and is free. Most people default to instant without realizing the fee, then complain about it on message boards. It is worth checking the fee before you confirm each withdrawal if you are doing multiple transfers in a short period. The fees add up. I had a case once where an employee set up automatic transfers to their bank every day. They were paying roughly two dollars a day in instant transfer fees. That is over five hundred dollars a year if they kept it up. I flagged it when I noticed the pattern in the support tickets. They switched to weekly standard transfers and saved most of that. The money was still available when they needed it. They just had poor timing awareness.
Common Problems and Workarounds
The system occasionally shows a zero balance even when you have worked that day. This is almost always an employer sync delay. The payroll system sends hourly data to DailyPay on a batch schedule, and that schedule varies. If your employer processes payroll at 5 PM, your DailyPay balance might not reflect hours worked before that cutoff until the next morning. Work around it by requesting transfers after the sync window, or accept that you will have a slight lag during the day. Sometimes the app crashes during the bank connection step. This happens more often on older Android devices. The workaround is closing the app completely and reopening it, then starting the connection flow again. Do not try to pause and resume — it rarely works. A full restart clears the session cache that causes the crash. A more serious issue: your balance shows correctly but the transfer fails with an error about insufficient funds. This means the amount you are trying to access exceeds your available balance after any pending holds or employer-imposed limits. Check the available balance number, not the total earned number. They can differ if you have a hold on a recent transfer or if your employer applies a buffer limit. The app usually displays both numbers side by side if you expand the balance detail.
Privacy and Data
DailyPay shares data with your employer, but only aggregated information. They report participation rates and aggregate usage statistics. They do not share individual withdrawal amounts with your manager. This is a common fear, and it is mostly unfounded. The employer sees that you have an active account and a general utilization rate if they have opted into those reporting features. They do not see when you withdrew money or how much. That said, DailyPay does collect a significant amount of personal financial data. Banking details, identity verification documents, transaction history. If you are uncomfortable with that data footprint, you can delete your account at any time through the app settings. The deletion process removes your banking info and transaction history within thirty days. The employer's participation record may persist for audit purposes, but your personal data is cleared.
Who Should Use It and Who Should Not
DailyPay works well for people who have irregular cash flow and want to smooth out the gaps between paychecks. If you are living paycheck to paycheck and occasionally need access to money you have already earned, the standard transfer option is essentially an interest-free bridge. The instant transfer fee is reasonable if you use it sparingly, maybe once or twice a month at most. It is less useful if you rely on it as a regular source of credit. The fees accumulate, and the psychological effect of having easy access to your wages can lead to spending money before it is actually deposited into your account. I saw this play out with a few employees during the rollout. They used instant transfers twice a week and quietly ate up the fees without noticing. The system does not warn you about cumulative costs. You have to track that yourself. If your employer does not offer it, you cannot sign up independently. There is no public registration. The platform is B2B2C, meaning the employer is the gatekeeper. Some employees confuse this with a personal fintech product and spend time looking for a sign-up page that does not exist. The only path is through your employer's benefits or payroll portal.
A Few Things the Support Pages Do Not Mention
International workers on H-1B and similar visas sometimes run into issues because the identity verification step requires a SSN or ITIN that is not yet issued. The system will reject the verification, and the workaround is to complete the account setup with whatever identification is available and contact support directly. Processing takes longer, but it is doable. Most agents know the procedure after the third or fourth ticket like this in a week. Another detail: DailyPay does not report to credit bureaus. Withdrawals are not loans. They are advances on wages you have already earned. This means using the service has no impact on your credit score, positive or negative. It also means you cannot use your DailyPay history as part of a credit building strategy. Some people assume it functions like a secured card or a reportable loan. It does not. If your employer offers multiple payroll providers — which happens with acquisitions or subsidiary structures — your DailyPay account may not sync across all of them. I encountered this when a client merged two companies with different payroll systems. Employees who worked across both entities saw split balances. The fix was contacting support to consolidate the accounts manually. The process took about four business days and required proof of employment with both entities.

The app also does not support joint accounts or shared banking profiles. Each account is strictly individual. If you and a spouse both work for the same employer, you each get your own account. There is no family or household view. Some employees ask for this feature, and it simply does not exist. One more thing that trips people up: tax withholding. DailyPay withdrawals are subject to the same tax withholdings as your regular paycheck. The amount you see as available is your gross earned wage minus the estimated withholdings your employer has configured. If you pull more than your net pay for the period, the system blocks it. You cannot withdraw money that has not yet been cleared through the withholding calculation. This is a safeguard, not a bug, but it catches people off guard when they expect to see their full hourly earnings as available.