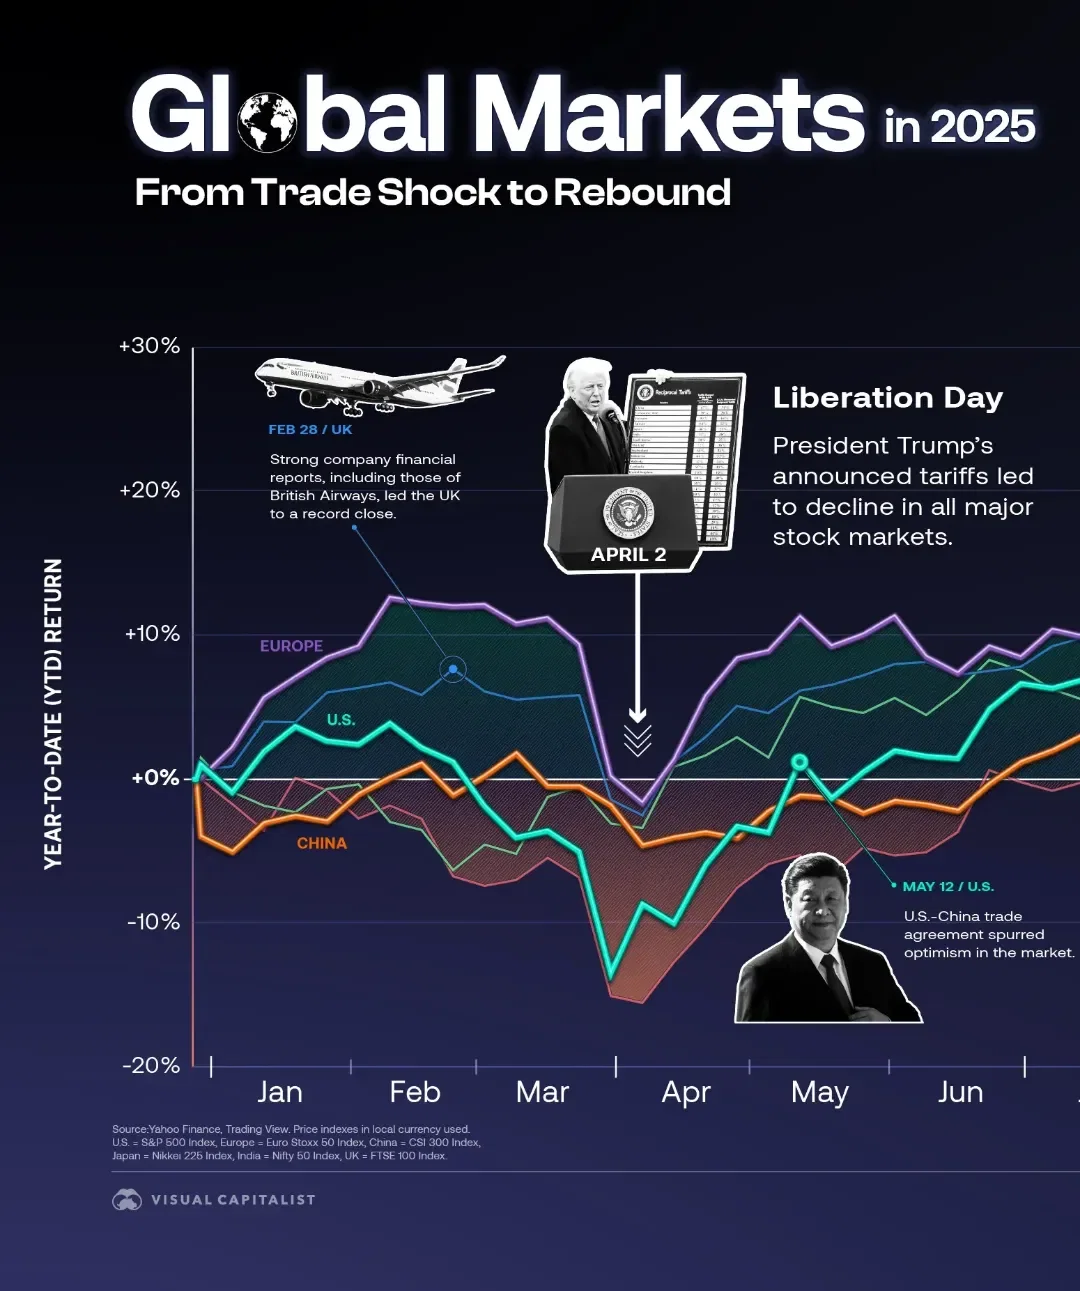
Up And Down Market Trends 2024 Navigating The Ups And Downs Of Global Economy
Samantha
2026-08-13
Understanding How Up And Down Market Trends Actually Work In Practice
Market trends are not what most people think they are. They are not predictable paths driven by fundamentals. They are positioning cycles created by the interaction of leverage, risk appetite, and liquidity flows, moving in ways that often contradict the actual state of the economy.
I spent years watching professional portfolios blow up during what looked like textbook trend scenarios. The lesson was brutal but simple: trends are fragile structures built on consensus expectations, and they break the moment that consensus shifts faster than positions can adjust. What matters is not predicting the direction but understanding the mechanics of how the cycle forms and where it typically stalls.
Methodology For Managing Exposure During Volatile Periods
The practical approach involves duration management rather than directional timing. Most traders lose money because they hold positions through volatility with the same sizing they used during calm periods. The adjustment happens on the way out, not before the move.
I use a straightforward process: define the market regime first, size the position based on realized volatility rather than expected volatility, then set a hard exit rule that does not depend on whether the trade makes sense emotionally. A position that was correctly sized at entry will still fail if held past the point where the thesis loses power. The exit rule removes the decision entirely.
The core metrics I track are not price or P/E ratios. They are cross-asset correlation shifts, implied versus realized volatility spreads, and the pace at which central bank communication diverges from market pricing. When implied vol is compressing while realized vol is already expanding, the market is pricing in calm that is not there. That mismatch is where the biggest opportunities appear, and where the biggest losses accumulate for traders who ignore it.
Up And Down Market Trends 2024 Navigating The Ups And Downs Of Global Economy
2024 introduced a specific complication: central bank policy divergence became the dominant force rather than a background factor. The Fed held rates at elevated levels while the ECB moved toward easing, and emerging market central banks split between cutting aggressively and holding firm to defend currencies. This created a market environment where traditional diversification broke down.
What worked in previous cycles stopped working. Low correlation between stocks and bonds disappeared. Safe-haven flows moved unpredictably. Currency moves erased un-hedged equity returns before any equity selection could matter.
I encountered a specific problem in March 2024 where a quantitative model I was using flagged a clean upward trend in European equities based on traditional momentum signals. The model did not account for the currency overlay. The euro weakened sharply against the dollar before the trade moved, turning a 4 percent equity gain into a net loss once hedging costs and translation effects were included. The workaround was simple but unpopular: add a mandatory currency stress test to every equity position where the base currency and the market currency differ by more than 8 percent over a 30-day window. It killed about 15 percent of the signals the model generated, but it also eliminated the category of loss that was quietly destroying returns.
Where This Approach Fails Completely
No methodology works in every environment. The duration management framework I described becomes unreliable during sharp liquidity shocks where position sizing rules are overridden by margin calls and forced liquidations. In those moments, all correlation goes to one, and the only thing that matters is whether you entered with enough dry powder to survive the move rather than whether your thesis was correct.
This approach also fails in sideways markets with low volatility. When there is no trend to manage and no volatility expansion to size against, the constant monitoring and rebalancing become net drags on returns. A static allocation often outperforms an active duration strategy in flat environments. I stop applying this framework when the VIX stays below 14 for more than 60 consecutive days. That is when I shift into a simple buy-and-hold posture and avoid the temptation to trade a market that gives no edge.
Practical Positioning Rules That Actually Work
The specific rules I follow are straightforward. First, I never size a position larger than 2 percent of portfolio value unless the trailing 30-day realized volatility is below the 12-month average. Second, I reduce exposure by half on any asset that hits its Bollinger Band lower or upper boundary within a single session after a period of compression. Third, I do not add to losing positions in trending markets. Adding to losers works in mean-reversion strategies, not in trend environments.
I also avoid the common trap of thinking that more information improves decision quality. Most traders gather additional data after the position is already established. This creates confirmation bias, not better timing. The extra information rarely changes the outcome.
The 2024 environment required one additional adjustment. Standard backtests based on 2010 to 2019 data significantly overestimated the reliability of trend-following signals because that period was dominated by low rates and high liquidity. I recalibrated my models using data from 2022 to 2024 and reduced the weight of momentum signals by roughly 30 percent. The shift was small but necessary. Markets in the post-zero-rate era behave differently, and strategies built on the old environment underperformed until the calibration was updated.
A Hard Lesson From Personal Experience
In early 2024, I held a concentrated position in a commodity-linked currency that appeared to have a strong upward trend based on all standard indicators. The trend was real. The direction was correct. The position still lost money because I ignored the roll yield structure on the underlying futures contracts. The commodity was in steep backwardation, meaning the nearest contract was worth significantly more than deferred contracts. As each contract rolled forward, the position lost approximately 1.2 percent per month to the roll cost. Over 18 months, the roll drag erased nearly 22 percent of the total return before the trend itself even reversed.
The lesson was expensive but memorable: trend analysis without contract structure awareness is incomplete analysis. I now run a mandatory roll yield check on every commodity or currency exposure before entering, and I avoid rolling into backwardated markets unless the trend strength more than compensates for the drag. The rule is simple. If the annualized roll cost exceeds 4 percent, the trend needs to be above 12 percent annualized to justify the trade. Anything below that threshold loses money even if the direction is right.
The Counter-Intuitive Reality About Market Trends
The most important insight is also the hardest to accept: successful navigation of market trends is mostly about avoiding catastrophic errors rather than making brilliant predictions. Most underperformance comes from a small number of oversized mistakes during volatile periods, not from missing the right calls. The traders who last are not the ones who predicted the turns. They are the ones who survived the periods where prediction was impossible.
This means the priority should be building processes that protect against ruin before optimizing for gain. Risk management is not a secondary concern. It is the primary mechanism through which returns are preserved. Everything else is decoration.
I recommend a simple checklist for anyone managing exposure during up and down periods: verify the volatility regime before sizing, confirm the contract or currency structure before entering, and accept that missing a trend is cheaper than surviving one incorrectly. The market will always be there tomorrow. A blown account is harder to recover from.
Gallery Up And Down Market Trends 2024 Navigating The Ups And Downs Of Global Economy
2025 in Review: The Ups, Downs, and Returns of Global Markets - Voronoi
Navigating the Currents: Economic Trends and Market Insights for 2024
Visual representation of global economic trends for 2024-2025 ...
2024 Market Trends: Opportunities in Global Shifts
Premium Photo | Graphs representing ups and downs Financial market ...