Getting Form 8962 Right Without Losing Your Mind
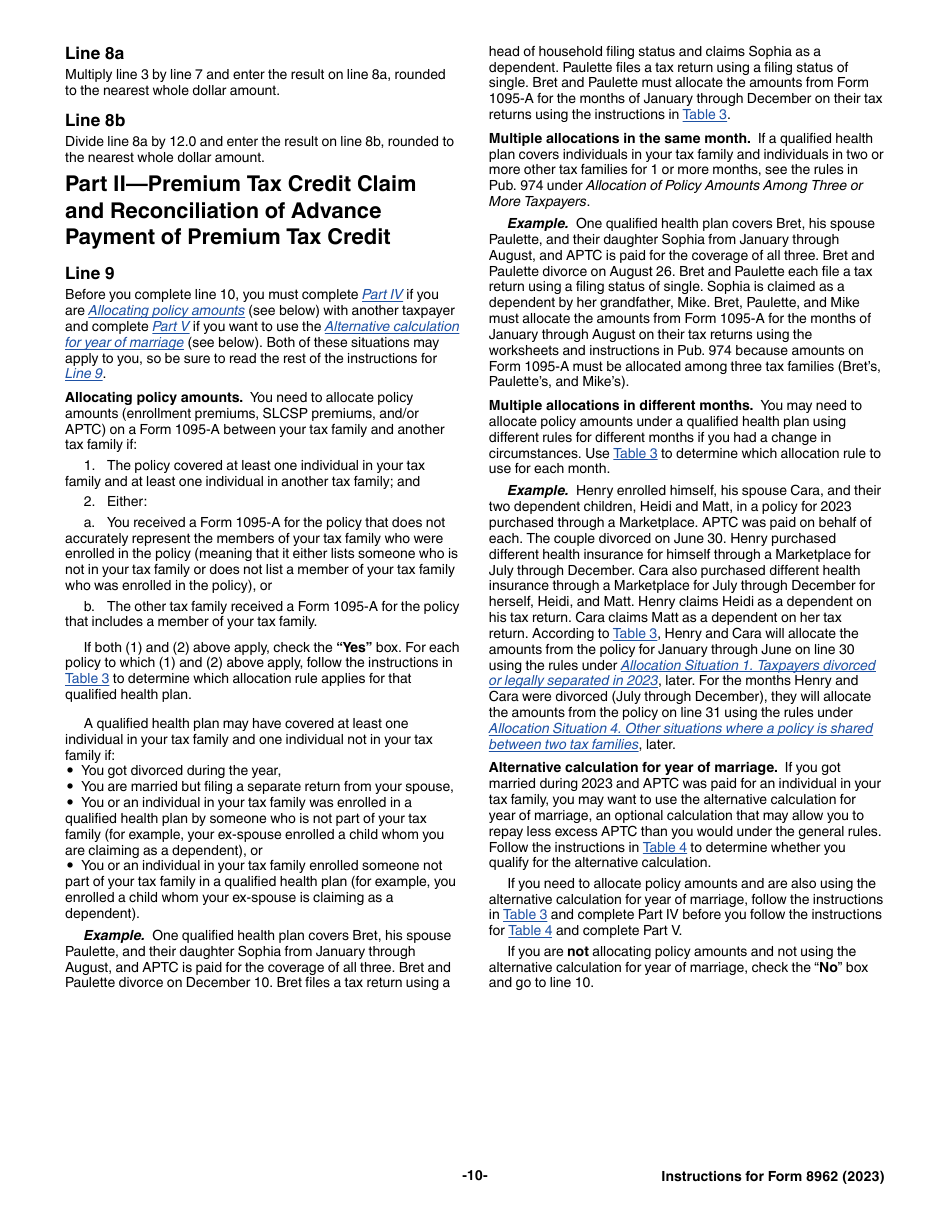
Form 8962 is the paperwork you file when you need to reconcile the advance premium tax credits your insurance marketplace sent to your carrier throughout the year against what you actually qualified for based on your real income. The IRS wants to make sure no one got too much credit or missed out on what they were owed. Most people mess this up because the instructions are fragmented across different pages and the worksheets don't always line up the way you'd expect. I've been filing these for over a decade. The process itself is straightforward if you stay organized, but there are enough edge cases that a careless approach will cost you time during audit season. Let me walk through how to do it properly and what to watch out for.
The Ultimate Form 8962 Instructions PDF Guide Navigating Premium Tax Credits With Precision
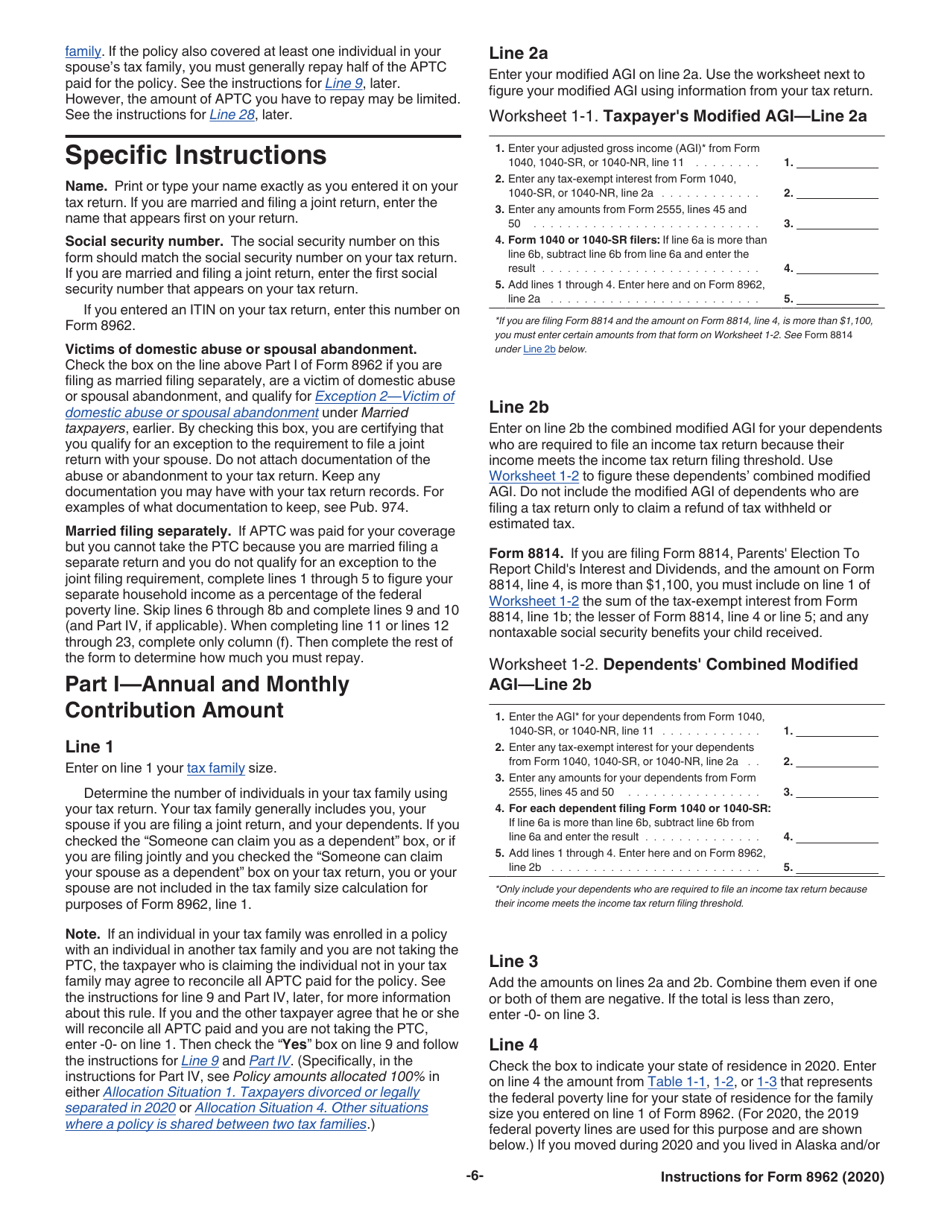
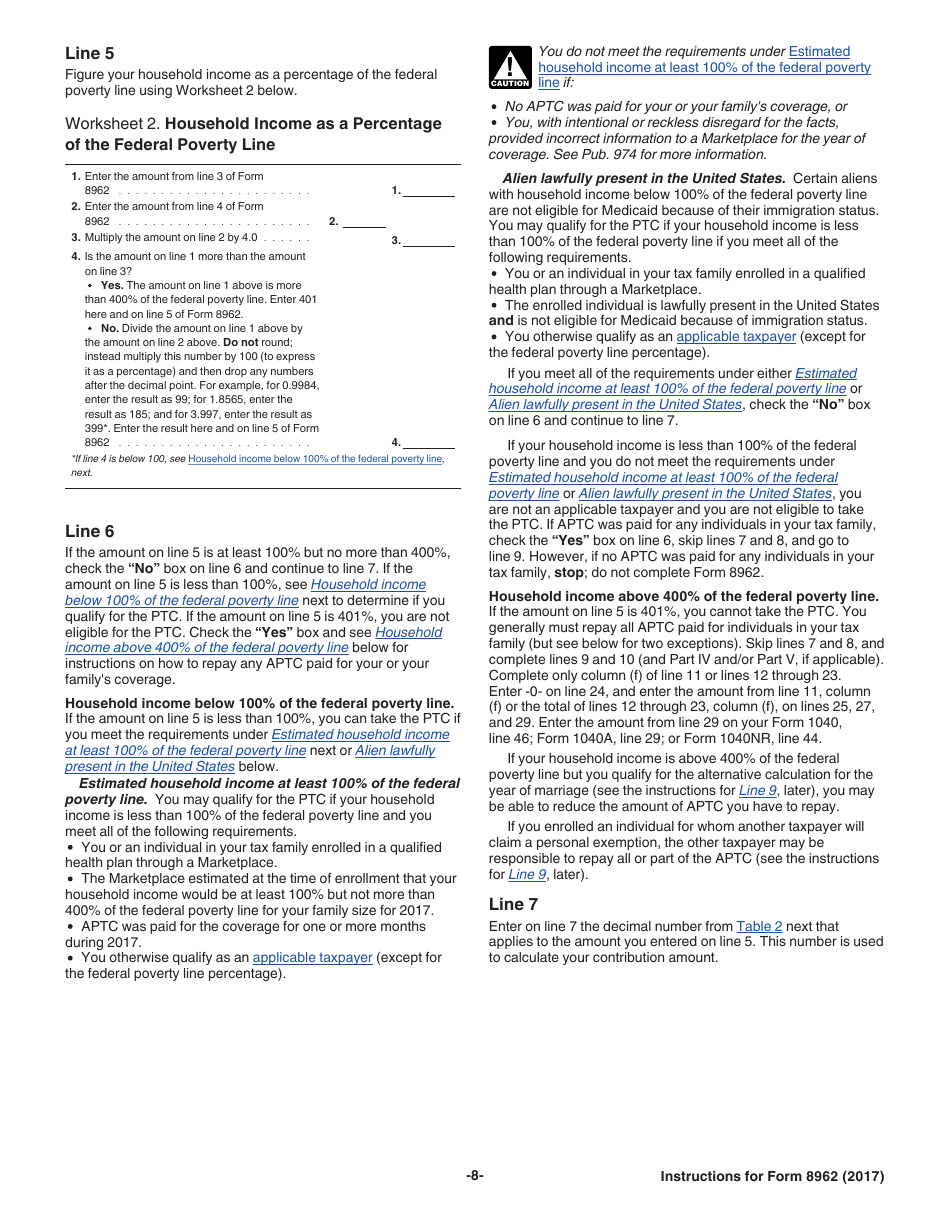
Start by gathering three documents before you open anything on paper. You need Form 1095-A from your marketplace, your actual taxable income for the year from your W-2s and other sources, and the applicable federal poverty guideline figures for your state and household size. These are non-negotiable. If you're missing any of them, stop and get them first. The form won't make sense without all three in front of you. Line 1 of Form 8962 asks for the second lowest cost silver plan premium shown on your 1095-A. This is critical. Do not enter the premium your household actually paid. Do not enter the benchmark plan premium if it's something other than the second lowest cost silver plan. The 1095-A box 2 amount is what goes here. I've seen countless returns bounced back because someone put the wrong premium figure from the wrong box on the form. Double-check which box on the 1095-A corresponds to the second lowest cost silver plan in your county. It varies by state and sometimes by county within a state. Next, you need to calculate your household income as a percentage of the federal poverty line. This determines your contribution percentage. The marketplaces use an estimate when they send advance credits, and that estimate is almost always wrong by tax time. If your income fluctuated during the year or you had a life change that affected your household size, the advance credit calculation on your 1095-A likely doesn't match your final numbers. That's the whole reason this form exists.
Common Problems and Where People Go Wrong
The most frequent mistake I see involves family members changing coverage mid-year. If someone dropped off the marketplace plan partway through the year, you can't just file one Form 8962 and be done. Each household member who had advance premium tax credits needs to be accounted for across the months they were enrolled. The 1095-A will show this, but you have to manually track which months each person was covered and apply the credit calculations accordingly. This is where the form gets complicated fast. Another issue that catches people off guard involves the modified adjusted gross income ceiling. If your MAGI exceeds 400% of the federal poverty level, you generally cannot claim any premium tax credit, and you may have to repay advance credits you received. There are exceptions to the 400% cap under the American Rescue Plan provisions that extended through 2025, but those are temporary and require careful documentation. If your income is near that threshold, run the numbers both ways before you finalize anything. Here's a specific case from my own practice that illustrates why attention to detail matters. A client filed her 1095-A with a marketplace-enrolled plan for months 1 through 8, then switched to employer coverage that didn't qualify for the credit. She tried to claim the advance credits for all twelve months on her return. When I caught the error before filing, we recalculated using only the months she was actually enrolled in the marketplace plan. That correction reduced her refund by about $800 but prevented a notice from the IRS that would have taken three months to resolve. The lesson is simple: the months matter as much as the dollar amounts.
Get the Full Details

Working Through the Worksheets
The worksheets in the Form 8962 instructions are where most of the actual computation happens. Worksheet 1 uses your household income and the poverty line percentages to determine your contribution amount. Worksheet 2 calculates the total advance premium tax credits you received. Worksheet 3 reconciles the two numbers to show whether you're owed additional credit or need to repay excess advance payments. Don't skip any of the worksheets even if the math seems obvious. The IRS reconciliation algorithm checks every line, and mismatches between your form and the IRS's records trigger automated flags. I've seen returns held for weeks over simple arithmetic discrepancies that a second pass through the worksheets would have caught immediately. Take fifteen minutes to verify each worksheet against the corresponding line on the main form. If you receive multiple 1095-A forms for the same tax year, you need to file a separate Form 8962 for each one and then combine the results on your Schedule 2. This commonly happens when a household experiences a qualifying life event mid-year, such as marriage or the birth of a child. Each form tracks a different enrollment period, and mixing them together will produce incorrect calculations. Keep them separate throughout the process and merge only at the final reporting stage.
When Form 8962 Isn't the Answer
There are scenarios where Form 8962 simply doesn't apply. If you purchased health insurance entirely outside the marketplace without any advance premium tax credits, you don't file this form. If you received the premium tax credit through your employer's plan rather than a marketplace exchange, the reporting structure is different. If you're married filing separately and either spouse received advance credits, special rules apply that can actually disqualify you from claiming any credit at all unless you meet specific exceptions. These exceptions are narrow, so if you're in that situation, verify the filing status requirements carefully before proceeding. The form also becomes unnecessary if your household income at the end of the year is below 100% of the federal poverty level. In that case, you generally wouldn't have been eligible for advance premium tax credits in the first place, but if your marketplace issued them anyway, you still need to file Form 8962 to report the repayment. There is no automatic forgiveness for overpayments of advance credits. The marketplace and the IRS don't coordinate to cancel these, and the repayment obligation survives regardless of your current income situation.
Final Considerations Before You File
Accuracy on Form 8962 directly impacts your refund or tax liability. A single digit error in the premium amount or household income can cascade through every worksheet and produce a significantly wrong result. Run a quick sanity check on your final numbers. If your repayment amount exceeds 10% of your expected refund, something is likely wrong. Revisit the worksheets and compare each line against your source documents before attaching the form to your return. The IRS provides the current version of Form 8962 and its instructions on irs.gov, along with the detailed worksheet package. Download the PDF and work through it methodically. E-filing services that include Form 8962 support will validate many of the common errors automatically, but they won't catch everything. The form's logic requires you to understand which income figures go where and why, not just plug numbers into boxes. Take the time to understand the structure of the form. It will save you considerable frustration later.