Why Banks Are Pushing You Toward Your Phone
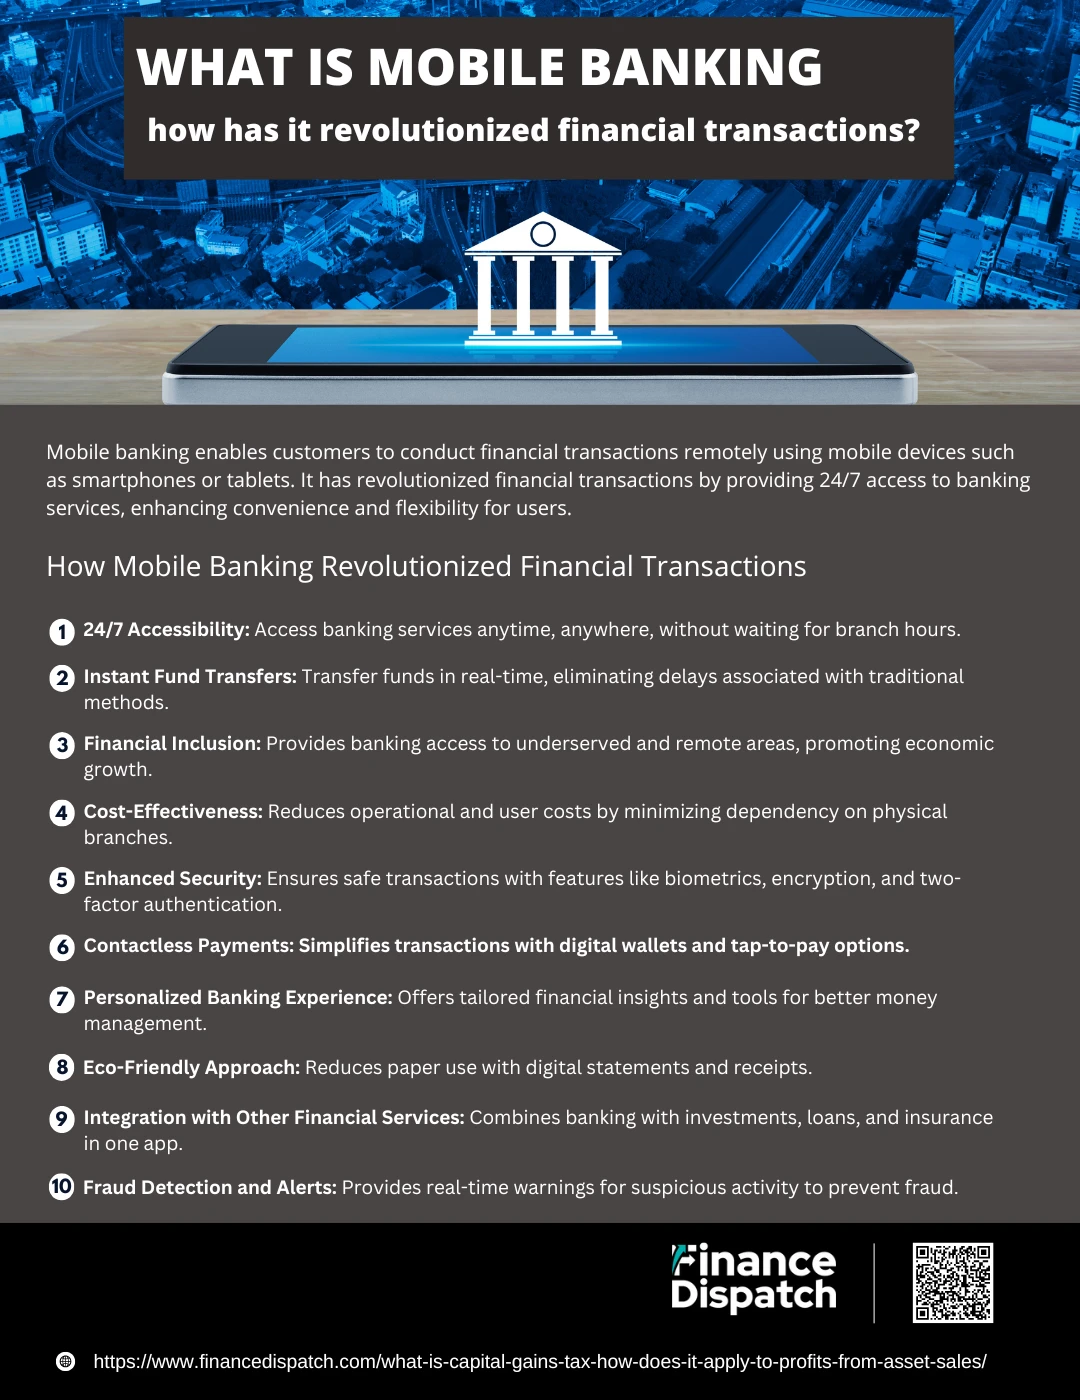
The shift toward mobile banking isn't happening because bankers decided they like your face less. It's happening because maintaining physical branches costs roughly $4 million to $6 million annually per location, and the average branch now processes about 200 to 300 transactions per day, many of which could just as easily happen through an app. Banks are consolidating. Branch closures accelerated dramatically between 2018 and 2024, with over 3,500 locations shutting in the United States alone according to FDIC data. People without smartphones or reliable internet are the ones actually getting squeezed here. Mobile banking works through one of two architectures: a responsive web interface served through your phone's browser, or a native application downloaded from the App Store or Google Play. The native app approach dominates now because it supports biometric authentication, push notifications, and background data sync that browsers can't reliably handle. When you open a banking app and authenticate with Face ID or a fingerprint, the app sends a token through an encrypted channel to the bank's API gateway. The gateway validates the token against the bank's identity provider, pulls your account data from the core banking system, and returns a JSON response. That entire round trip usually takes 200 to 800 milliseconds on a decent connection. What most people don't realize is that the app itself is not storing your money. It's a rendering layer. The actual data lives in the bank's core system, typically a mainframe like Fiserv, Jack Henry, or a modern cloud-hosted ledger. The app is basically a very sophisticated window into that system. Understanding this distinction matters when things go wrong, because you'll sometimes see stale data in your app that doesn't match what's actually posted in your account. A transfer initiated at 11:47 PM might show as pending immediately but not settle until the next business day cutoff, and the app's display of your available balance depends entirely on whether the bank updates in real time or batches updates every few minutes.
I ran into a specific edge case last year that took me three weeks to fully resolve. I had set up mobile check deposit through my primary bank's app, and for eight months it worked fine. Then one Tuesday, a check I deposited for $4,200 showed as received and posted, but my available balance didn't reflect it. The app showed the deposit in the transaction history, but the balance remained unchanged. I called the bank and they said the image was rejected during OCR processing, which is the optical character recognition step that reads the check amount and payee from the scanned image. The problem was that the check had a handwritten amount in the upper right corner that the scanner's confidence threshold flagged as ambiguous. The bank's policy holds the full amount until manual review clears it, but the app never sent me a notification about the rejection because their push notification service had an undelivered queue from a server migration two days prior. My workaround was to log into the web portal on my laptop, navigate to the deposits section, and there was a flagged status message that never made it to the app. I uploaded a second, clearer image of the check through the portal and it posted within two hours. The lesson here is that relying solely on the mobile app for deposit confirmations is risky. Always verify posted balance separately from the deposit confirmation screen, especially for amounts above your typical transaction size.
What Actually Happens When You Make a Mobile Transfer
Let's trace what occurs when you initiate a standard ACH transfer between two accounts at the same bank. You enter the amount, select the source and destination accounts, and confirm. The app generates a request payload and sends it to the bank's transaction processing engine. The engine performs a series of checks: sufficient funds verification, fraud scoring, account status review, and daily limit enforcement. If all checks pass, the engine posts a debit to the source account and a credit to the destination account in the core ledger. This happens internally within the bank's system and usually completes in under 30 seconds for in-network transfers. For ACH transfers between different banks, the process is slower because it goes through the Federal Reserve's ACH network, which operates in sorting cycles. Most banks process ACH submissions four times per day, so a transfer initiated after the last cutoff of the day won't actually begin moving until the next business day's first cycle. That means a Friday evening transfer often doesn't arrive until Tuesday. Wire transfers are different entirely. They route through Fedwire or CHIPS and typically settle in minutes during business hours, but they also cost more and are generally irreversible. I've seen people accidentally send five-figure sums to the wrong account and spend months trying to recover them. No amount of customer service politeness changes the fact that wire fraud recovery is notoriously difficult. The fraud detection systems at most regional banks aren't sophisticated enough to catch every misdirected transfer, and once money leaves your account via wire, it's essentially gone unless the receiving bank cooperates willingly.
Get the Full Details
Security Realities Most People Ignore
Mobile banking apps use multiple layers of encryption. Data in transit is protected by TLS 1.2 or 1.3, which is the same protocol your browser uses for HTTPS. Data at rest on your device is typically encrypted using the phone's hardware-backed keystore, meaning the encryption keys never leave the secure enclave on your processor. This is genuinely stronger than what most people have protecting their password files on their laptops. The weak link is almost always human behavior, not the technology itself. The most common vulnerability I see isn't a hack of the app. It's SIM swapping, where a fraudster convinces your mobile carrier to port your number to a different SIM card, then uses SMS-based two-factor authentication to reset your banking passwords. Banks that rely solely on SMS for multi-factor authentication are running a significant risk. If your bank offers an authenticator app or hardware token as an alternative to SMS 2FA, use it. It eliminates the SIM swap vector entirely. I switched all my accounts to TOTP-based authenticators after a client of mine lost $12,000 to a SIM swap in 2023. The fraudster had ported her number while she was on vacation, intercepted the password reset codes, and drained her checking and savings accounts before the bank flagged anything. Another overlooked issue is session management. Many banking apps maintain long-lived sessions, meaning you stay logged in for days or weeks at a time. On a personal device this is fine, but on any shared or public device it becomes a serious liability. Some apps let you configure session timeouts. Check your settings. A 15-minute inactivity timeout is reasonable. Anything longer and you're leaving the door open if your phone gets misplaced or stolen.
Features That Actually Matter vs. Marketing Fluff
Mobile banking apps have accumulated features that range from genuinely useful to outright distracting. Here's what I consider essential: real-time transaction notifications, mobile check deposit, bill pay, account aggregation across multiple institutions, fraud alerts, and the ability to freeze individual cards or accounts instantly. These five features alone cover 90 percent of what most people need from a banking app. Features like spending categorization, budgeting dashboards, and "insights" modules are nice but unreliable. The categorization engines are usually rule-based or lightly machine-learning-assisted, and they get things wrong frequently. I've had groceries categorized as entertainment and utility payments flagged as subscriptions. These features can be a starting point for understanding your spending, but they require manual correction to be accurate. Don't trust the auto-categorization without verifying it against your actual statements. Account aggregation, the ability to view accounts from other banks within the same app, is useful if your bank supports it well. Plaid and similar data aggregators power most of these features. The tradeoff is that you're granting a third-party data processor access to your financial information. Plaid is the dominant player and they've been generally reliable, but they've also had security incidents. In 2023, Plaid disclosed that a third-party vendor had improperly accessed user data. It wasn't a breach of Plaid's systems directly, but it's a reminder that every layer in the data pipeline is a potential point of failure. If you use account aggregation, review which connections are active and revoke any you don't actively need.
Where Mobile Banking Actually Falls Short
There are scenarios where mobile banking simply doesn't work well enough to be your only option. Cash deposits are the biggest gap. Most banks allow mobile check deposit but very few have cash deposit machines integrated into their apps. If you're a cash-intensive business owner or someone who receives regular cash payments, you're still stuck driving to a branch or an ATM with deposit capability. Some credit unions and smaller banks have started installing cash acceptance ATMs, but the network is fragmented and inconsistent. Complex transactions like loan applications, mortgage refinancing, and business account openings still generally require in-person interactions or at minimum a desktop web session. The mobile experience for these processes is usually a stripped-down version that funnels you toward a branch appointment anyway. Don't waste time trying to complete a commercial loan application on your phone. The form factor isn't designed for it and the app will likely just redirect you to a web portal or a scheduling page. Accessibility is another area where mobile banking underperforms. Screen reader compatibility varies dramatically between banks. I've tested banking apps with NVDA and VoiceOver, and the difference between a well-accessible app and a poorly accessible one is enormous. Some apps have proper semantic labeling, logical tab order, and adequate color contrast. Others treat their interface like a design project with no regard for assistive technology users. If you or someone you depend on relies on screen readers, test the app thoroughly before committing to that bank. Look for FDIC disclosures about WCAG compliance, though even those disclosures don't guarantee a good experience.
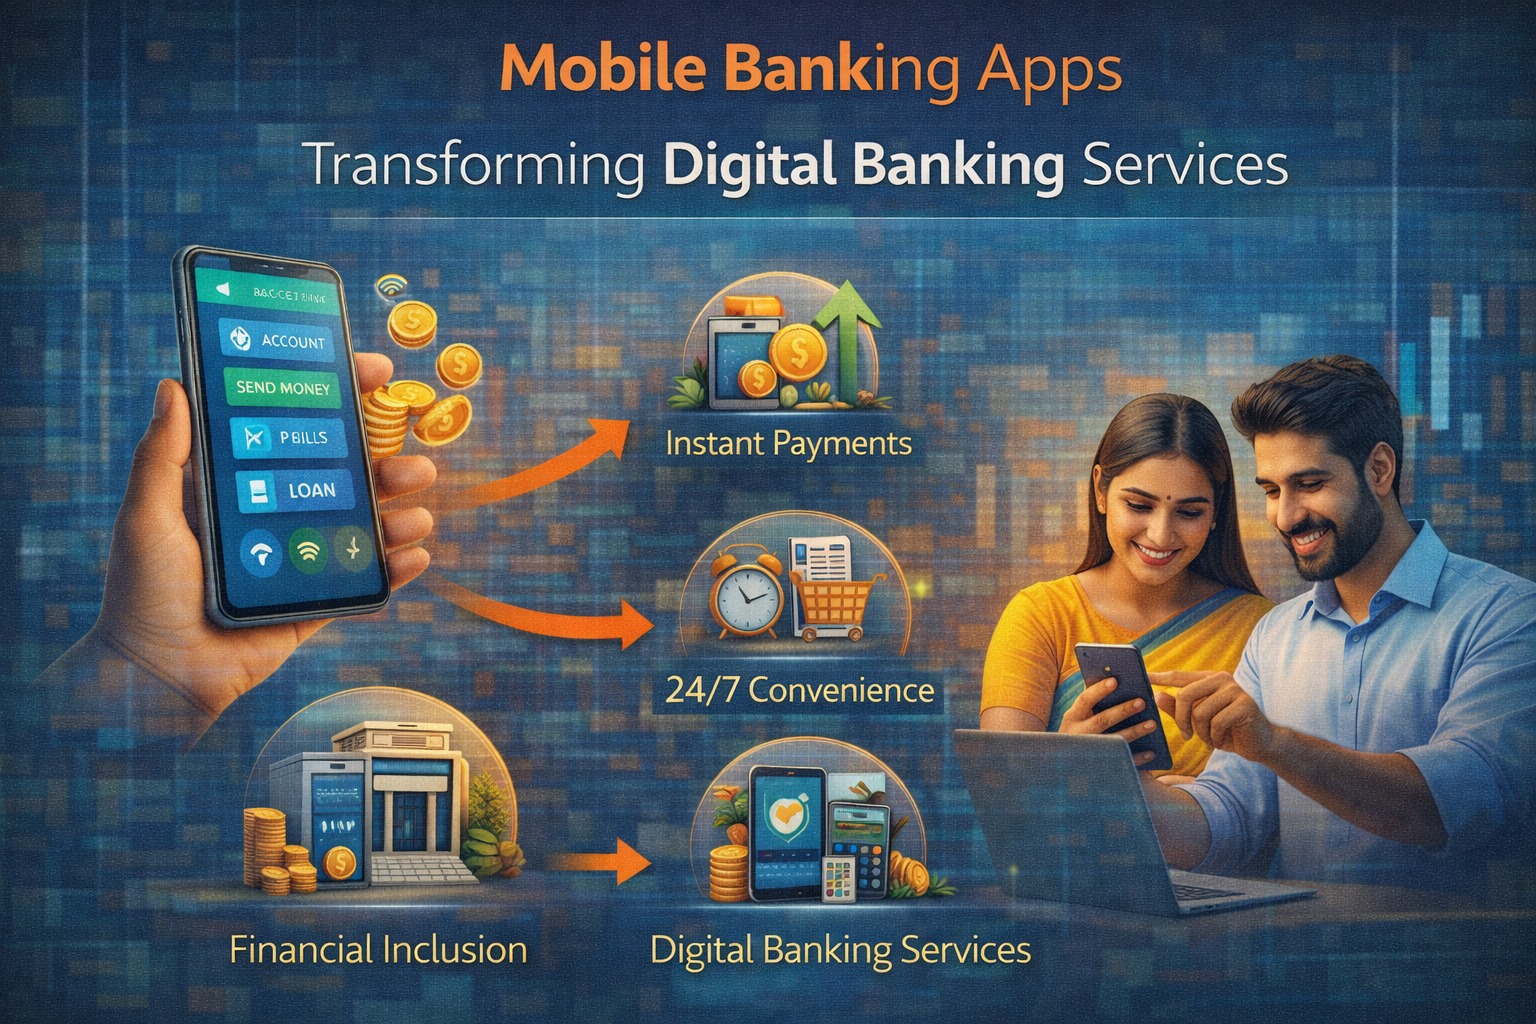
International users and people without traditional banking histories face another barrier. Many mobile banking platforms require a Social Security number, a verified address, and a minimum opening deposit. Alternatives like prepaid card apps and fintech neobanks have relaxed some of these requirements, but they often come with their own limitations: lower deposit limits, fewer features, and sometimes less regulatory protection. The FDIC insurance question is important here. With most neobanks, your money is held at a partner bank and insured through that bank's FDIC coverage. You need to verify that coverage is actually in place and understand how it works. Some apps offer up to $250,000 in pass-through insurance across multiple partner banks, but the mechanics of that coverage can be confusing and you may not realize you're exposed until something goes wrong.
Practical Steps to Set Up Mobile Banking Securely
If you're new to mobile banking or looking to tighten things up, start with these steps in order. First, download the official app directly from the App Store or Google Play. Do not download banking apps from third-party APK sites or email links. Second, enable biometric authentication if your device supports it. Face ID and fingerprint authentication are stronger than PINs because they can't be socially engineered or observed. Third, disable SMS-based two-factor authentication and switch to an authenticator app or hardware token. Fourth, review your transaction notification settings and enable alerts for transactions over a reasonable threshold, like $100 or $250 depending on your normal spending patterns. Fifth, set a session timeout of 10 to 15 minutes. Sixth, download your bank's fraud prevention app if they offer one, which typically includes card freeze controls and instant fraud reporting. Seventh, periodically review your connected third-party services and revoke access for anything you no longer use. One thing I recommend that most people skip: download and save a copy of your most recent account statement in PDF format every quarter. Mobile apps make it easy to view transactions online, but if the app has an outage or your account gets compromised and locked, you may not be able to access your transaction history for weeks. Having local copies of your statements gives you a baseline to detect discrepancies quickly. It also helps if you need documentation for a dispute, tax preparation, or a rental application. Mobile banking has made financial access significantly broader and more convenient. People in rural areas without a nearby branch can now manage accounts that previously required a trip of an hour or more. Immigrant communities that faced barriers to traditional banking have more entry points through fintech alternatives. Small business owners can process deposits and manage cash flow without taking time off work to visit a branch. These are real improvements. But the technology has hard limits, and the convenience comes with security responsibilities that most banks do not communicate clearly enough. The gap between what the app shows you and what is actually true in your account is where problems hide. Pay attention to that gap. Verify balances independently. Keep backups of your statements. And never assume that a confirmation screen means the money has actually moved.


