Tractor Supply Checkout: What Actually Works and What Doesn't
Tractor Supply has built a payment infrastructure that handles everything from a $12 bag of dog food to a $4,000 ride-on mower, and most of it works without friction. I've processed transactions across both channels for years, and the friction points are usually on the customer side, not the company side. Here's how it breaks down. At the core, Tractor Supply accepts standard payment rails: Visa, Mastercard, American Express, and Discover. That covers the majority of in-store and online transactions. They also run a branded store credit card issued by Synchrony Bank, which is the same banking partner used by a lot of big-box retailers. The store card offers promotional financing on qualifying purchases, typically 6 to 24 months depending on the promotion, and that's where people tend to get confused. Online checkout also supports PayPal, Apple Pay, Google Pay, and Affirm as a buy-now-pay-later option. Gift cards are accepted in both channels. For eligible agricultural and household essentials, they accept EBT/SNAP cards in-store, though this doesn't apply online except through their partnership with certain delivery programs. The in-store payment terminal usually prompts you to check for the Synchrony card offer at checkout, which is fine if you're not looking for new credit, but declining it doesn't slow your transaction down.
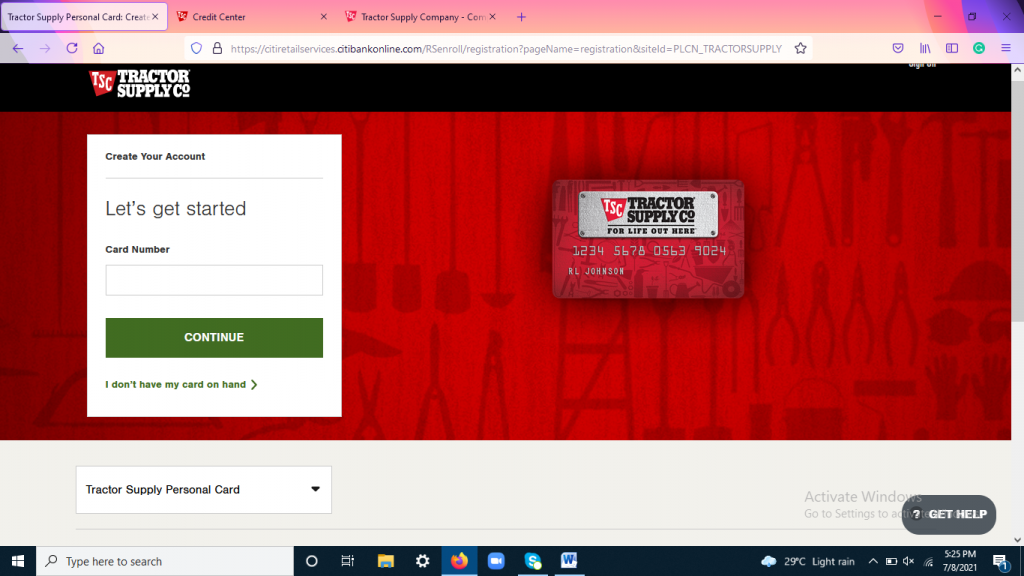
One thing most people don't realize: the Tractor Supply credit card application is a soft pull in most cases before you get the final offer, but the actual approval trigger is a hard inquiry. I've seen people accidentally run a hard pull just by clicking "apply now" at checkout without reading the fine print. If you're shopping with tight credit windows, fill out the application separately on the Synchrony portal instead of through the checkout flow. It gives you the same rate offers but lets you time the hard pull when it matters. Affirm is available online and occasionally in-store for larger purchases. The terms vary by purchase amount and credit profile, typically ranging from 3 to 36 months with APRs that can run from around 0% promotional to 30% depending on your creditworthiness. The catch with Affirm is that it doesn't stack with other promotions or discounts on the same order. If you're buying a tractor part that's already running a 20% off sale, applying Affirm to that transaction cancels the discount. I learned this the hard way on a $1,200 order of snowplow equipment. The checkout screen showed the discount at $960, but once I selected Affirm, the price jumped back to $1,200. The workaround was straightforward: pay with a credit card and use Affirm on a separate transaction, but only if the system allows splitting the order that way. In my case, I called customer service, had them void the original cart, and re-place it as two orders. Took about twenty minutes and saved me the discount hit. EBT eligibility is another area where people run into problems at the register. Not all items qualify. Hand tools, equipment, feed for working animals, and most chemicals are ineligible. Only certain food-grade products and some animal feed categories pass EBT verification. The POS system flags these automatically, but the split-payment process can get messy if your cart has a mix of eligible and ineligible items. The workaround is to ask the cashier to ring up the EBT-eligible items separately before running your card for the rest. It takes an extra minute at the register and avoids the awkward moment when your SNAP balance gets declined partway through.
For online orders, there's a common issue where gift card balances don't always apply correctly during the payment stage, especially if the order total changes after the gift card is applied due to shipping adjustments or tax recalculation. I've had gift cards show as partially used with a remainder that vanishes if you don't manually refresh the payment screen before finalizing. Keep a screenshot of your remaining balance before you click place order. If something goes wrong, that screenshot is what you'll need for customer service. One more thing worth noting: Tractor Supply's payment processing is handled through multiple gateways depending on the channel. In-store transactions go through a different processor than online, which means a card that gets flagged online might not get flagged in-store, and vice versa. If your card keeps getting declined online, try placing the order in-store or calling in. The risk assessment engines don't always sync perfectly between the two systems, and it's not uncommon for a legitimate card to slip through one gate and get caught by the other. The financing options through Synchrony are competitive for approved applicants, but the deferred interest promotions are where people get burned. If you don't pay off the full balance by the end of the promotional period, interest accrues from the original purchase date, not from the date of each payment. A $2,000 purchase on a 12-month deferred interest plan at 26.99% APR will cost you $539.80 in back-interest if you miss the payoff by even one day. Paying down $1,900 of it over eleven months doesn't help. The balance has to be zero by the deadline.
Get the Full Details

For most shoppers, the fastest checkout path is using Apple Pay or Google Pay in-store, or saving a card to your Tractor Supply account for online purchases. The store card makes sense if you're making a large equipment purchase and can guarantee full payoff within the promotional window. Affirm works for bigger purchases if you're not combining it with discounts. And if you're paying with EBT, keep your eligible and ineligible items in separate transactions from the start to avoid the split-payment headache at the register.