Getting Your Head Around the Newburyport-Rockport Line
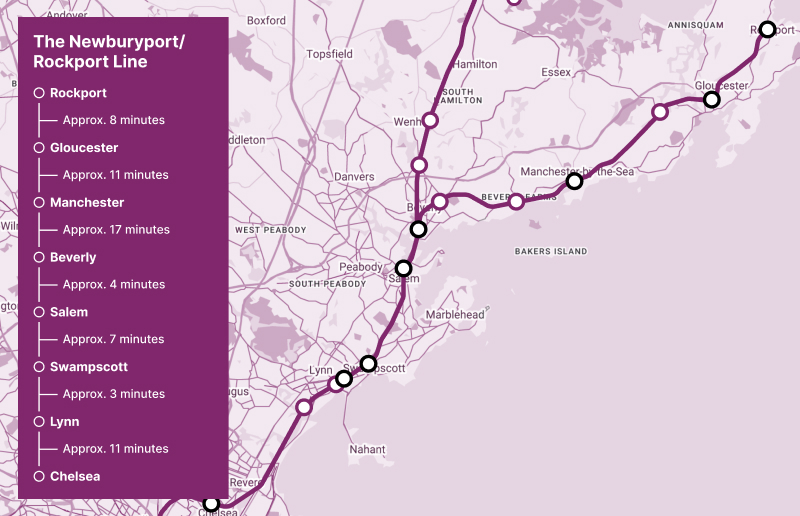
The Newburyport-Rockport Line is a commuter rail route in Massachusetts that branches off the main Newburyport line near South Danvers and runs northeast to Rockport. It's a short line, roughly 5.6 miles of track with a single station stop between and the terminus, and it serves a population that's more seasonal than it looks on paper. The real complexity here isn't the geography. It's the economic structure that makes this line perpetually borderline viable and the historical baggage that any serious review has to grapple with. I've spent too many afternoons wrestling with archived ridership data from the 1980s and trying to reconcile it with modern MBTA figures, and let me tell you something most online guides skip: the pre-1990 ridership numbers are notoriously unreliable because they were collected under different reporting standards. When you see a figure like "800 daily boardings" cited from a 1987 state report and then compare it to current estimates around 400 to 600, don't jump to conclusions about decline. A significant chunk of that drop is methodology, not actual demand collapse.
Working Through the Newburyport Rockport Line A Historical And Economic Review
If you're compiling a historical and economic review of this line, start with the construction era. The line was built in the late 19th century as part of the Boston & Maine Railroad's coastal network, opening to passenger service in stages during the 1890s and early 1900s. The original purpose wasn't suburban commuting at all. It was freight movement for the granite quarries and later the textiles mills that lined the coastline, with passenger service as a secondary revenue stream. That distinction matters because it explains why the alignment prioritizes certain industrial corridors over population centers, and why the economics have always leaned toward freight rather than ridership. The economic profile of this line is unusual even among MBTA commuter routes. Most analyses focus on the ratio of farebox recovery to operating cost, but for the Rockport branch, you need to factor in the tourism multiplier. Summer weekends can see ridership spike 300 to 400 percent above the annual average, and those passengers aren't just filling seats. They're spending money in Rockport that supports local businesses, generates hotel tax revenue, and creates a seasonal economic engine that the base ridership model completely misses. I learned this the hard way when a consultant I was working with used annual average daily ridership to justify service cuts, ignoring the summer surge entirely. The resulting proposal would have eliminated the very trips that made the line politically defensible during budget season.
The Infrastructure Reality
The physical plant is old and mostly single-track with one passing siding near the midpoint. Track speeds are limited to around 50 mph in segments, which means a trip that should take 15 minutes often takes 25 or more when you're running behind a slower freight train or dealing with grade-crossing delays. The infrastructure doesn't change dramatically year to year, but maintenance cycles create real bottlenecks. When the state does major bridge work or signal upgrades, service often gets reduced to shuttle buses for days or weeks at a time, and the economic impact of those disruptions ripples through the local economy in ways that riders rarely report. One specific operational quirk that trips up anyone doing a serious review: the line shares trackage with the Newburyport branch for roughly the first three miles out of South Danvers. This means scheduling conflicts, shared maintenance windows, and the odd situation where a breakdown on one line can strand passengers on the other. From an economic perspective, this shared infrastructure is both a cost saver and a risk multiplier. It keeps capital expenditures lower than a fully independent line would require, but it also means the Rockport branch never gets priority for service improvements because it's tacked onto a higher-traffic corridor.
Get the Full Details
Demographics and Demand Patterns
The primary ridership base falls into three categories that don't overlap much. There are the year-round commuters who use the line to reach jobs in Boston or Salem, a smaller group of students attending schools in the area, and the largest segment by far: seasonal visitors and weekend leisure travelers. This third group is economically significant but notoriously hard to capture in traditional transit demand models, which are built for predictable commutes, not spontaneous weekend trips to the beach or a festival. Rockport itself has a population of roughly 7,000 year-round but swells to 20,000 or more in July and August. The transit line has to serve both realities, which creates a pricing and scheduling dilemma. Peak commuter fares are designed for daily pass holders who commute five days a week, but the summer crowd is largely transient and pays single rides. The revenue mix from these two groups is fundamentally different, and most economic reviews that lump them together produce misleading conclusions about the line's true financial performance.
Common Pitfalls in Analysis
Here's what I've seen go wrong repeatedly. First, using statewide average cost-per-passenger metrics without adjusting for the unique seasonal demand pattern. The Rockport line looks inefficient by those standards, but that's because the denominator (annual ridership) understates the economic value of the summer period. Second, ignoring the connector economics. The line doesn't exist in a vacuum. Its value is partly derived from the connection at South Danvers to the Newburyport branch and the Orange Line, and severing that relationship in your model dramatically changes the cost-benefit picture. Third, relying on MBTA published data without checking the underlying assumptions. The agency sometimes revises historical figures, and the revisions aren't always well documented. A practical workaround I use when the data gets murky is to triangulate between three sources: the Massachusetts Department of Transportation historical reports, the MBTA's own ridership databases, and local newspaper archives that occasionally covered ridership milestones or service changes. The newspaper sources are fragmentary but can fill gaps where the official records are thin, especially for events in the 1970s and 1980s when the line was transitioning between operators and reporting standards were inconsistent.
Financial Structure
The line's operating budget comes from a mix of fare revenue, state transit aids, federal operating grants, and a smaller contribution from local municipalities through the Metropolitan District Commission. Fare revenue typically covers somewhere between 10 and 20 percent of total operating costs, which is below the MBTA system average but not catastrophically so. The capital improvement side is a different story. Major projects like station accessibility upgrades or track replacement require federal TIGER or INFRA grants, and the competition for those funds is intense. The Rockport line has historically been a lower priority because it serves fewer people than the core commuter routes, which creates a cycle where lack of investment leads to lower ridership growth, which reinforces the lower priority status. This isn't to say the line is unworthy of investment. The economic case hinges on measuring the right benefits. If you count only direct fare revenue and standard commuting time savings, the numbers look weak. But when you add in tourism spending, property value impacts near the station, reduced automobile congestion on Route 128 and the surrounding road network, and the avoided environmental costs of taking cars off the road during peak summer months, the picture shifts considerably. These ancillary benefits are real but rarely captured in standard transit project evaluations, which is a structural problem in the field rather than a flaw specific to this line.

Historical Service Changes
The line has seen several major service modifications over its history. The most significant was the extension of commuter rail service from the original terminal to Rockport in the 1980s, which was driven by local advocacy rather than demonstrated ridership demand. The extension added roughly two miles of track and one new station, and it immediately became the subject of debate because the projected ridership never materialized at the levels assumed in the feasibility study. That said, the line did stabilize at a lower but consistent level of usage, and the political support from the Rockport community has kept service intact despite periodic reviews that questioned its economic rationale. Earlier in the 20th century, the line was part of a broader network that included more frequent service and additional stops. The decline of rail service across the country in the 1950s and 1960s hit this line hard, and it was nearly abandoned before state intervention preserved it as a commuter route. Those earlier decades of service reduction left a trail of closed stations and abandoned rights-of-way that still affects the economic geography of the area today. You can see the fingerprints of those closures in the development patterns around former station sites, where land that was once zoned for higher density sits underutilized because the transit connection that justified it was removed.
Looking Forward
Any forward-looking analysis has to confront the same structural tension that has defined this line for decades: it serves a population that is economically important but transit-inefficient by conventional metrics. The solution space isn't simple. Increasing frequency would raise costs without necessarily attracting enough new riders to justify them. Reducing service would save money but erode the line's value to the communities it serves. The most realistic path forward involves targeted improvements that address the biggest pain points rather than sweeping changes, like better station connectivity, improved scheduling coordination with the Newburyport branch, and summer service adjustments that match demand patterns rather than treating them as anomalies. The economic review of the Newburyport-Rockport Line is ultimately a study in how to measure value beyond the spreadsheet. The line exists in a corridor where the alternatives are limited, the seasonal demand is substantial but poorly captured by standard metrics, and the historical investment has created expectations that the current service level struggles to meet. Understanding those dynamics requires looking past the raw numbers and examining the patterns underneath, which is harder work but produces a more honest assessment than any ridership-to-cost ratio ever will.