
What the Project 5-Year Back and Financing Programs Actually Cost You
I ran a full bathroom remodel last October using a Home Depot credit card for the bulk of it. I signed up for the promotional financing, figured it was free money until the due date. It wasn't free. Not even close, and the fine print buried that fact under three layers of terms nobody reads. The 5 percent back program sounds generous on paper, but the return rate only kicks in on select categories and often requires you to maintain a minimum spend threshold every billing cycle. I learned this the hard way when I put $4,200 worth of lumber and fixtures on the card, spent two months making minimum payments on time, and then got hit with a retroactive interest calculation because I hadn't met the category qualification window. The card itself comes in three tiers. The blue bundle card gives you 5 percent back on most Home Depot purchases, but the actual redemption only processes as a statement credit at checkout, not as cash back you can take anywhere. The premium card adds special financing options that look attractive until you read the deferred interest clause. And then there's the commercial card, which is a completely different beast aimed at contractors and pros who run business expenses through the system.
Here is what most people miss about the deferred interest offers. The 5-year financing deals that get pushed hardest in-store are almost never zero percent. They're deferred interest, meaning if you don't pay off the entire balance before the promotional period ends, they slap retroactive interest on the original purchase price from day one. I sat across from a sales rep who told me "you won't pay any interest." He wasn't lying, technically. He just omitted the part where I would owe four thousand dollars in back-interest if I missed a single payment by two days. The workaround I ended up using was setting up automatic payments for the full monthly amount, not the minimum, and calendar reminders for the payoff deadline that fired three weeks early. Even then, I still carried a separate high-yield savings account where I parked a portion of every paycheck to ensure the balance cleared before the window closed. This usually cuts the stress level from "I might lose thousands" down to "I probably won't mess this up if I don't forget." The 5 percent back calculation itself has a hidden cap. Some card agreements limit your total annual cash back to somewhere around two hundred to five hundred dollars, depending on which version of the card you qualified for. If you are buying major appliances or running a full renovation, that ceiling hits fast and then your subsequent purchases earn zero percent until the next calendar year resets. I found this out when my statement showed $0 in rewards for the last four months of the year despite spending another eight thousand dollars on top of the initial project.
There is also a pricing nuance that rarely gets discussed. Items purchased with a Home Depot credit card sometimes get flagged for price matching differently than standard retailers. I tried to match a lower price I found at a competitor on a $900 air handler unit and was told the system would not process the adjustment because the receipt from the big box store did not show the same promotional terms that were active in our local market at the time. The workaround was calling corporate directly rather than arguing with the store associate. I filed a formal price match request with screenshots, printed promotional pages, and receipts from both stores in the same email thread. It took eleven business days to process but came through at the end. The application process itself is straightforward but the approval criteria lean heavily on credit utilization and recent hard inquiries. If you have two or more new credit accounts opened in the last ninety days, your approval odds drop significantly even if your credit score sits above seven hundred. I watched a contractor with excellent credit get declined because he had pulled three new equipment loans in February and the algorithm treated him as high risk despite paying everything off on time. One thing the marketing material does not tell you is that the 5 percent back does not apply to every product line. Appliances often fall into a restricted category that earns only 1 percent or sometimes zero depending on manufacturer rebate policies and the current quarter promotions. Tools and outdoor power equipment sometimes get grouped into separate reward brackets that reset monthly. I learned to check my online account dashboard before every purchase rather than assuming the banner ad applied to everything on the floor.
Get the Full Details
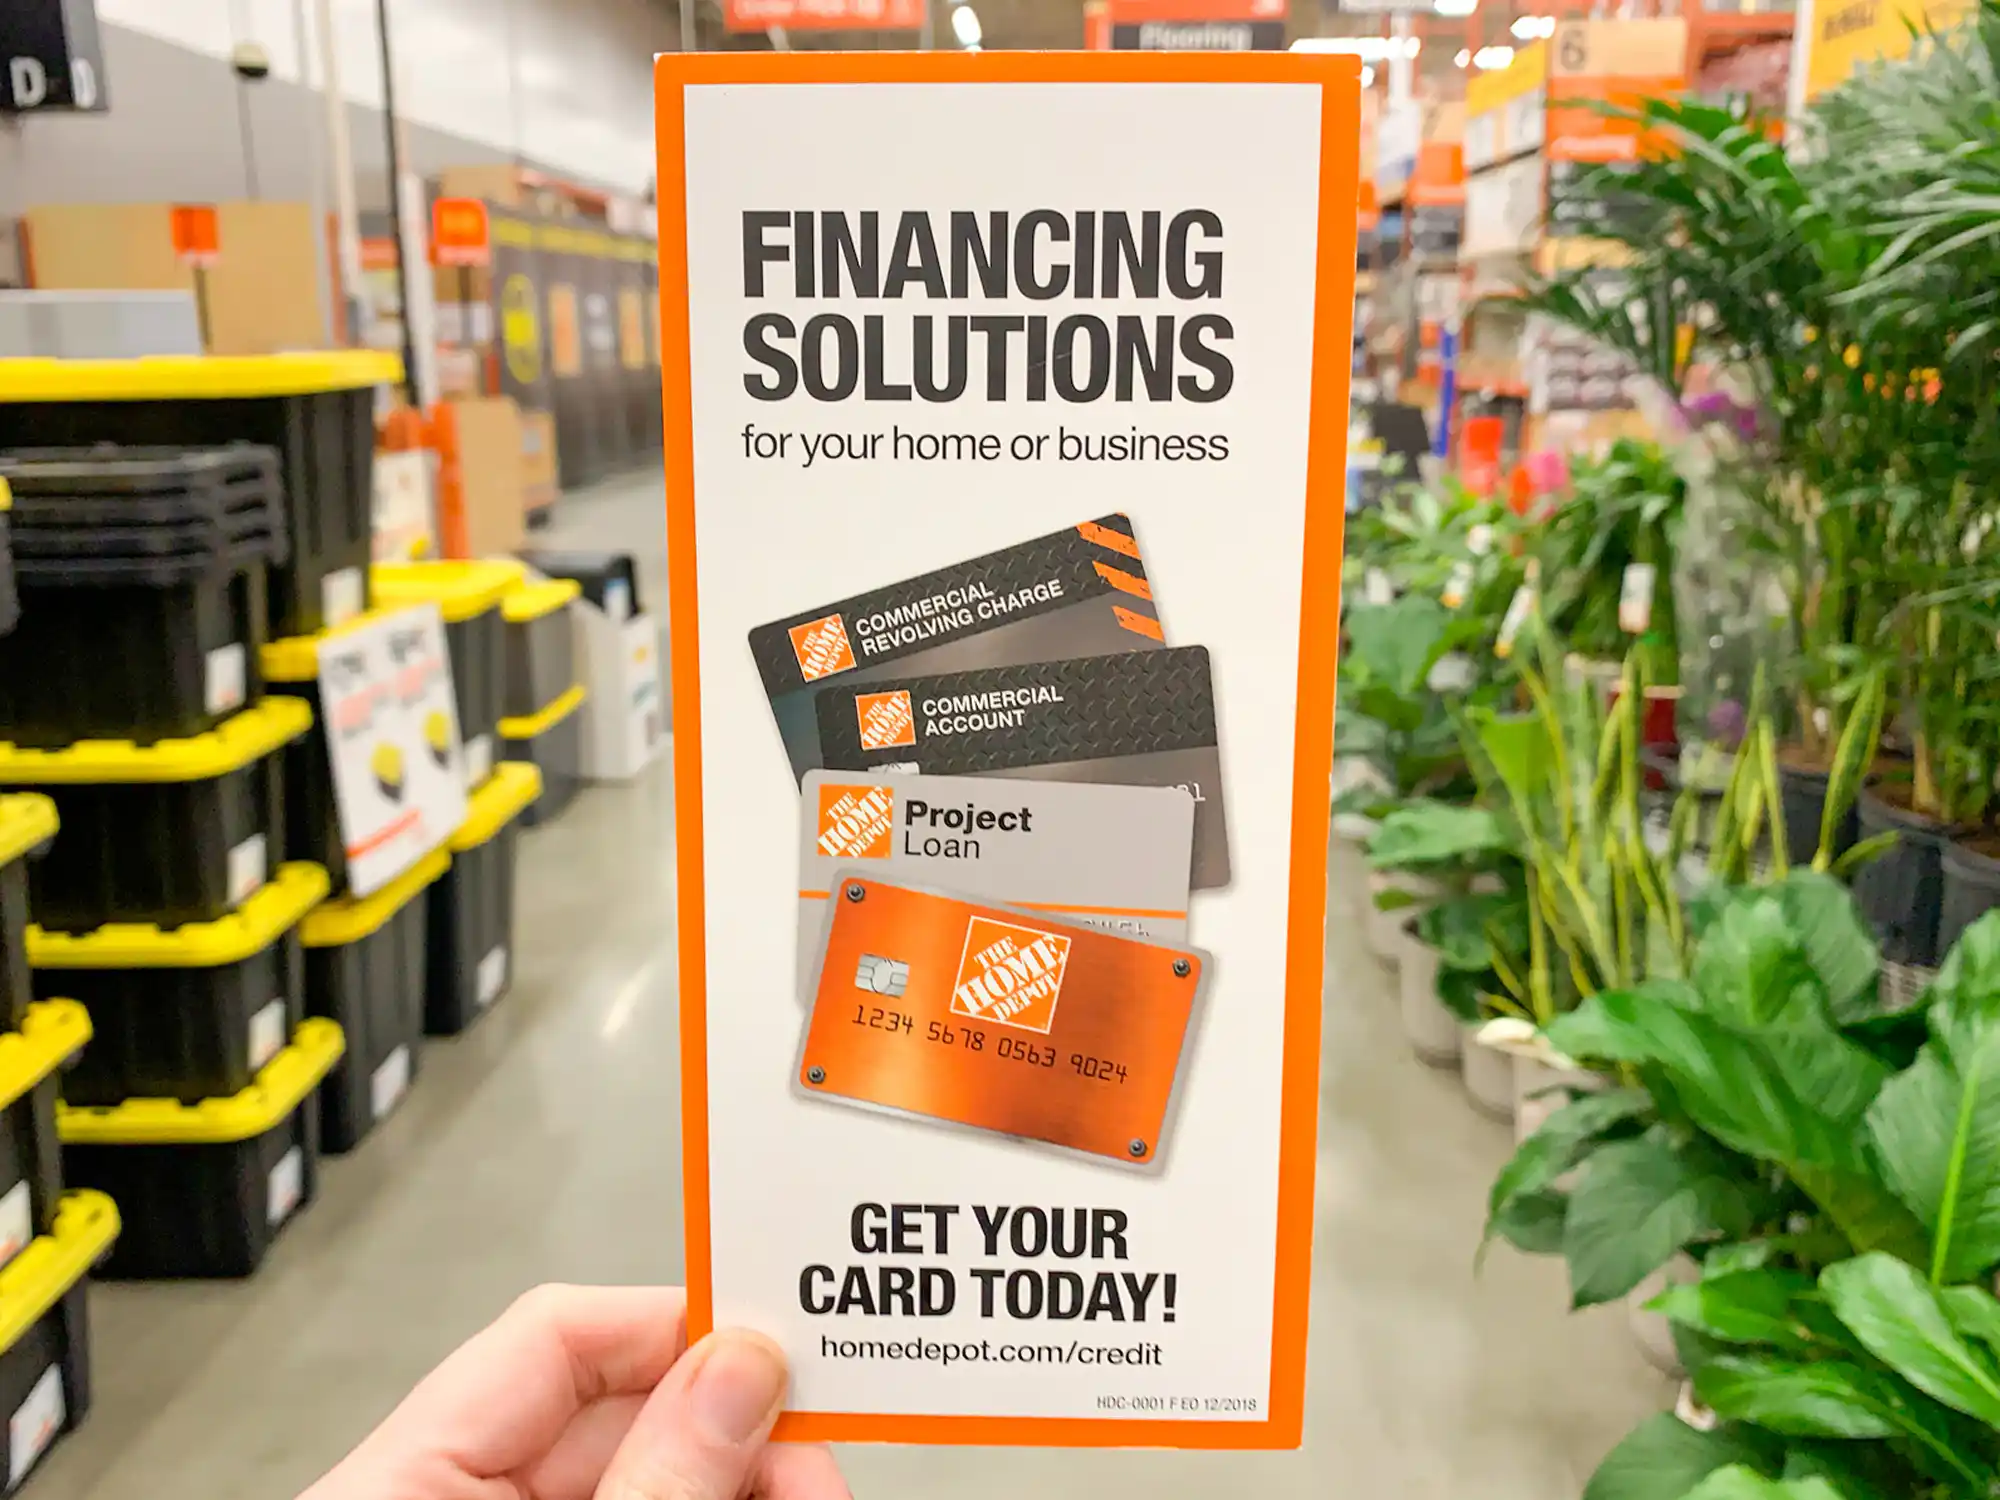
The financing deals themselves have a quirk that catches people who budget tightly. Some promotional periods start counting from the purchase date while others start from the first billing cycle. This discrepancy means your actual payoff deadline can shift by thirty to forty-five days depending on when exactly the sale happened relative to your statement closing date. I missed my target by six weeks once because I assumed day one of the promotion aligned with my calendar month when it actually rolled forward to the first billing statement after checkout. If you are considering these cards for a one-time project, I would recommend comparing the math against a standard zero percent balance transfer card from a bank first. A typical bank offer might give you twelve to eighteen months with actual zero interest, no deferred interest trap, and the flexibility to pay down however you want. The Home Depot card wins when you need materials immediately and want the rewards stacking on top of familiar retailers you already shop at regularly. It loses when your project timeline stretches or your cash flow might dip near the promotional deadline. The administrative side of managing multiple purchases across different billing cycles adds another layer of complexity. I kept a spreadsheet tracking each transaction date, the promotional window it fell under, and the exact payoff target for that billing period. This usually takes about twenty minutes to set up initially and then five minutes per month to maintain, but it prevents the kind of balance confusion that led me into the deferred interest situation I mentioned earlier.
You also need to understand how returns work when you financed a purchase. If you bought something on a promotional financing plan and then return it, the return amount gets applied to your balance but it does not reset your promotional clock. The remaining balance still carries the original deadline. I returned a defective water heater two months into my financing term and thought the timeline extended. It did not. I had to pay off the full remaining balance including the portion I had already covered to avoid the deferred interest penalty kicking in on the rest of the purchase. The customer service experience with these cards runs the full range from helpful to dismissive depending on which department you reach. I spent forty-five minutes on hold twice trying to clarify a billing discrepancy that showed my promotional period had expired a week early when it should have still had six months remaining. The error came from a system glitch that failed to sync the purchase date with the promotional tracking database. Corporate customer relations fixed it within forty-eight hours after I provided my account number and a screenshot of the original terms page I saved at signup. One final practical note about the 5 percent structure. The rewards typically post as a statement credit at the end of each calendar year or sometimes quarterly depending on the card tier. You cannot use them for mid-cycle redemption except in very limited scenarios like instant checkout discounts on select categories. This means if your project spans two years, you only get the full benefit once per cycle and your effective annual return rate drops significantly when you divide by the total amount spent over that longer period.


