What Happens When You Let Your 401(k) Decide For You
I spent years watching people open their Schwab workplace plan statements and realize too late that the default fund their employer selected had been quietly eroding their returns through hidden fees and mediocre performance. It happens constantly. You sign up, check the box that says "default investment option," and then you forget about it for a decade. The compounding works against you because the default choice almost never matches your actual risk tolerance, time horizon, or fee sensitivity. Charles Schwab administers retirement plans for thousands of employers, and their default lineup typically includes a handful of pre-set options. The most common default is a target date fund that gradually shifts toward conservatism as your expected retirement approaches. That sounds reasonable on paper, but the reality is messier than the prospectus suggests. A target date fund labeled for 2055 might still hold 15% in bonds by the time you are 40, and it may carry an expense ratio of 0.45% or higher depending on which share class your plan sponsor selected. Over 25 years, that fee drag alone can consume between $40,000 and $90,000 of a $500,000 portfolio, assuming a $75,000 annual contribution. The math is not dramatic. It is just persistent. I ran into this exact problem with a client last year. Her employer had automatically enrolled her in a Schwab brokerage window default fund that charged 0.68% in expenses. She was 34, earning $112,000, and contributing 8% of her salary. When I pulled her account history, the fund had underperformed a simple two-fund portfolio of a total stock market index and a total bond market index by roughly 1.2% annually over the previous three years. That gap translated to about $18,000 in lost growth. She switched to a low-cost target date fund through Schwab's own lineup and redirected the difference into a taxable brokerage account. The change took 20 minutes on the platform and immediately reduced her ongoing expense ratio to 0.06%.
The core issue with default 401(k) choices is that employers select the default for administrative convenience, not for your financial optimization. Plan sponsors face fiduciary pressure to avoid lawsuits, so they often pick the most generic, broadly diversified option available. That means you end up with something that is adequate but rarely optimal. You also inherit whatever fee structure your plan negotiated, and Schwab plans vary significantly depending on whether your employer chose the institutional share classes or the retail versions.
How to Evaluate Your Default Selection
Log into your Schwab workplace account and find the investment allocation page. Look for the option listed as your default or qualified default investment alternative, commonly referred to as a QDIA. If your plan uses a target date fund as the QDIA, note the glide path name, the expense ratio, and the underlying asset allocation. Then compare it against at least one alternative available in the same menu. Most Schwab plans offer a self-directed brokerage window that lets you buy individual ETFs or mutual funds, sometimes with additional transaction fees that range from zero to $49.99 per trade depending on your plan's configuration. If your default fund carries an expense ratio above 0.30%, it is almost certainly worth exploring lower-cost alternatives within the same plan. Schwab's own index funds and ETFs typically run between 0.02% and 0.07%. The S&P 500 index fund, for example, charges 0.01%. A total international stock index fund runs around 0.06%. When your employer matches a portion of your contribution, prioritize filling that match first, then shift any excess contributions toward the lowest-cost broad market index funds available. There is a nuance that most people miss. The default fund is not always the worst option, but it is rarely the best one for your specific situation. A 55-year-old who is three years from retirement should not be in the same target date fund as a 28-year-old starting their career, yet both are often defaulted into the 2055 fund simply because that is the closest label. Check the glide path carefully. If you are within ten years of your target retirement date and still in a fund labeled for 2055, you are likely carrying too much equity exposure relative to your actual timeline. Reallocate toward the appropriate target date or build a custom mix that reflects your real horizon.
Get the Full Details

What to Do If Your Plan Has Limited Options
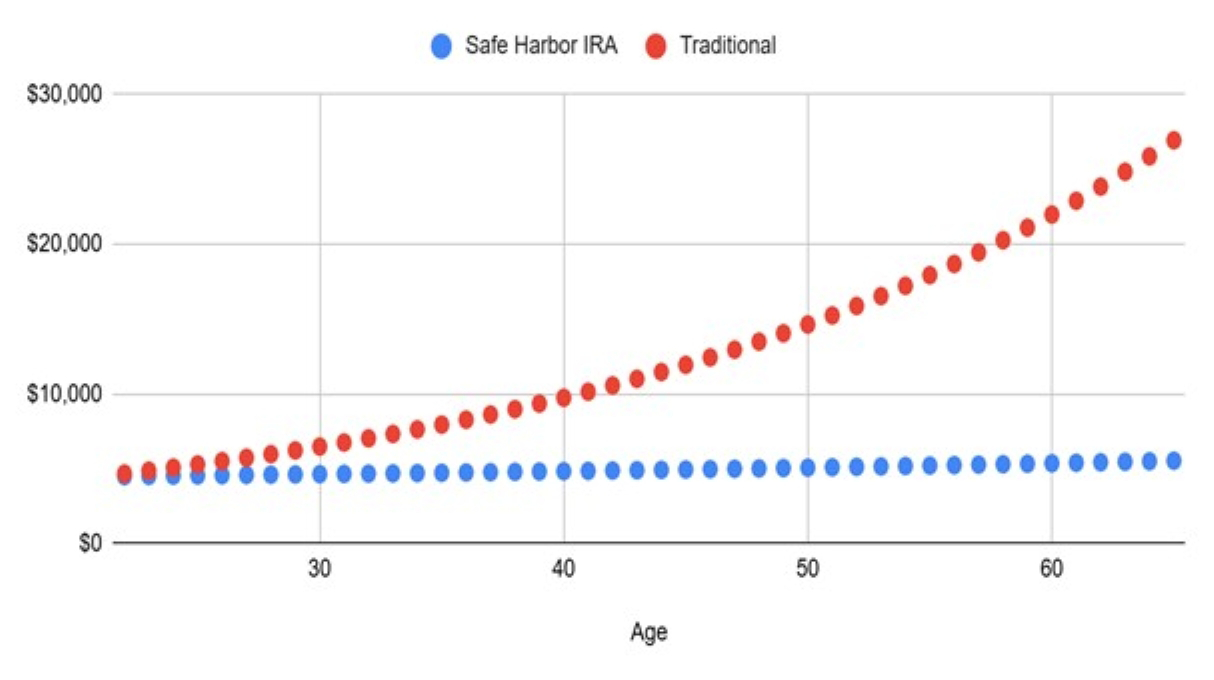
Some Schwab workplace plans offer only five or six investment choices. In those cases, your ability to optimize is constrained, but you are not completely stuck. The trick is to use the brokerage window if it is available and reasonably priced. If the window charges more than $25 per trade, it may still make sense for occasional rebalancing, but not for monthly contributions. In that scenario, pick the two or three lowest-cost funds and allocate across them manually. Another overlooked strategy is to adjust your contribution percentage rather than your fund selection when options are scarce. Increasing your deferral from 6% to 10% while staying in a mediocre default fund will usually produce better results than switching funds and reducing your contribution rate. The employer match is the immediate return, and every dollar of matched contribution compounds faster than any fee savings from a fund switch. I have seen this play out repeatedly. A client in a plan with only four options, all charging above 0.50%, increased her contribution by 3% and moved half of it into a Roth conversion through the brokerage window. She saved over $12,000 in lifetime taxes by age 65 compared to staying in the traditional default track. The hard truth is that default 401(k) choices at Schwab and other major providers will never be tailored to you. They are designed to be good enough to satisfy fiduciary standards and easy to administer at scale. Your job is to recognize the gap between good enough and optimal, then close it with deliberate adjustments. Review your allocation once a year, preferably after your employer sends the annual QDIA disclosure. If you cannot find that disclosure, request it directly from your plan administrator. Most Schwab plans provide it within five business days.
If your plan does not offer a brokerage window and the available funds all carry high fees, consider whether your employer is using a Schwab CoreSelect platform or a different Schwab retirement architecture. The CoreSelect lineup includes hundreds of no-load mutual funds with expense ratios that can drop below 0.10%, and many employers who use it do not automatically enroll participants in those options. Ask your HR or benefits team whether CoreSelect is active on your plan. If it is, you may already have access to far better choices than the default display suggests. If it is not, you can request that they add it, though that process typically requires a formal plan amendment and can take anywhere from three to eight months to implement. The longer you leave money in a default selection without review, the more costly the decision becomes. Not because the default is terrible, but because the opportunity cost compounds silently. Two percent in annual fees versus one percent does not look significant on a quarterly statement. Over thirty years, it is the difference between retiring with $1.2 million and $1.7 million. You do not need to become an investment expert. You just need to look at your default fund, check the expense ratio, compare it to what else is available, and move a portion of your contributions to the better option. That is the entire process.