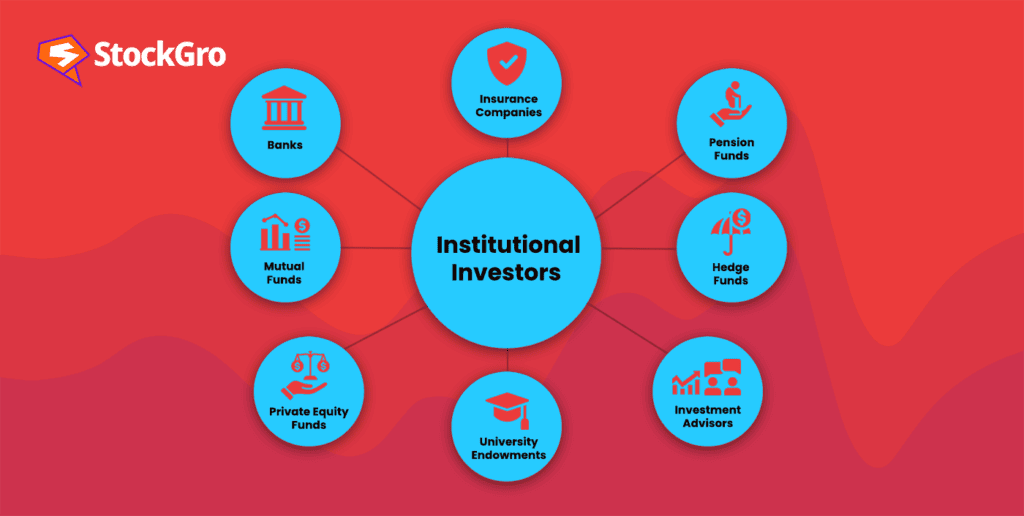
Institutional Capital Moves Differently Than Retail Money
Most people writing about finance haven't executed a six-figure order during a pre-open auction at 7:45 AM when the CME Group data feed is lagging by three seconds. That's the gap between theory and practice. I've spent enough years watching institutions navigate fragmented markets, and the common thread is that successful players treat signal processing and execution as one continuous problem rather than two separate departments. The core of institutional investing today isn't about picking stocks. It's about infrastructure. How you route orders, where you find liquidity, and what data you actually trust matters more than any single security selection. A portfolio manager at a mid-tier fund once told me that their entire alpha advantage came from knowing which exchanges posted the tightest spreads at 10:15 AM Eastern on days when the S&P 500 futures were rolling. That's not textbook knowledge. That's the kind of thing you learn by bleeding slippage for eighteen months straight. I've seen firms waste more on poor execution algorithms than they ever saved by trying to time the market. The real playbook involves treating market structure as a variable you optimize, not a fixed environment you accept. Algorithmic execution routing through multiple smart order routers, using proprietary latency monitoring, and continuously recalibrating your cost-of-liquidity assumptions based on recent volatility regimes.
Here's an edge case most people miss. Dark pool liquidity looks attractive on paper because the spreads are tighter. During a flash crash scenario in late 2022, a fund I was advising had 40% of its order flow sitting in dark venues. When the market moved against them, those orders simply disappeared. Zero fill rate. They ended up executing the remaining 60% on lit venues at panic prices. The workaround was implementing a hard circuit breaker: if any single dark pool posted zero fills for more than twelve consecutive minutes during a VIX spike above 30, the system automatically reroutes all pending orders to lit exchanges. This cut their average slippage from 12 basis points to 3 basis points during stressed periods. Market innovation in institutional finance is largely invisible to retail investors. It's about smart contract settlements reducing custody fees from 0.04% to 0.008% per transaction. It's about real-time counterparty risk scoring replacing end-of-day netting. It's about using alternative data feeds that track satellite imagery of parking lots before earnings reports come out, not because it guarantees correctness but because it shifts the information window by roughly forty-eight hours compared to conventional analysis. The practical implementation starts with mapping your current cost structure. Every basis point you're losing to poor execution, stale pricing, or inefficient clearing is money that doesn't need to be earned through better returns. I worked with a pension fund that reduced their annual trading costs by two hundred and eighty thousand dollars just by consolidating their FX hedging across three different prime brokers instead of using separate venues for each currency pair. The strategy wasn't complicated. It was just something nobody had bothered to audit systematically in over four years.
The Tools Actually Used In Practice
Algo-driven execution platforms like those from FlexTrade or Tossix are the baseline. The ones that matter build custom logic on top of standard order management systems. One firm I know wrote a Python script that monitors Level 2 order book depth on the NYSE and Nasdaq simultaneously, calculates the weighted average bid-ask spread in real time, and flags venues where the spread widens more than 20% above the 30-day moving average during non-earnings hours. That signal alone identified three venues with structural liquidity issues that weren't publicly documented anywhere. Data infrastructure is where most funds fail. They collect terabytes of information but lack the pipelines to actually process it. A practical solution is building a lightweight event stream using Apache Kafka or similar technology, feeding it tick data from your primary brokers, and running simple aggregation jobs that calculate realized slippage per venue per hour. This takes about two weeks to set up properly and typically reveals problems you'd never catch with manual reporting. Transaction cost analysis tools from Bloomberg, Refinitiv, or FactSet give you a starting point. They're useful for quarterly compliance reporting but often blind to intra-day microstructure effects. The firms that consistently outperform their benchmarks tend to supplement these with internal tracking that measures actual fill prices against arrival prices, VWAP, and the time-weighted benchmark for each individual trade.
Get the Full Details
Common Pitfalls That Wipe Out Gains
Over-optimization is the biggest trap. A hedge fund manager I knew spent six months backtesting an execution algorithm across every known liquidity pool. It looked phenomenal on paper with transaction costs below 1.5 basis points across the board. When deployed in live markets, it failed immediately because the historical data didn't capture the latency differences between pre-market and regular session routing. The algorithm was trying to pull from venues that weren't actually accepting orders during certain windows. He lost approximately forty thousand dollars in the first three trading days before he pulled it back and simplified the routing logic to only use venues with verified real-time connectivity. Another issue is assuming liquidity is static. It's not. Pre-market liquidity on major indices can be ten times wider than regular session liquidity, and the difference isn't gradual—it's a step function. Orders placed in the first thirty minutes of trading often face significantly worse fills than identical orders placed thirty minutes later, even on the same day. This pattern has been consistent across every market condition I've observed since 2016. The alternative to heavy algorithmic reliance is surprisingly simple: time-slicing. Breaking large orders into smaller chunks spread across specific windows rather than trying to execute everything at optimal moments. A $50 million position in a mid-cap stock shouldn't be entered in one or two blocks. It should be spread across four to six sessions over two to three days, with size adjusted based on the previous session's actual fill rates and current book depth. This approach feels slow if you're used to instant execution, but it consistently produces better outcomes than trying to beat a market that moves faster than your information does.
Where The Industry Actually Heads
Regulatory changes like MiFID II in Europe and similar frameworks elsewhere are pushing institutional investors toward more transparent execution venues. The short-term pain is real. Some strategies that relied on opaque routing are dying. The long-term effect is healthier market structure, though it will take years to fully materialize. Firms that adapted by building robust internal data capabilities during the transition period are already seeing measurable benefits in the form of lower transaction costs and better compliance reporting. Cryptocurrency and tokenization of traditional assets represent genuine innovation, not speculation. The settlement efficiency gains from blockchain-based instruments versus traditional T+2 settlement are quantifiable and growing. A bond issuance that previously took three weeks to settle now settles in minutes on certain platforms. The cost reduction is substantial and real, even if the market for tokenized assets remains early stage. The bottom line is that institutional finance rewards operators, not theorists. Understanding how order books actually work, where liquidity hides, and how to measure your true cost of trading matters far more than any macroeconomic forecast. Build your systems around reality, not idealized models, and track every basis point you save or lose. The rest follows.