Getting Your Payment Processing Right
Most merchants sign up for a payment processor without reading the contract, then spend three years figuring out why their rates don't match what they were quoted. Connectpay is one of the mid-market processors that gives you decent flexibility if you actually take the time to understand how it's structured. I've been working with payment infrastructure long enough to know that the difference between a smooth operation and a headache is usually in the configuration, not the product itself. The phrase shows up in a lot of search results because people are looking for exactly what this is - a practical walkthrough of how to set up Connectpay for maximum benefit. Connectpay itself is a payment gateway and processing solution aimed at small to mid-size businesses. It handles credit card processing, recurring billing, e-commerce integrations, and point-of-sale solutions. The real value isn't in signing up. It's in configuring it properly from day one. I'm going to walk through the setup, the common mistakes, and the specific settings that most people miss. This will be more detailed than most guides because the people who skip details are the same people calling support at 2 AM wondering why their settlements are delayed.
The Setup Process
When you create a Connectpay account, you'll go through standard KYC verification. Your documentation needs to include business registration, tax ID, bank account details, and identification for the authorized representative. Processing typically takes 1 to 3 business days. If your application gets flagged, it's usually because the business type doesn't match your website or because your banking information doesn't align with your registered entity. Get that right upfront and you avoid unnecessary delays. Once approved, you'll get access to the merchant dashboard. The first thing you should do before handling a single transaction is set up your settlement schedule. Connectpay offers next-day settlement as standard, but you can opt into same-day settlement if your volume justifies the extra fee. For most businesses processing under $5,000 per day, next-day is fine. If you're pushing above that threshold, same-day settlement can improve cash flow enough to cover the per-transaction cost.
Rate Structures and What They Actually Mean
Connectpay uses a tiered pricing model that comes in three levels: qualified, mid-qualified, and non-qualified rates. This is where most merchants get confused. The qualified rate is the base rate advertised in marketing materials. Mid-qualified applies to transactions that don't fully meet interchange criteria - things like corporate cards, rewards cards, or international transactions. Non-qualified covers the rest, including certain B2B transactions and cards issued outside your region. Here's what nobody tells you clearly: your effective rate is never the qualified rate. It's a blended average across all three tiers. If 30% of your transactions fall into mid or non-qualified, your actual cost is higher than what was quoted. I had a client who was complaining about unexpected fees for months. We pulled the transaction report and found that 42% of her sales were hitting the non-qualified tier because she was accepting corporate purchase cards without understanding the interchange structure. Switching her checkout flow to require address verification on those transactions dropped her non-qualified rate from 42% to about 18%. Connectpay also charges a monthly gateway fee and an annual processing fee. These are standard across most processors. What matters more is the chargeback fee, which runs around $20 to $25 per dispute. That's steep enough that prevention matters more than cure.
Get the Full Details
Integrations and Technical Setup
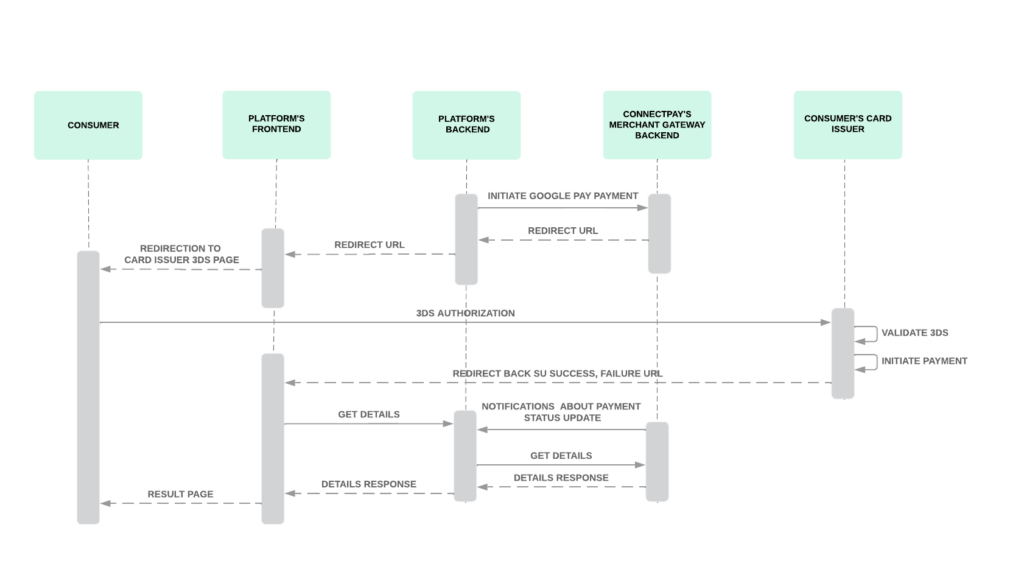
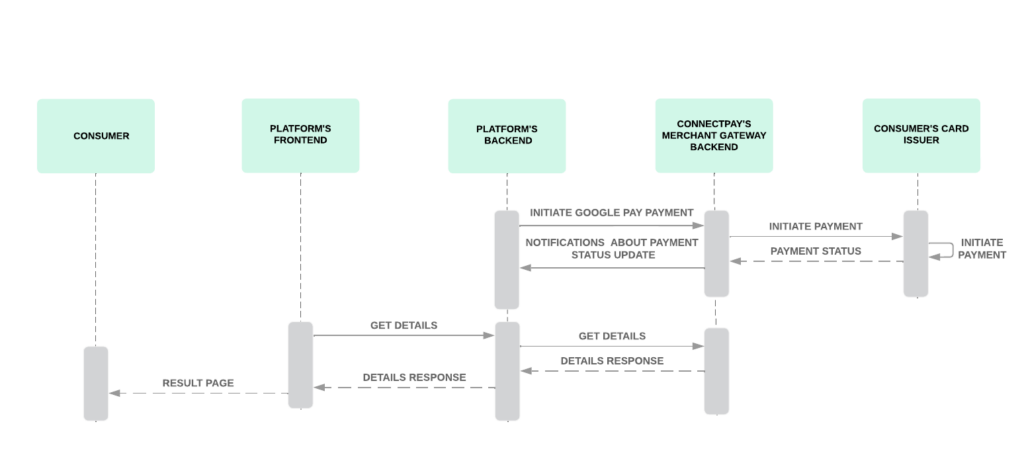
Connectpay supports REST API integration, which means it works with most e-commerce platforms and custom builds. The key integration points are your checkout page, your order management system, and your reconciliation process. If you're using Shopify, WooCommerce, or Magento, there are pre-built plugins that handle the bulk of the work. For custom integrations, you'll need to set up the API keys, configure your webhook endpoints for transaction notifications, and implement the 3D Secure flow if you're processing international cards. The webhook configuration is where things usually go wrong. Connectpay sends transaction events to your server, and if your endpoint isn't set up correctly or if you're not acknowledging responses within the timeout window, you'll get duplicate charges or failed payments. I've seen this happen repeatedly. The fix is straightforward: implement idempotency keys on your payment requests and set up a retry queue for webhook failures. That alone prevents most integration issues.
Recurring Billing Setup
If you're running a subscription business, Connectpay has a recurring billing module built in. You set up the billing cycle, define the amount and frequency, and store the customer's payment method as a token. The tokenization is handled by Connectpay's secure vault, so you never touch raw card data. This is important for PCI compliance. If you're storing card numbers yourself, you're opening yourself up to liability that a proper vault eliminates. The common pitfall here is dunning management. When a subscription payment fails, Connectpay will retry based on your configured schedule. But the default retry logic is pretty basic. You'll want to customize it - add delays between retries, send customer notifications at each failure stage, and set a maximum retry count before canceling the subscription. I configured a dunning flow for a client that looked like this: retry on day 1, retry on day 3, notify customer on day 5, retry on day 7, cancel on day 10 if still failed. That structure recovered about 23% of otherwise lost subscriptions compared to their previous processor's default 2-retry policy.
Chargeback Management
Chargebacks are inevitable. The question is how you handle them. Connectpay provides a chargeback management interface where you can submit evidence, track dispute status, and respond to representment requests. The interface is functional but not elegant. It gets the job done if you stay on top of it. Here's the important part: you have 30 days from the chargeback filing date to respond. Missing that deadline means automatic loss of the dispute and the $20-to-$25 fee goes straight to the processor. I recommend setting up calendar reminders for all active disputes and assigning someone to review chargeback notifications daily. The cost of a minute of attention per day is nothing compared to losing a $500 dispute because you missed the deadline.
Reporting and Reconciliation
Connectpay offers daily settlement reports and monthly statements in CSV and PDF formats. The daily report includes transaction IDs, amounts, fees, net deposits, and chargeback activity. Cross-referencing this with your bank deposits should be a daily routine. Mismatches between the report and your actual bank balance usually indicate one of three things: a pending transaction that hasn't settled yet, a refund that was processed but not recorded, or a dispute that was filed but not yet reflected in the report. For reconciliation, I recommend importing the daily CSV into your accounting system and running an automated match. Tools like QuickBooks or Xero can handle this if you map the Connectpay fields correctly. The initial mapping takes about 20 minutes. After that, reconciliation should take less than 5 minutes per day.
Common Configuration Mistakes
I've seen the same errors come up repeatedly across different merchant accounts. The first is leaving the default routing rules unchanged. Connectpay allows you to route transactions to different processing paths based on card type, amount, or region. If you don't configure this, every transaction goes through the default path, which may not be the most cost-effective route for your specific mix. The second mistake is not enabling address verification service (AVS) and CVV checking. These are basic fraud prevention tools that are disabled by default on some configurations. Without them, you're accepting every transaction that presents a valid card number and expiry date. That's fine if you're processing $5 transactions and don't expect chargebacks. It's not fine if you're processing anything meaningful. The third mistake is ignoring the risk profile settings. Connectpay monitors transaction patterns and flags unusual activity. If your business has seasonal spikes or runs promotions that increase transaction volume, you should pre-notify your account manager. Otherwise, the system may temporarily suspend your account pending review, which looks unprofessional to your customers and costs you sales during the window.
Scaling Beyond Connectpay
Connectpay works well for businesses processing between $50,000 and $500,000 per month. Below that range, the monthly fees and setup complexity may not be worth it compared to simpler options like Stripe or Square. Above that range, you'll likely negotiate better rates with a dedicated acquiring bank or a processor that offers volume-based pricing tiers. The transition is usually smooth because Connectpay supports data export and migration tools. One thing to watch is interchange++ pricing. If you're on a flat-rate plan, you're paying a premium for simplicity. As your volume grows, switching to interchange++ can save you between 0.5% and 1.5% on total processing costs. Connectpay offers both models, and you can switch between them, but the change affects your billing structure immediately. Make sure you model the difference before making the switch.
Support and Documentation
Connectpay's support channels include email, phone, and a knowledge base. The knowledge base is adequate but not comprehensive. For complex issues, phone support is faster. Response times average 2 to 4 hours during business hours. After-hours support is available but with longer wait times. I've had cases where a technical issue took 24 hours to resolve because it required escalation to their development team. That's normal for mid-tier processors. If you need guaranteed 1-hour response times, you're in enterprise territory and should look elsewhere. The documentation covers the standard integration paths but doesn't go deep into edge cases. If you're running into unusual scenarios - like split settlements, partial refunds across multiple transactions, or multi-currency handling with dynamic conversion - you'll often need to reach out to support directly rather than finding answers in the docs.
Final Practical Notes
The biggest advantage Connectpay offers over cheaper alternatives is flexibility in configuration. You can adjust rates, set up custom routing rules, manage recurring billing schedules, and handle chargebacks through a single dashboard. The trade-off is that you need to understand what you're doing. The platform won't make decisions for you the way some turnkey solutions do. If you're comfortable managing your own payment infrastructure and want control over your processing costs, Connectpay is a solid choice. If you want something that requires zero configuration and just works out of the box, look at simpler platforms first. There's no shame in starting simpler and upgrading when your volume justifies the complexity.